This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
Life & Health
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
1. General Insurance Concepts
2. Producer Roles and Receipt Types
3. Principles of Life Insurance
4. Underwriting
5. Term Life Insurance
6. Whole Life Insurance
7. Variable Insurance Products
8. Group Life Insurance
9. Life Insurance Provisions
10. Annuities
10.1 Annuity Basics and Accumulation
10.2 Payouts and Advanced Options
11. Taxation of Life Insurance Products
12. Qualified Retirement Plans
13. Health Insurance Basics
14. Required Policy Provisions
15. Optional Policy Provisions
16. Medical Expense Insurance
17. Group Health Insurance
18. The Affordable Care Act (ACA)
19. Disability Income Insurance
20. Accidental Death and Dismemberment Insurance
21. Long Term Care Insurance
22. Dental Insurance
23. Section 125 Plans and Limited Policies
24. Federal Government Programs
25. Medigap and Medicaid
26. Health Insurance Taxation
Wrapping Up
Achievable logoAchievable logo
10.1 Annuity Basics and Accumulation
Achievable Life & Health
10. Annuities

Annuity Basics and Accumulation

8 min read
Font
Discuss
Share
Feedback

Annuities originated as a life income settlement option offered by life insurance policies. Annuities are insurance products, but they aren’t designed to provide protection in the event of premature death. Instead, an annuity protects against living a long time and outliving your financial resources. Annuity payments are guaranteed for a fixed period - commonly for life - so the annuitant can’t outlive the stream of monthly payments.

Annuities are often used to accumulate funds for retirement. As with life insurance, premiums paid aren’t tax-deductible, but they grow tax-deferred until withdrawn. Because of tax-deferred growth and unlimited contribution amounts, annuities are popular with people in high tax brackets.

Annuities may be purchased with a lump sum investment (single premium annuity) or with periodic payments. A single premium annuity may also be an immediate annuity if the owner elects to begin receiving payments right away. More commonly, an annuity is purchased over time with periodic payments and payments begin at a future date; this is a flexible premium deferred annuity.

The accumulation stage is the period when the owner is investing money into the contract.

  • In a variable annuity, the value is measured in accumulation units tied to separate account investments (insurance-dedicated mutual funds).
  • In a fixed or indexed annuity, the account value grows based on the insurer’s general account interest or an index formula, not accumulation units.

During the accumulation stage, the terms of the contract are flexible. Unlike life insurance, there’s no required premium schedule with an annuity, though most contracts impose minimum initial and subsequent contributions. The owner can choose how much and how often to invest, may withdraw funds, and may also terminate the contract during the accumulation stage.

A withdrawal during the accumulation stage is a taxable event. The owner of the annuity contract has an ordinary income tax liability on any withdrawal from an annuity in excess of his/her cost basis. Any taxable withdrawal is also subject to a 10% penalty if the owner is under age 59½.

Sidenote
Know this...

Before age 59½, the 10% penalty generally applies to taxable withdrawals during the accumulation stage. Once the contract is annuitized for the annuitant’s life or life expectancy, the penalty does not apply to the annuity payments, even if they are received before age 59½.

If the owner of an annuity dies during the accumulation stage, the beneficiary will receive the greater of:

  1. The cash value of the contract on date of death
  2. The decedent’s cost basis

If the cash value exceeds the cost basis, the beneficiary will owe ordinary income tax on the excess amount above the decedent’s cost basis. However, the 10% early withdrawal penalty does not apply.

When the owner of an annuity elects to begin receiving guaranteed monthly payments from the annuity, the contract is annuitized. The accumulation units are converted into annuity units, and the contract enters the annuity stage.

Annuitization shouldn’t be taken lightly. It’s irreversible and can’t be altered or canceled. Upon annuitization, the owner relinquishes all rights to the cash value in the contract in exchange for the insurance company’s payout guarantee.

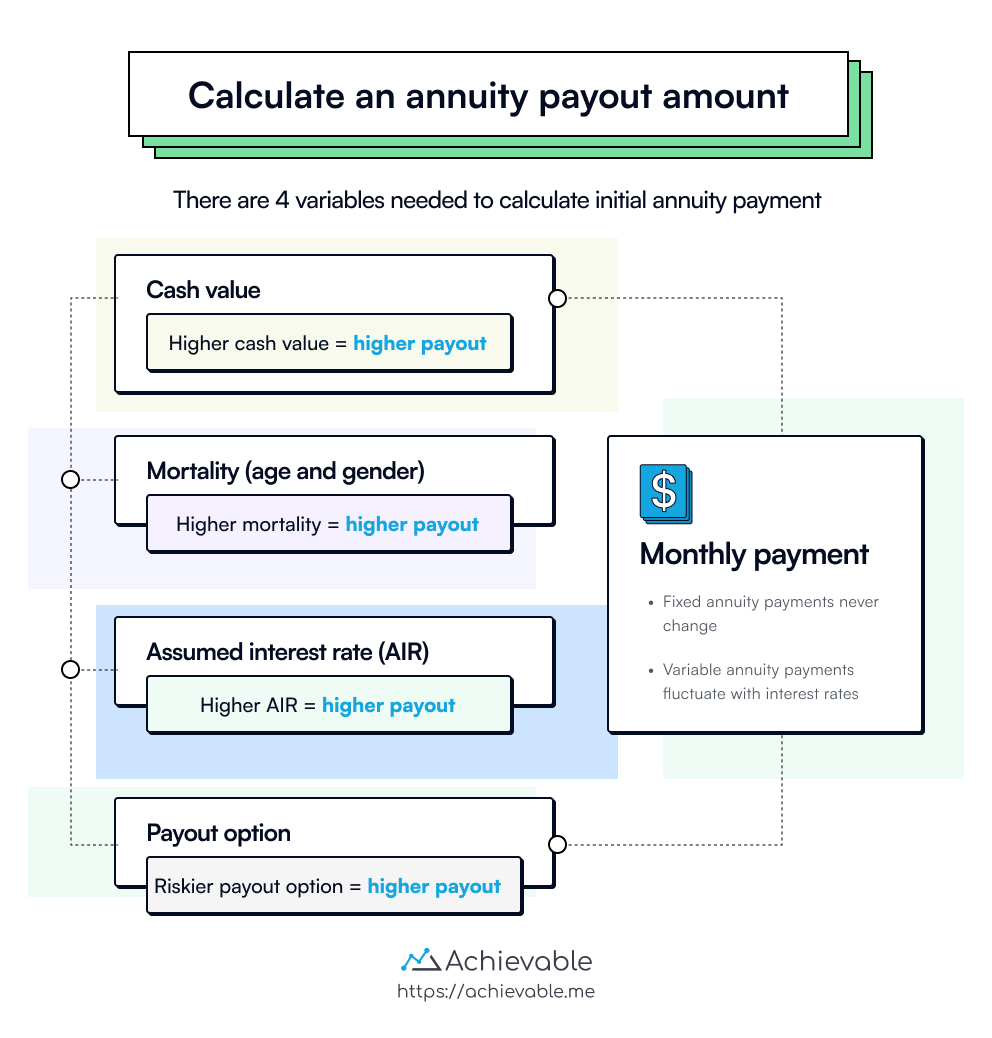
The four variables required to calculate the amount of an annuitant’s initial payment are:

  1. Life expectancy of the annuitant (age and gender)
  2. Assumed interest rate (AIR)
  3. Cash value of the annuity contract
  4. Payout option

Requirements to calculate an annuity initial payment

Lesson summary

Annuities originated as a life income settlement option from life insurance policies. They’re designed to protect against outliving financial resources by offering guaranteed payments for a fixed period - commonly for life - while not providing protection against premature death.

  • Annuities are used to accumulate funds for retirement. Premiums aren’t tax-deductible, but they grow tax-deferred until withdrawn, which makes them popular with individuals in high tax brackets.
  • Annuities can be purchased with a lump sum or periodic payments, including single premium immediate annuities and flexible premium deferred annuities.
  • During the accumulation phase, the owner has flexibility: there’s no required premium schedule (though minimums apply), and the owner may withdraw funds or terminate the contract. Withdrawals are taxable events.
  • If the owner dies during the accumulation phase, the beneficiary receives the greater of the cash value or the decedent’s cost basis, with ordinary income tax due on any amount above the cost basis.

When the annuity owner chooses to receive guaranteed payments, the contract is annuitized. At that point, the owner gives up access to the cash value in exchange for the insurance company’s payout guarantee.

  • Calculating initial annuity payments depends on life expectancy, assumed interest rate (AIR), cash value, and payout option.

  • Annuity payments are taxed differently based on annuitization status, and there’s no 10% penalty on payments annuitized for life or life expectancy.

Annuities are complex financial products with tax implications and various options for investors seeking to manage retirement income and risk.

Chapter vocabulary

Definitions
Accumulation Stage
The period during which the owner of a deferred annuity makes payments to build up assets.
Annuitant
The person(s) who receives the payment from an annuity contract.
Annuitization
The conversion of the account balance of an annuity contract to income payments.
Annuity
A life insurance product that pays periodic income benefits for a specific period of time or over the course of the annuitant’s lifetime.
Annuity Beneficiary
In certain types of annuities, a person who receives annuity contract payments if the annuity owner or annuitant dies while payments are still due.
Annuity Contract Owner
The person or entity that purchases an annuity and has all rights to the contract. Usually, but not always, the annuitant.
Annuity Death Benefits
If an annuity contract owner dies before annuitization, the beneficiary typically receives at least the account value. Most contracts guarantee the greater of the current account value or the total premiums paid (cost basis), adjusted for withdrawals.
Annuity Issuer
The insurance company that issues the annuity.
Annuity Prospectus
Legal document providing detailed information about variable annuity contracts.
Deferred Annuity
An annuity on which payments to the annuitant are delayed until a specified future date.
Fixed Period Option
An annuity payout option under which the beneficiary receives a regular income for a specified period of time.
Flexible Premium Annuity
An annuity that allows the contract owner the option of whether to pay the annuity premiums following the establishment of the annuity.
Immediate Annuity
A type of annuity purchased with a lump sum, usually at retirement. Payments begin in the next payment period; can be fixed or variable.
Single Premium Annuity
An annuity that is paid in full upon purchase.

Purpose & Structure of Annuities

  • Protects against outliving assets (opposite risk of life insurance); guarantees payments for fixed period or life
  • Premiums not tax-deductible, but grow tax-deferred; no contribution limits, so popular with high tax brackets
  • Purchase types: single premium (lump sum) vs. flexible premium (periodic payments); immediate (payments start right away) vs. deferred (payments begin later)

Accumulation Stage

  • Period when owner invests funds into the contract
  • Variable annuities: value tracked in accumulation units tied to separate account investments
  • Fixed/indexed annuities: growth based on insurer’s general account rate or index formula
  • Flexible terms: no required premium schedule (minimums may apply); owner can withdraw or terminate

Taxation & Withdrawals

  • Withdrawals during accumulation = taxable event (ordinary income tax on amount above cost basis)
  • 10% penalty applies if under age 59½, only during accumulation stage
  • Once annuitized for life/life expectancy, penalty no longer applies even if before 59½

Death During Accumulation Stage

  • Beneficiary receives greater of: cash value at death, or decedent’s cost basis
  • Ordinary income tax owed on excess above cost basis
  • No 10% early withdrawal penalty applies

Annuitization & Payout Calculation

  • Annuitization = converting accumulation units into annuity units; contract enters annuity stage
  • Irreversible: owner gives up cash value access in exchange for insurer’s guaranteed payout
  • Initial payment amount depends on four factors:
    • Annuitant’s life expectancy (age, gender)
    • Assumed interest rate (AIR)
    • Cash value of contract
    • Payout option chosen

Key Vocabulary

  • Annuitant: person receiving annuity payments; Annuity Contract Owner: purchaser with contract rights (often same as annuitant)
  • Deferred vs. Immediate Annuity: payments delayed to future date vs. starting next period after lump-sum purchase
  • Annuity Death Benefits: beneficiary gets greater of account value or cost basis if owner dies pre-annuitization
  • Fixed Period Option: payout option providing income for a specified time span

Sign up for free to take 23 quiz questions on this topic

Previous
Next  | 10.2 Payouts and Advanced Options
All rights reserved ©2016 - 2026 Achievable, Inc.

Annuity Basics and Accumulation

Annuities originated as a life income settlement option offered by life insurance policies. Annuities are insurance products, but they aren’t designed to provide protection in the event of premature death. Instead, an annuity protects against living a long time and outliving your financial resources. Annuity payments are guaranteed for a fixed period - commonly for life - so the annuitant can’t outlive the stream of monthly payments.

Annuities are often used to accumulate funds for retirement. As with life insurance, premiums paid aren’t tax-deductible, but they grow tax-deferred until withdrawn. Because of tax-deferred growth and unlimited contribution amounts, annuities are popular with people in high tax brackets.

Annuities may be purchased with a lump sum investment (single premium annuity) or with periodic payments. A single premium annuity may also be an immediate annuity if the owner elects to begin receiving payments right away. More commonly, an annuity is purchased over time with periodic payments and payments begin at a future date; this is a flexible premium deferred annuity.

The accumulation stage is the period when the owner is investing money into the contract.

  • In a variable annuity, the value is measured in accumulation units tied to separate account investments (insurance-dedicated mutual funds).
  • In a fixed or indexed annuity, the account value grows based on the insurer’s general account interest or an index formula, not accumulation units.

During the accumulation stage, the terms of the contract are flexible. Unlike life insurance, there’s no required premium schedule with an annuity, though most contracts impose minimum initial and subsequent contributions. The owner can choose how much and how often to invest, may withdraw funds, and may also terminate the contract during the accumulation stage.

A withdrawal during the accumulation stage is a taxable event. The owner of the annuity contract has an ordinary income tax liability on any withdrawal from an annuity in excess of his/her cost basis. Any taxable withdrawal is also subject to a 10% penalty if the owner is under age 59½.

Sidenote
Know this...

Before age 59½, the 10% penalty generally applies to taxable withdrawals during the accumulation stage. Once the contract is annuitized for the annuitant’s life or life expectancy, the penalty does not apply to the annuity payments, even if they are received before age 59½.

If the owner of an annuity dies during the accumulation stage, the beneficiary will receive the greater of:

  1. The cash value of the contract on date of death
  2. The decedent’s cost basis

If the cash value exceeds the cost basis, the beneficiary will owe ordinary income tax on the excess amount above the decedent’s cost basis. However, the 10% early withdrawal penalty does not apply.

When the owner of an annuity elects to begin receiving guaranteed monthly payments from the annuity, the contract is annuitized. The accumulation units are converted into annuity units, and the contract enters the annuity stage.

Annuitization shouldn’t be taken lightly. It’s irreversible and can’t be altered or canceled. Upon annuitization, the owner relinquishes all rights to the cash value in the contract in exchange for the insurance company’s payout guarantee.

The four variables required to calculate the amount of an annuitant’s initial payment are:

  1. Life expectancy of the annuitant (age and gender)
  2. Assumed interest rate (AIR)
  3. Cash value of the annuity contract
  4. Payout option

Requirements to calculate an annuity initial payment

Lesson summary

Annuities originated as a life income settlement option from life insurance policies. They’re designed to protect against outliving financial resources by offering guaranteed payments for a fixed period - commonly for life - while not providing protection against premature death.

  • Annuities are used to accumulate funds for retirement. Premiums aren’t tax-deductible, but they grow tax-deferred until withdrawn, which makes them popular with individuals in high tax brackets.
  • Annuities can be purchased with a lump sum or periodic payments, including single premium immediate annuities and flexible premium deferred annuities.
  • During the accumulation phase, the owner has flexibility: there’s no required premium schedule (though minimums apply), and the owner may withdraw funds or terminate the contract. Withdrawals are taxable events.
  • If the owner dies during the accumulation phase, the beneficiary receives the greater of the cash value or the decedent’s cost basis, with ordinary income tax due on any amount above the cost basis.

When the annuity owner chooses to receive guaranteed payments, the contract is annuitized. At that point, the owner gives up access to the cash value in exchange for the insurance company’s payout guarantee.

  • Calculating initial annuity payments depends on life expectancy, assumed interest rate (AIR), cash value, and payout option.

  • Annuity payments are taxed differently based on annuitization status, and there’s no 10% penalty on payments annuitized for life or life expectancy.

Annuities are complex financial products with tax implications and various options for investors seeking to manage retirement income and risk.

Chapter vocabulary

Definitions
Accumulation Stage
The period during which the owner of a deferred annuity makes payments to build up assets.
Annuitant
The person(s) who receives the payment from an annuity contract.
Annuitization
The conversion of the account balance of an annuity contract to income payments.
Annuity
A life insurance product that pays periodic income benefits for a specific period of time or over the course of the annuitant’s lifetime.
Annuity Beneficiary
In certain types of annuities, a person who receives annuity contract payments if the annuity owner or annuitant dies while payments are still due.
Annuity Contract Owner
The person or entity that purchases an annuity and has all rights to the contract. Usually, but not always, the annuitant.
Annuity Death Benefits
If an annuity contract owner dies before annuitization, the beneficiary typically receives at least the account value. Most contracts guarantee the greater of the current account value or the total premiums paid (cost basis), adjusted for withdrawals.
Annuity Issuer
The insurance company that issues the annuity.
Annuity Prospectus
Legal document providing detailed information about variable annuity contracts.
Deferred Annuity
An annuity on which payments to the annuitant are delayed until a specified future date.
Fixed Period Option
An annuity payout option under which the beneficiary receives a regular income for a specified period of time.
Flexible Premium Annuity
An annuity that allows the contract owner the option of whether to pay the annuity premiums following the establishment of the annuity.
Immediate Annuity
A type of annuity purchased with a lump sum, usually at retirement. Payments begin in the next payment period; can be fixed or variable.
Single Premium Annuity
An annuity that is paid in full upon purchase.
Key points

Purpose & Structure of Annuities

  • Protects against outliving assets (opposite risk of life insurance); guarantees payments for fixed period or life
  • Premiums not tax-deductible, but grow tax-deferred; no contribution limits, so popular with high tax brackets
  • Purchase types: single premium (lump sum) vs. flexible premium (periodic payments); immediate (payments start right away) vs. deferred (payments begin later)

Accumulation Stage

  • Period when owner invests funds into the contract
  • Variable annuities: value tracked in accumulation units tied to separate account investments
  • Fixed/indexed annuities: growth based on insurer’s general account rate or index formula
  • Flexible terms: no required premium schedule (minimums may apply); owner can withdraw or terminate

Taxation & Withdrawals

  • Withdrawals during accumulation = taxable event (ordinary income tax on amount above cost basis)
  • 10% penalty applies if under age 59½, only during accumulation stage
  • Once annuitized for life/life expectancy, penalty no longer applies even if before 59½

Death During Accumulation Stage

  • Beneficiary receives greater of: cash value at death, or decedent’s cost basis
  • Ordinary income tax owed on excess above cost basis
  • No 10% early withdrawal penalty applies

Annuitization & Payout Calculation

  • Annuitization = converting accumulation units into annuity units; contract enters annuity stage
  • Irreversible: owner gives up cash value access in exchange for insurer’s guaranteed payout
  • Initial payment amount depends on four factors:
    • Annuitant’s life expectancy (age, gender)
    • Assumed interest rate (AIR)
    • Cash value of contract
    • Payout option chosen

Key Vocabulary

  • Annuitant: person receiving annuity payments; Annuity Contract Owner: purchaser with contract rights (often same as annuitant)
  • Deferred vs. Immediate Annuity: payments delayed to future date vs. starting next period after lump-sum purchase
  • Annuity Death Benefits: beneficiary gets greater of account value or cost basis if owner dies pre-annuitization
  • Fixed Period Option: payout option providing income for a specified time span

More from Annuities

  • Payouts and Advanced Options