Achievable logoAchievable logo
Life & Health
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
1. General Insurance Concepts
2. Producer Roles and Receipt Types
3. Principles of Life Insurance
4. Underwriting
5. Term Life Insurance
6. Whole Life Insurance
7. Variable Insurance Products
8. Group Life Insurance
9. Life Insurance Provisions
10. Annuities
10.1 Annuity Basics and Accumulation
10.2 Payouts and Advanced Options
11. Taxation of Life Insurance Products
12. Qualified Retirement Plans
13. Health Insurance Basics
14. Required Policy Provisions
15. Optional Policy Provisions
16. Medical Expense Insurance
17. Group Health Insurance
18. The Affordable Care Act (ACA)
19. Disability Income Insurance
20. Accidental Death and Dismemberment Insurance
21. Long Term Care Insurance
22. Dental Insurance
23. Section 125 Plans and Limited Policies
24. Federal Government Programs
25. Medigap and Medicaid
26. Health Insurance Taxation
Wrapping Up
Achievable logoAchievable logo
10.2 Payouts and Advanced Options
Achievable Life & Health
10. Annuities

Payouts and Advanced Options

8 min read
Font
Discuss
Share
Feedback

The available annuity payout options are as follows:

  • Life income (straight): This option typically provides the highest monthly payment, but it also carries the most longevity risk for the insurer. Payments are guaranteed for the annuitant’s lifetime and stop at the annuitant’s death.

  • Period certain (fixed period annuity): This option provides payments for a fixed period (for example, 10 or 20 years). If the annuitant dies during that period, a beneficiary receives the remaining payments. If the annuitant lives beyond the period, payments stop when the period ends.

  • Life annuity with period certain: Payments are guaranteed for the annuitant’s lifetime or for a specified period (for example, 10 or 20 years), whichever is longer. If the annuitant dies during the guaranteed period, the beneficiary receives the remaining payments. If the annuitant lives beyond the period, payments continue for life.

  • Refund: This is the most conservative option and typically has the lowest payments. If the annuitant dies before receiving payments equal to the contract’s value at annuitization, the beneficiary receives the remaining balance. Refunds may be paid either in a lump sum (cash refund) or in continued installments (installment refund).

  • Joint life: Covers two or more annuitants, but payments stop at the first annuitant’s death. Because payments end sooner, it pays more per month than joint and survivor.

  • Joint and survivor (joint and last survivor): This payout option covers two or more people, commonly spouses. The contract pays monthly as long as at least one annuitant is living. Depending on the contract, the payment may stay level or be reduced after the first annuitant’s death.
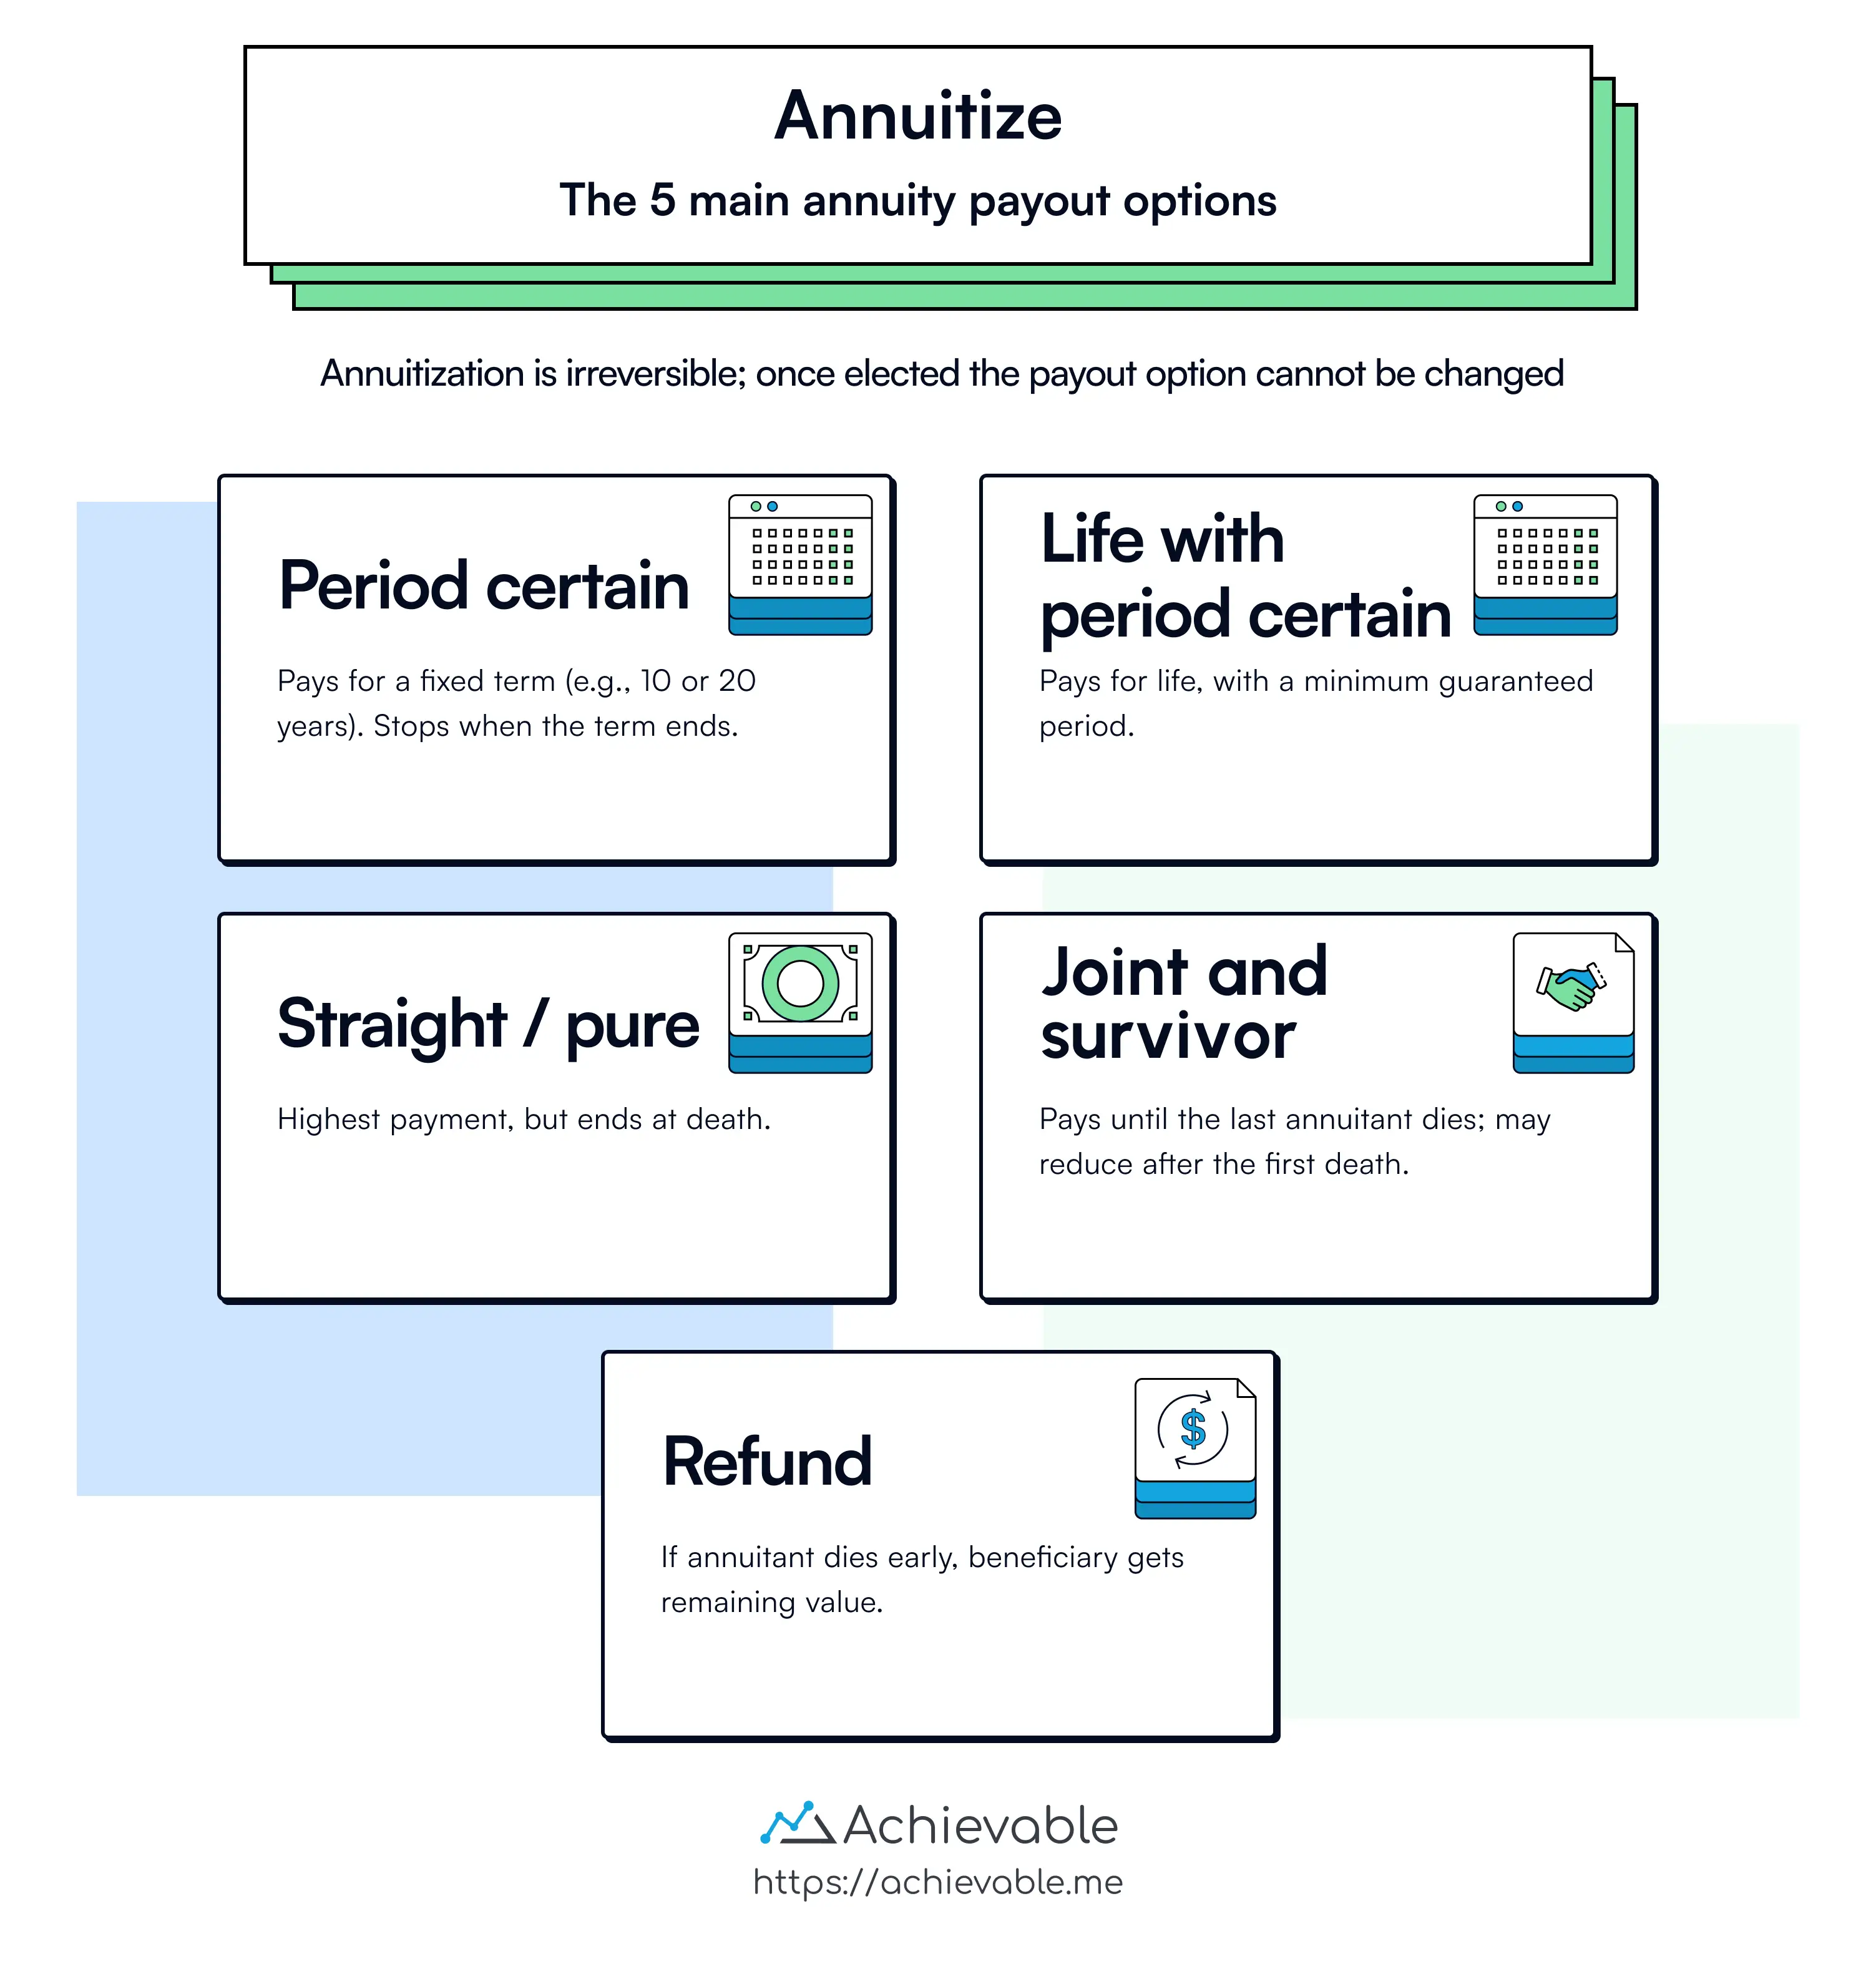
Available annuity payout options

Taxation of annuity payments differs from withdrawals during the accumulation stage. Once a contract has been annuitized, the 10% early withdrawal penalty no longer applies because payments are treated as a scheduled annuity stream, not as withdrawals.

For income taxes, only the portion of each payment that represents growth is taxable. Fixed annuity payments stay the same each month, while variable annuity payments may change based on investment performance.

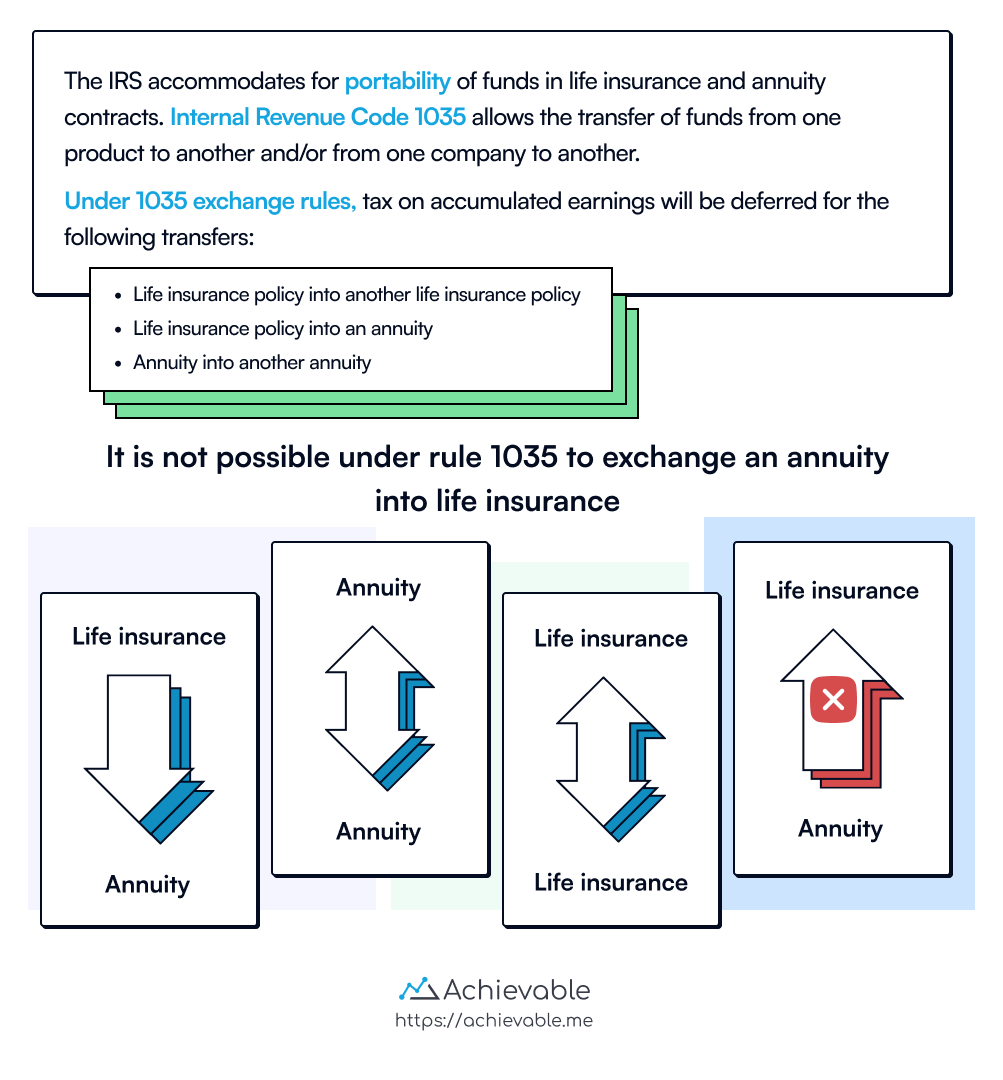
The IRS provides portability for certain life insurance and annuity contracts. Internal Revenue Code 1035 allows the transfer of funds from one product to another, or from one company to another. Under 1035 exchange rules, tax on accumulated earnings is deferred for the following transfers:

  • Life insurance policy into another life insurance policy
  • Life insurance policy into an annuity
  • Annuity into another annuity
Sidenote
Know this...

It is not possible under rule 1035 to transfer an annuity into life insurance

Internal Revenue Code 1035 rules

Equity indexed annuities

Equity indexed annuities are fixed annuities that guarantee against loss of principal if held to term. With an equity indexed annuity, interest credited is linked to the upward movement of a designated index, such as the Standard and Poor’s 500 (S&P 500).

  • If the index moves upward, the interest rate is based on some portion of the increase.
  • If the index moves downward, the equity indexed annuity does not lose value.

Market value adjusted annuities

Another fixed annuity product with a market-driven feature is the market value adjusted annuity. Unlike an equity indexed annuity (where interest is linked to an index), a market value adjusted annuity credits a fixed interest rate. The market value adjustment feature applies only if the contract is surrendered before the contract period expires.

If a market value adjusted annuity owner surrenders the contract early, both a surrender charge and a market value adjustment apply.

  • If interest rates decrease during the contract period, the adjustment is positive and may add to the contract’s surrender value.
  • If interest rates increase during the contract period, the adjustment is negative and may increase the contract’s surrender charge.
Sidenote
Know this...

Marketing material of market value adjusted annuities must plainly state that the adjustment may be positive or negative.

Lesson summary

IRS rules under Code 1035 allow portability of funds between life insurance and annuity contracts, deferring tax on certain transfers such as life-to-life, life-to-annuity, and annuity-to-annuity. Transfers from an annuity into life insurance are not permitted.

  • Equity indexed annuities offer principal protection and interest linked to an index’s upward movement without downside risk.
  • Market value adjusted annuities have fixed interest rates but include a market value adjustment feature upon early surrender, impacting surrender values based on interest rate fluctuations.

Available annuity payout options include life income, period certain, life annuity with period certain, refund, joint life, and joint and survivor, each offering different tradeoffs in payment amount, guarantees, and beneficiary protection. Joint life stops paying at the first annuitant’s death and pays more per month, while joint and survivor continues until the last annuitant dies and may reduce after the first death.

Chapter vocabulary

Definitions
Equity Indexed Annuity
A fixed annuity that earns interest or provides benefits that are linked to an external reference or equity index, subject to a minimum guarantee.
Fixed Annuity
An annuity that guarantees a specific rate of return. In the case of a deferred annuity, a minimum rate of interest is guaranteed during the savings phase. During the payment phase, a fixed amount of income, paid on a regular schedule, is guaranteed.
Index Annuity
Equity Indexed Annuity (also called Index Annuity): A fixed annuity that earns interest tied to an external equity index, such as the S&P 500, while protecting principal if held to term.
Joint-Life Annuity
Payout option covering two or more annuitants that stops paying at the first annuitant’s death.
Joint and Survivor Annuity
Payout option covering two or more annuitants that continues to pay until the last annuitant dies, sometimes at a reduced amount after the first death.
Market-Value Adjusted Annuity
An annuity whose accumulated value is subject to a market value adjustment on surrender. The market value adjustment may be positive or negative depending on the movement of interest rates since the inception of the contract.
1035 Exchange
A nontaxable exchange of life insurance policies or annuities, as provided under section 1035 of the Internal Revenue Code.

Annuity payout options

  • Life income (straight): highest payment, stops at death, most longevity risk to insurer
  • Period certain: pays for fixed period; beneficiary gets remainder if annuitant dies early; stops if annuitant outlives period
  • Life annuity with period certain: pays for life or specified period, whichever longer
  • Refund: lowest payments, most conservative; beneficiary gets remaining contract value (lump sum or installments)
  • Joint life: covers 2+ people, stops at first death, higher monthly payment
  • Joint and survivor: pays until last annuitant dies, may reduce after first death

Taxation of annuity payments

  • No 10% early withdrawal penalty once annuitized (treated as scheduled income stream)
  • Only the growth portion of each payment is taxable
  • Fixed annuity payments stay level; variable annuity payments fluctuate with investment performance

1035 exchange

  • IRC Section 1035 allows tax-deferred transfers between contracts
  • Permitted: life insurance → life insurance; life insurance → annuity; annuity → annuity
  • Not permitted: annuity → life insurance

Equity indexed annuities

  • Fixed annuity type; guarantees no loss of principal if held to term
  • Interest credited linked to upward movement of an index (e.g., S&P 500)
  • Only a portion of index gains credited; no loss if index falls

Market value adjusted annuities

  • Fixed annuity with a set interest rate (not index-linked)
  • Market value adjustment (MVA) applies only on early surrender
  • Interest rates fall → positive adjustment (higher surrender value)
  • Interest rates rise → negative adjustment (larger surrender charge)
  • Marketing materials must disclose adjustment can be positive or negative

Lesson summary

  • 1035 exchanges enable tax-deferred portability between life/annuity contracts (except annuity→life insurance)
  • Equity indexed annuities: principal protection + index-linked upside, no downside
  • Market value adjusted annuities: fixed rate + MVA feature affecting early surrender value
  • Payout options vary in payment size, guarantees, and beneficiary protections; joint life vs. joint and survivor differ in duration and payment amount

Chapter vocabulary

  • Equity Indexed Annuity/Index Annuity: fixed annuity with interest linked to external index, minimum guarantee
  • Fixed Annuity: guarantees rate of return/fixed income payments
  • Joint-Life Annuity: stops at first annuitant’s death
  • Joint and Survivor Annuity: pays until last annuitant’s death, possibly reduced after first death
  • Market-Value Adjusted Annuity: surrender value subject to positive/negative adjustment based on interest rate changes
  • 1035 Exchange: nontaxable exchange of life insurance/annuity contracts under IRC Section 1035

Sign up for free to take 16 quiz questions on this topic

Previous
Next  | 11. Taxation of Life Insurance Products
All rights reserved ©2016 - 2026 Achievable, Inc.

Payouts and Advanced Options

The available annuity payout options are as follows:

  • Life income (straight): This option typically provides the highest monthly payment, but it also carries the most longevity risk for the insurer. Payments are guaranteed for the annuitant’s lifetime and stop at the annuitant’s death.

  • Period certain (fixed period annuity): This option provides payments for a fixed period (for example, 10 or 20 years). If the annuitant dies during that period, a beneficiary receives the remaining payments. If the annuitant lives beyond the period, payments stop when the period ends.

  • Life annuity with period certain: Payments are guaranteed for the annuitant’s lifetime or for a specified period (for example, 10 or 20 years), whichever is longer. If the annuitant dies during the guaranteed period, the beneficiary receives the remaining payments. If the annuitant lives beyond the period, payments continue for life.

  • Refund: This is the most conservative option and typically has the lowest payments. If the annuitant dies before receiving payments equal to the contract’s value at annuitization, the beneficiary receives the remaining balance. Refunds may be paid either in a lump sum (cash refund) or in continued installments (installment refund).

  • Joint life: Covers two or more annuitants, but payments stop at the first annuitant’s death. Because payments end sooner, it pays more per month than joint and survivor.

  • Joint and survivor (joint and last survivor): This payout option covers two or more people, commonly spouses. The contract pays monthly as long as at least one annuitant is living. Depending on the contract, the payment may stay level or be reduced after the first annuitant’s death.

Available annuity payout options

Taxation of annuity payments differs from withdrawals during the accumulation stage. Once a contract has been annuitized, the 10% early withdrawal penalty no longer applies because payments are treated as a scheduled annuity stream, not as withdrawals.

For income taxes, only the portion of each payment that represents growth is taxable. Fixed annuity payments stay the same each month, while variable annuity payments may change based on investment performance.

The IRS provides portability for certain life insurance and annuity contracts. Internal Revenue Code 1035 allows the transfer of funds from one product to another, or from one company to another. Under 1035 exchange rules, tax on accumulated earnings is deferred for the following transfers:

  • Life insurance policy into another life insurance policy
  • Life insurance policy into an annuity
  • Annuity into another annuity
Sidenote
Know this...

It is not possible under rule 1035 to transfer an annuity into life insurance

Internal Revenue Code 1035 rules

Equity indexed annuities

Equity indexed annuities are fixed annuities that guarantee against loss of principal if held to term. With an equity indexed annuity, interest credited is linked to the upward movement of a designated index, such as the Standard and Poor’s 500 (S&P 500).

  • If the index moves upward, the interest rate is based on some portion of the increase.
  • If the index moves downward, the equity indexed annuity does not lose value.

Market value adjusted annuities

Another fixed annuity product with a market-driven feature is the market value adjusted annuity. Unlike an equity indexed annuity (where interest is linked to an index), a market value adjusted annuity credits a fixed interest rate. The market value adjustment feature applies only if the contract is surrendered before the contract period expires.

If a market value adjusted annuity owner surrenders the contract early, both a surrender charge and a market value adjustment apply.

  • If interest rates decrease during the contract period, the adjustment is positive and may add to the contract’s surrender value.
  • If interest rates increase during the contract period, the adjustment is negative and may increase the contract’s surrender charge.
Sidenote
Know this...

Marketing material of market value adjusted annuities must plainly state that the adjustment may be positive or negative.

Lesson summary

IRS rules under Code 1035 allow portability of funds between life insurance and annuity contracts, deferring tax on certain transfers such as life-to-life, life-to-annuity, and annuity-to-annuity. Transfers from an annuity into life insurance are not permitted.

  • Equity indexed annuities offer principal protection and interest linked to an index’s upward movement without downside risk.
  • Market value adjusted annuities have fixed interest rates but include a market value adjustment feature upon early surrender, impacting surrender values based on interest rate fluctuations.

Available annuity payout options include life income, period certain, life annuity with period certain, refund, joint life, and joint and survivor, each offering different tradeoffs in payment amount, guarantees, and beneficiary protection. Joint life stops paying at the first annuitant’s death and pays more per month, while joint and survivor continues until the last annuitant dies and may reduce after the first death.

Chapter vocabulary

Definitions
Equity Indexed Annuity
A fixed annuity that earns interest or provides benefits that are linked to an external reference or equity index, subject to a minimum guarantee.
Fixed Annuity
An annuity that guarantees a specific rate of return. In the case of a deferred annuity, a minimum rate of interest is guaranteed during the savings phase. During the payment phase, a fixed amount of income, paid on a regular schedule, is guaranteed.
Index Annuity
Equity Indexed Annuity (also called Index Annuity): A fixed annuity that earns interest tied to an external equity index, such as the S&P 500, while protecting principal if held to term.
Joint-Life Annuity
Payout option covering two or more annuitants that stops paying at the first annuitant’s death.
Joint and Survivor Annuity
Payout option covering two or more annuitants that continues to pay until the last annuitant dies, sometimes at a reduced amount after the first death.
Market-Value Adjusted Annuity
An annuity whose accumulated value is subject to a market value adjustment on surrender. The market value adjustment may be positive or negative depending on the movement of interest rates since the inception of the contract.
1035 Exchange
A nontaxable exchange of life insurance policies or annuities, as provided under section 1035 of the Internal Revenue Code.
Key points

Annuity payout options

  • Life income (straight): highest payment, stops at death, most longevity risk to insurer
  • Period certain: pays for fixed period; beneficiary gets remainder if annuitant dies early; stops if annuitant outlives period
  • Life annuity with period certain: pays for life or specified period, whichever longer
  • Refund: lowest payments, most conservative; beneficiary gets remaining contract value (lump sum or installments)
  • Joint life: covers 2+ people, stops at first death, higher monthly payment
  • Joint and survivor: pays until last annuitant dies, may reduce after first death

Taxation of annuity payments

  • No 10% early withdrawal penalty once annuitized (treated as scheduled income stream)
  • Only the growth portion of each payment is taxable
  • Fixed annuity payments stay level; variable annuity payments fluctuate with investment performance

1035 exchange

  • IRC Section 1035 allows tax-deferred transfers between contracts
  • Permitted: life insurance → life insurance; life insurance → annuity; annuity → annuity
  • Not permitted: annuity → life insurance

Equity indexed annuities

  • Fixed annuity type; guarantees no loss of principal if held to term
  • Interest credited linked to upward movement of an index (e.g., S&P 500)
  • Only a portion of index gains credited; no loss if index falls

Market value adjusted annuities

  • Fixed annuity with a set interest rate (not index-linked)
  • Market value adjustment (MVA) applies only on early surrender
  • Interest rates fall → positive adjustment (higher surrender value)
  • Interest rates rise → negative adjustment (larger surrender charge)
  • Marketing materials must disclose adjustment can be positive or negative

Lesson summary

  • 1035 exchanges enable tax-deferred portability between life/annuity contracts (except annuity→life insurance)
  • Equity indexed annuities: principal protection + index-linked upside, no downside
  • Market value adjusted annuities: fixed rate + MVA feature affecting early surrender value
  • Payout options vary in payment size, guarantees, and beneficiary protections; joint life vs. joint and survivor differ in duration and payment amount

Chapter vocabulary

  • Equity Indexed Annuity/Index Annuity: fixed annuity with interest linked to external index, minimum guarantee
  • Fixed Annuity: guarantees rate of return/fixed income payments
  • Joint-Life Annuity: stops at first annuitant’s death
  • Joint and Survivor Annuity: pays until last annuitant’s death, possibly reduced after first death
  • Market-Value Adjusted Annuity: surrender value subject to positive/negative adjustment based on interest rate changes
  • 1035 Exchange: nontaxable exchange of life insurance/annuity contracts under IRC Section 1035

More from Annuities

  • Annuity Basics and Accumulation