



Optional Policy Provisions
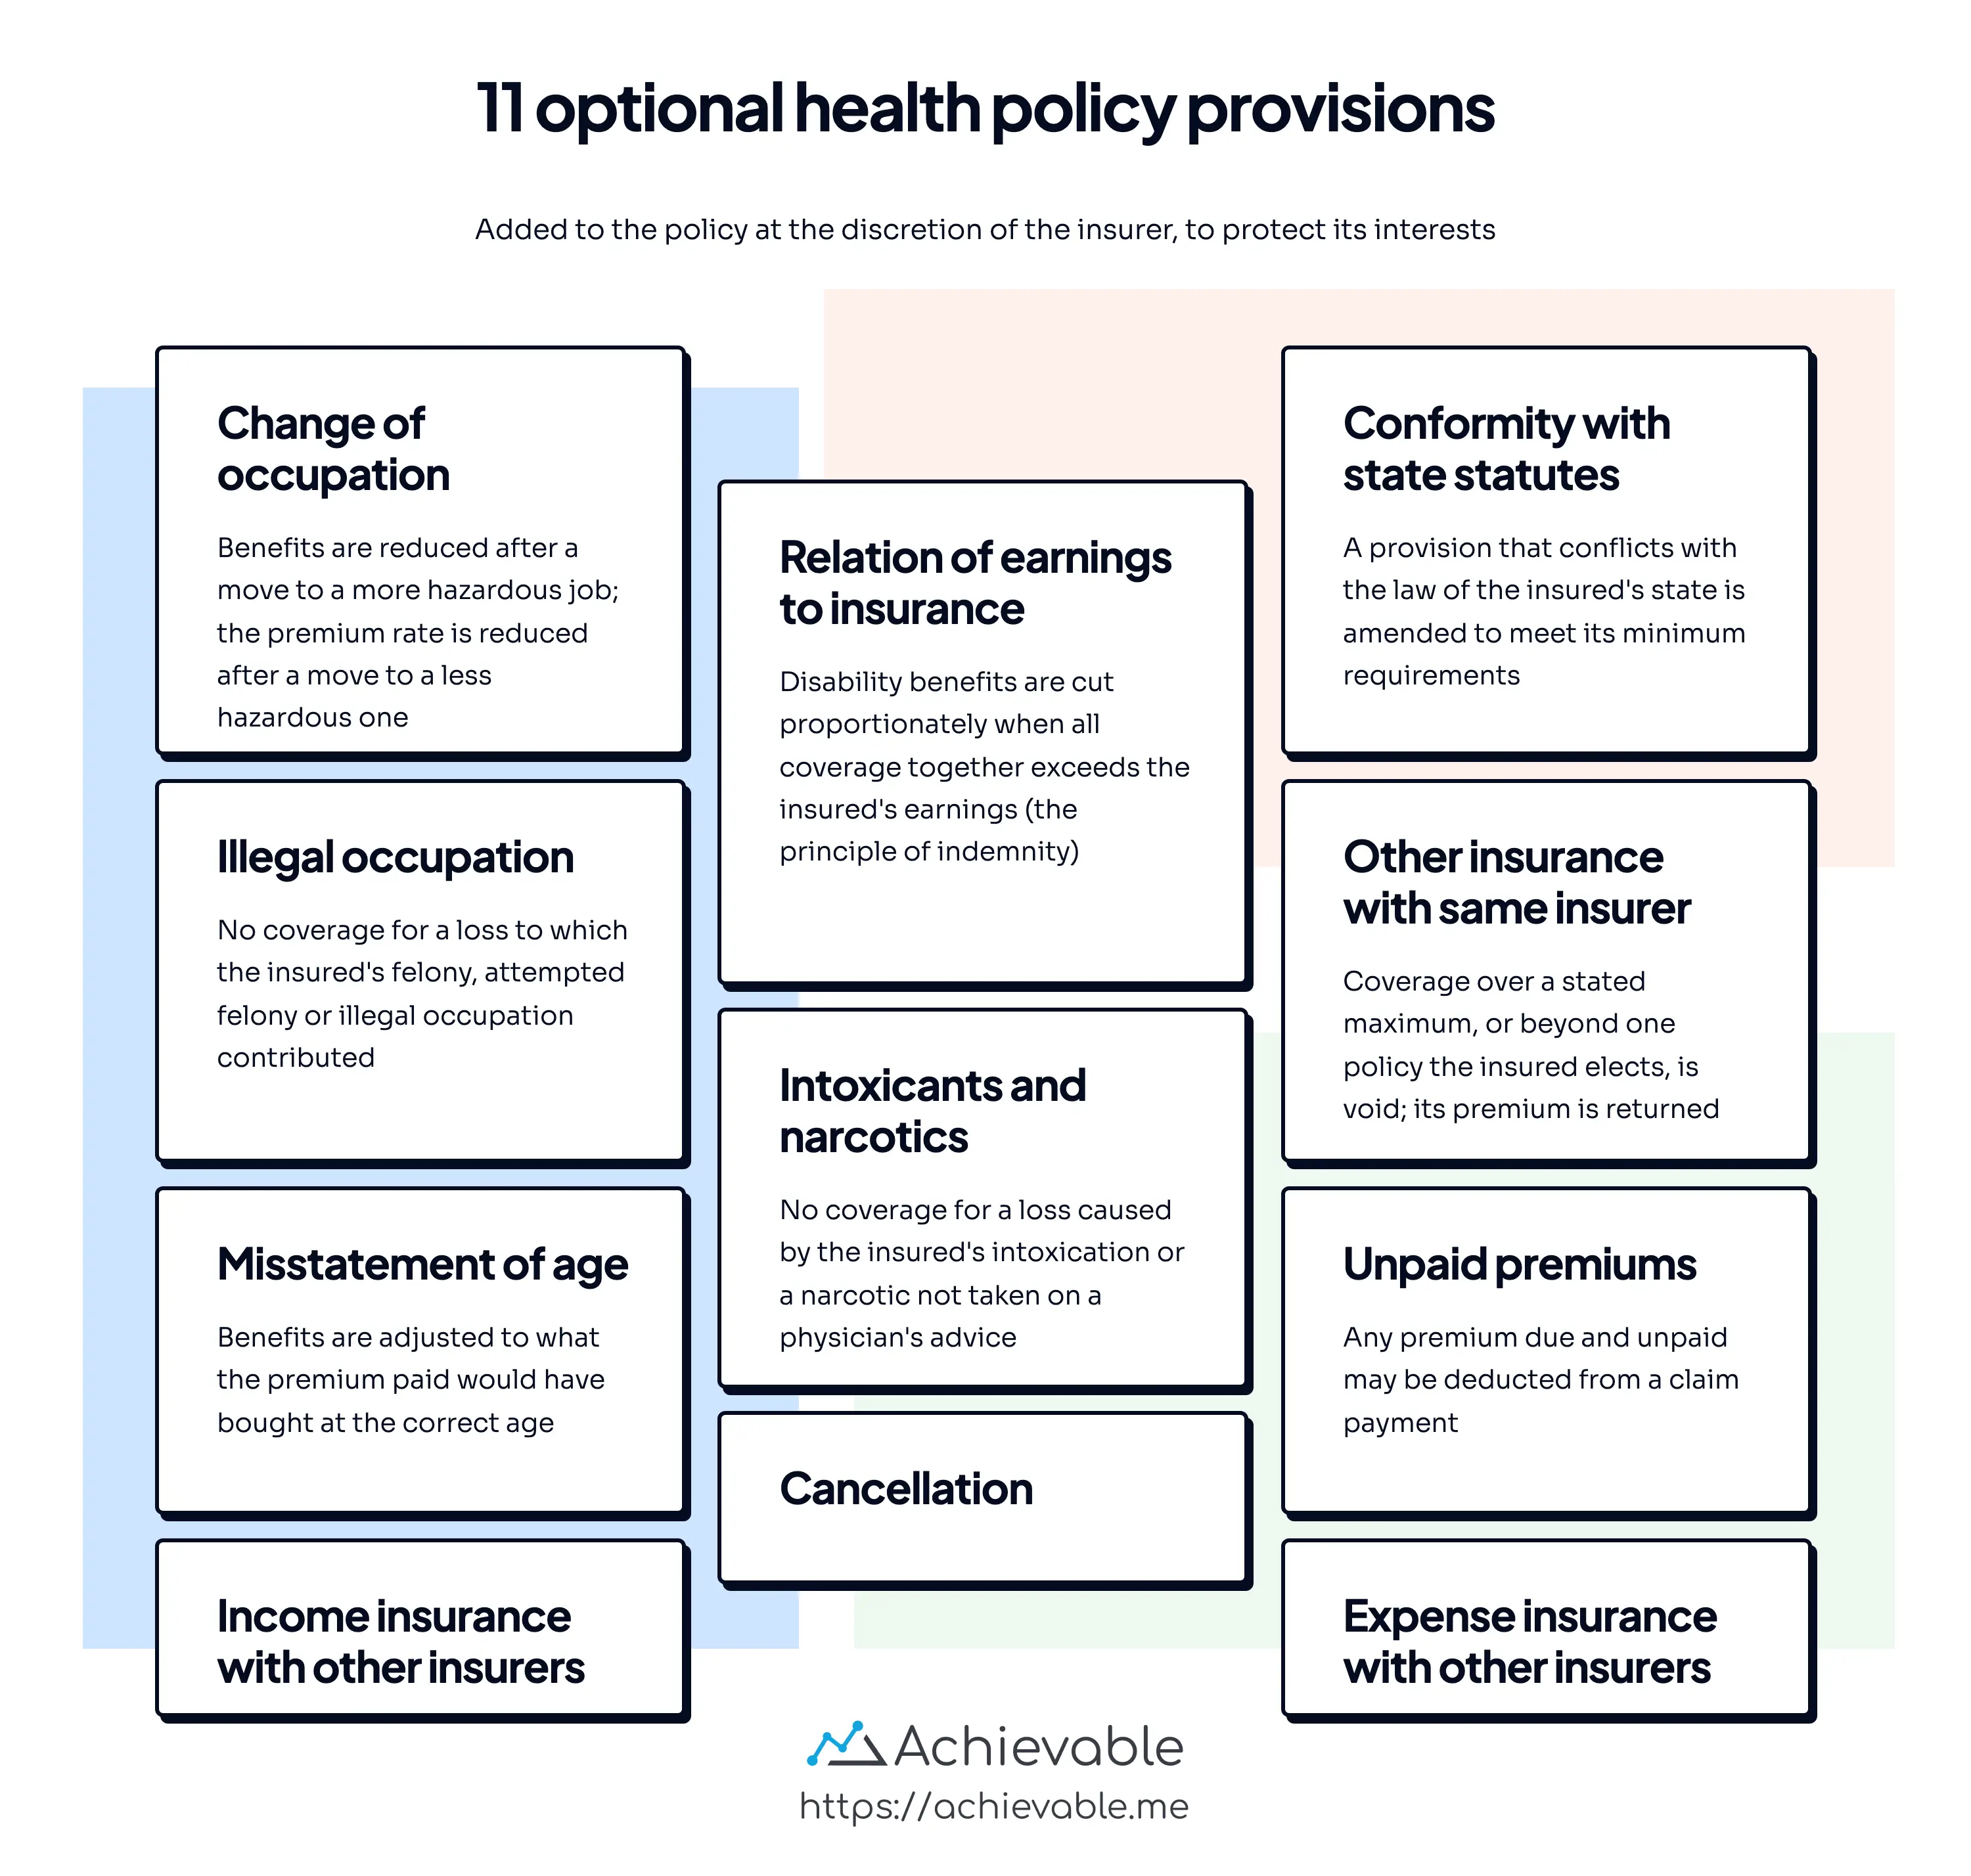
Optional provisions are policy provisions the insurer may choose to include or leave out. The 11 optional policy provisions are as follows:
Change of occupation
- If the insured changes to a more hazardous job, benefits may be reduced: on a claim, the insurer pays only the benefits that the premium paid would have purchased at its rate for the more hazardous job. If the insured changes to a less hazardous job, premiums may be reduced: once it receives proof of the change, the insurer lowers the premium rate and returns the excess unearned premium.
Misstatement of age
- Benefits will be adjusted to reflect what the premiums would have purchased if the insured’s correct age had been stated on the application.
Other insurance with the same insurer
- If the insured has more than one policy of the same kind with the same insurer, coverage is limited either to a maximum amount the policy states, with any insurance over it void, or to the one policy the insured (or the beneficiary or estate) chooses. The insurer returns the premiums paid for the excess coverage or for the other policies.
Expense insurance with other insurers
- Applies when the insured has expense-type policies (such as hospital or surgical coverage) with more than one company. An insurer that was not given written notice of the other coverage before the loss pays only its proportionate share of the loss, and returns the premium paid for the excess. Some states provide instead for an overinsurance (or coordination of benefits) provision, which reduces the insurer’s payment so that benefits from all valid coverage do not exceed the insured’s allowable expenses.
Income insurance with other insurers
- Applies when the insured has coverage that pays a fixed benefit, such as disability income, with more than one company. An insurer that was not given written notice of the other coverage before the loss pays only its proportionate share of the benefits, and returns the premium paid for the excess.
Relation of earnings to insurance
- Ensures disability income benefits do not exceed the insured’s actual earned income, reinforcing the principle of indemnity.
Unpaid premiums
- Allows the insurer to deduct any premium due but unpaid from the amount of a claim. This often applies if a claim occurs during the grace period.
Cancellation
- Allows the insurer to cancel the policy with proper notice and requires any unearned premium to be refunded to the policyowner.
Conformity with state statutes
- Any policy provision that conflicts with state law is automatically amended to conform with the statutes of the state where the insured resides.
Illegal occupation
- No coverage is provided if a claim arises from the insured committing a felony or engaging in an illegal occupation.
Intoxicants and narcotics
- The insurer is not liable for a loss that results from the insured’s being intoxicated or under the influence of a narcotic, unless the narcotic was taken on a physician’s advice. The provision applies when the intoxication or the narcotic caused the loss, not merely because the insured was intoxicated when a loss occurred.
Other general provisions
Free look (right to examine)
- Under this provision, the insured may return the policy to the agent or the insurer within 10 days of delivery (30 days for LTC and Medigap policies) and receive a full refund of premiums paid.
Insuring clause
- This provision is customarily found on the first page of the policy. It defines the benefits and policy periods and states the insurer’s promise to pay benefits if coverage is provided by the policy and all conditions are satisfied.
Consideration clause
- This provision states the amount and frequency of premium payments and the representations made by the applicant. It also describes the insurer’s obligation to pay the benefits.
Assignment of benefits provision
- This provision defines the benefit amounts to be paid in the event of a covered loss. In many cases, the beneficiary of a health reimbursement policy prefers that the insurer pay the doctor or hospital directly. If either will accept assignment of benefits, the insurer will pay them directly in the name of the insured.
Waiver of premium
- Disability income policies usually include this option, which exempts the insured from paying premiums if totally and permanently disabled. Other types of policies may also make this option available, for an additional premium.
Lesson summary
In an insurance policy, optional provisions can be included or excluded at the discretion of the insurer.
Optional policy provisions:
- Change of occupation: Benefits or premiums may be adjusted if the insured changes to a job with a different risk level.
- Misstatement of age: Benefits are adjusted to what the correct age and premium would have purchased.
- Other insurance with the same insurer: Prevents double recovery if the insured has more than one policy with the same company.
- Expense insurance with other insurers: An insurer not told of other medical expense coverage pays only its proportionate share.
- Income insurance with other insurers: An insurer not told of other fixed-benefit coverage, such as disability income, pays only its proportionate share.
- Relation of earnings to insurance: Disability benefits cannot exceed the insured’s actual earned income.
- Unpaid premiums: Any unpaid premium may be deducted from a claim payment.
- Cancellation: Insurer may cancel with proper notice and must refund any unearned premium.
- Conformity with state statutes: Policy automatically amends to meet state insurance laws.
- Illegal occupation: No coverage for a loss to which the insured’s committing or attempting to commit a felony, or engaging in an illegal occupation, was a contributing cause.
- Intoxicants and narcotics: No coverage for a loss caused by the insured’s being intoxicated or under the influence of a narcotic not taken on a physician’s advice.