This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
Life & Health
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
1. General Insurance Concepts
2. Producer Roles and Receipt Types
3. Principles of Life Insurance
4. Underwriting
5. Term Life Insurance
6. Whole Life Insurance
7. Variable Insurance Products
8. Group Life Insurance
9. Life Insurance Provisions
10. Annuities
11. Taxation of Life Insurance Products
12. Qualified Retirement Plans
13. Health Insurance Basics
14. Required Policy Provisions
15. Optional Policy Provisions
16. Medical Expense Insurance
17. Group Health Insurance
17.1 Group Insurance Essentials
17.2 Group Health Underwriting
18. The Affordable Care Act (ACA)
19. Disability Income Insurance
20. Accidental Death and Dismemberment Insurance
21. Long Term Care Insurance
22. Dental Insurance
23. Section 125 Plans and Limited Policies
24. Federal Government Programs
25. Medigap and Medicaid
26. Health Insurance Taxation
Wrapping Up
Achievable logoAchievable logo
17.2 Group Health Underwriting
Achievable Life & Health
18. Group Health Insurance

Group Health Underwriting

14 min read
Font
Discuss
Share
Feedback

Some of the rules in this chapter, such as pre-existing condition limitations and COBRA continuation, have been changed or modified by the Affordable Care Act (ACA). However, for exam purposes, these provisions are still tested in their original form. A separate chapter covers ACA-specific updates in detail. This chapter focuses on traditional group health underwriting topics that remain common on exams.

Group underwriting

Group health underwriting evaluates the risk of the group as a whole, not each individual. Underwriters typically don’t require physical exams or individual applications. Instead, they review group-level information such as:

  • Size of the group
  • Average age
  • Type of work performed
  • Claims history

Because working populations are generally healthier than the overall population, group plans usually present lower morbidity risk. If the group qualifies, the insurer accepts or rejects the entire group (not individual members).

On each anniversary date, group underwriters review the previous year’s claims experience. This information is used, to some extent, to help determine the next year’s premium.

The variables used to calculate a group health premium are fundamentally the same as those used for an individual health policy. However, health premium calculations are generally more complex than life insurance premium calculations. Key variables include:

  • Interest
  • Expenses
  • Morbidity
  • Claims experience
  • Policy benefits

Similar to mortality tables (which show how many people are expected to die at a given age), morbidity tables show how many people, out of a large group, are expected to become ill or disabled at a given age.

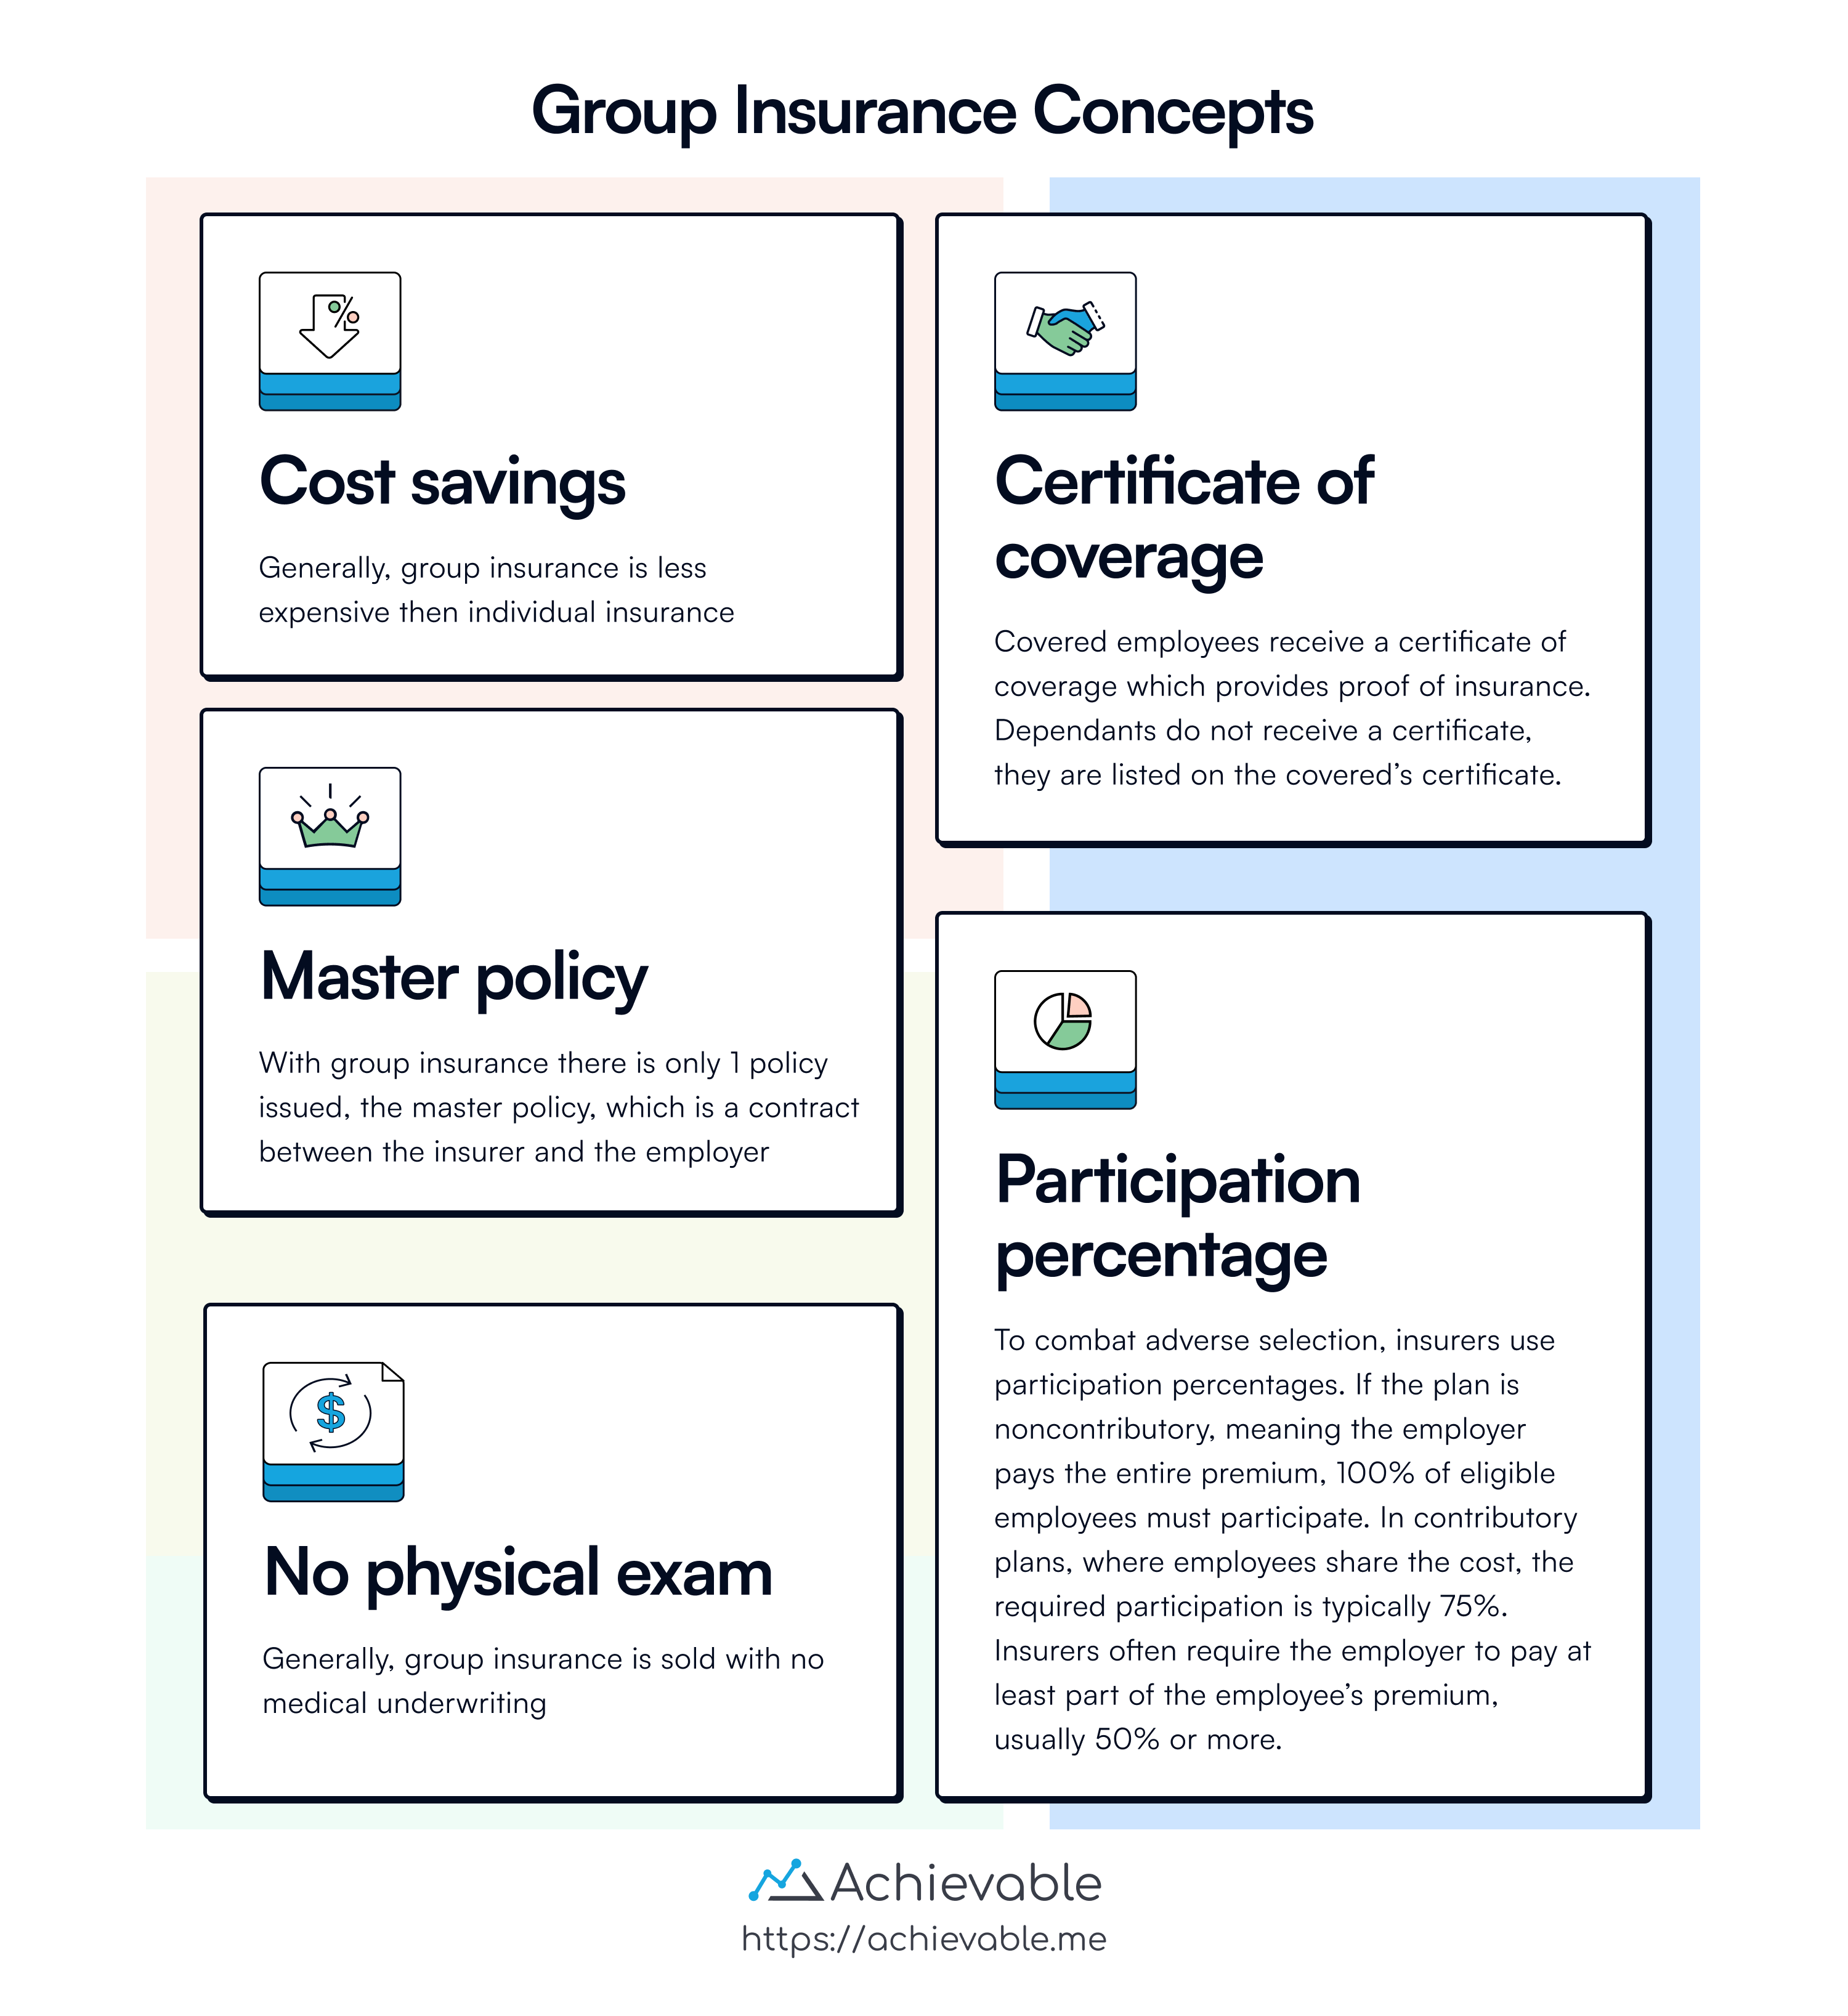
Insurers also impose requirements on group plans to reduce adverse selection and keep administrative costs low. One common requirement is participation percentage:

  • Noncontributory plans (employer pays the full premium) typically require 100% of eligible employees to enroll.
  • Contributory plans (employer and employees share the cost) typically require at least 75% participation.

Insurers often require the employer to pay part of the employee’s premium - commonly 50% or more - for the plan to qualify as contributory.

Employers are free to switch insurance carriers for their group coverage or terminate coverage altogether. Statutory rules regulate the terms and conditions that must be followed when this occurs.

The employees must be notified that the policy is being discontinued.

If a group health plan is discontinued, the plan must provide a reasonable extension of benefits for anyone who is totally disabled on the date it ends. Under the NAIC’s Group Coverage Discontinuance and Replacement Model Regulation, the extension must last at least 12 months under major medical coverage. Under other hospital or medical expense coverage, the plan must provide either an extension of at least 90 days or an accrued-liability provision. Benefits during the extension may be limited to the disabling condition and remain subject to the plan’s usual benefit limits.

When one insurer replaces another:

  • The prior insurer remains liable only to the extent of its accrued liabilities and extensions of benefits.
  • The new insurer must cover all employees who were eligible to participate under the prior insurer.
  • The new insurer must disregard any pre-existing conditions that would otherwise make a participant uninsurable.
Group insurance concepts

Health insurance portability and accountability act (HIPAA)

Under HIPAA, any insurer in the business of writing group health insurance must make the product available to small employer groups (2 to 50 employees) without regard to health status.

HIPAA limits how pre-existing conditions can be handled:

  • The look-back period for pre-existing conditions is limited to 6 months.
  • The maximum probationary period is 12 months (pre-existing conditions will be covered 12 months after enrollment).
  • Each month of prior creditable coverage reduces the probationary period, but coverage before a break of 63 days or more does not count. So if an individual enters a group plan fewer than 63 days after leaving another group plan that covered them for at least 12 months, the new insurer cannot assign a probationary period for pre-existing conditions.

Pregnancy is not a pre-existing condition, and newborn children must be covered from the moment of birth. Under a separate federal law, the Newborns’ and Mothers’ Health Protection Act, a group health plan that covers childbirth may not limit the hospital stay to less than the following, unless the attending provider, in consultation with the mother, decides on an earlier discharge:

  • A 48-hour hospital stay after a vaginal delivery
  • A 96-hour hospital stay after a caesarean birth

The newborn may be enrolled within 30 days without any pre-existing condition limitations.

Sidenote
Know this...

While this is not part of HIPAA, it fits nicely here…and is on the test!

  1. Under federal law, a group health plan that covers dependent children must cover a child placed with an employee for adoption on the same terms as a natural child, even before the adoption is final.
  2. Under the ACA, a dependent child may generally remain covered under a parent’s health plan until age 26, regardless of student status, marital status, residency, or financial dependence.
  3. A mentally or physically handicapped child (any age) can be covered as a dependent on his/her parents policy until he/she becomes self supporting.

A group health policy may include a conversion privilege, and some states’ laws require one. This allows members of the group to convert their coverage to an individual health insurance policy for 31 days after leaving a group plan due to a qualifying event.

The key value of this provision is that evidence of insurability is not required. This can be especially important for someone who has health problems or pre-existing conditions at the time of the qualifying event.

Which events give the right to convert depends on the policy and the state’s law. Wyoming’s law is one example. A member who has been insured under the group for at least 3 months may convert when the member’s group coverage ends for any reason, unless it ended because the member did not pay a required contribution, or the discontinued group coverage was replaced by similar group coverage within 31 days. The privilege also extends to:

  • The surviving spouse and children, when the member dies
  • A spouse who stops being an eligible family member, as on divorce, and the children whose coverage ends at the same time
  • A child who stops being an eligible dependent

Under HIPAA, employers must make full health care coverage available immediately (upon eligibility) to newly hired employees who were previously covered by a group policy for at least 12 months, with no break in coverage greater than 63 days. Coverage must be made available with no probationary, look back, or waiting periods.

Consolidated omnibus budget reconciliation act (COBRA)

COBRA is a federal law that requires, upon the occurrence of a qualifying event, employers with 20 or more employees to provide continuation of benefits under the employer’s group insurance plan for former employees and their dependents (at 102% of the required premium). COBRA provides transitional health care coverage until the employee and dependents can obtain coverage elsewhere.

Generally, the maximum period of coverage continuation is 18 months. However, if the qualifying event was the employee’s death, divorce or legal separation, or entitlement to Medicare, or a dependent child losing dependent status (for example, by attaining age 26), the maximum period of coverage continuation is 36 months. Disability is not a qualifying event, but a qualified beneficiary whom Social Security finds to have been disabled at any time during the first 60 days of continuation coverage can extend the 18 months to 29 months.

Upon the occurrence of a qualifying event, the employee or dependent has 60 days to notify the group insurer or plan administrator of their election to stay in the group plan through COBRA.

In effect, former employees may use the 60 days as a period of “free coverage,” by electing COBRA and paying the premium only if a claim arises. If the employee takes a new job (and enrolls in a new group plan), their new group coverage will most likely take effect before the transitional period allowed under COBRA expires. However, if COBRA is elected, the premium must be paid within 45 days.

HIPAA requires that every insurer who offers individual health insurance must offer at least two plans on a guaranteed issue basis to any individual who has elected and exhausted COBRA and is not eligible for coverage under any other group plan, Medicare, or Medicaid.
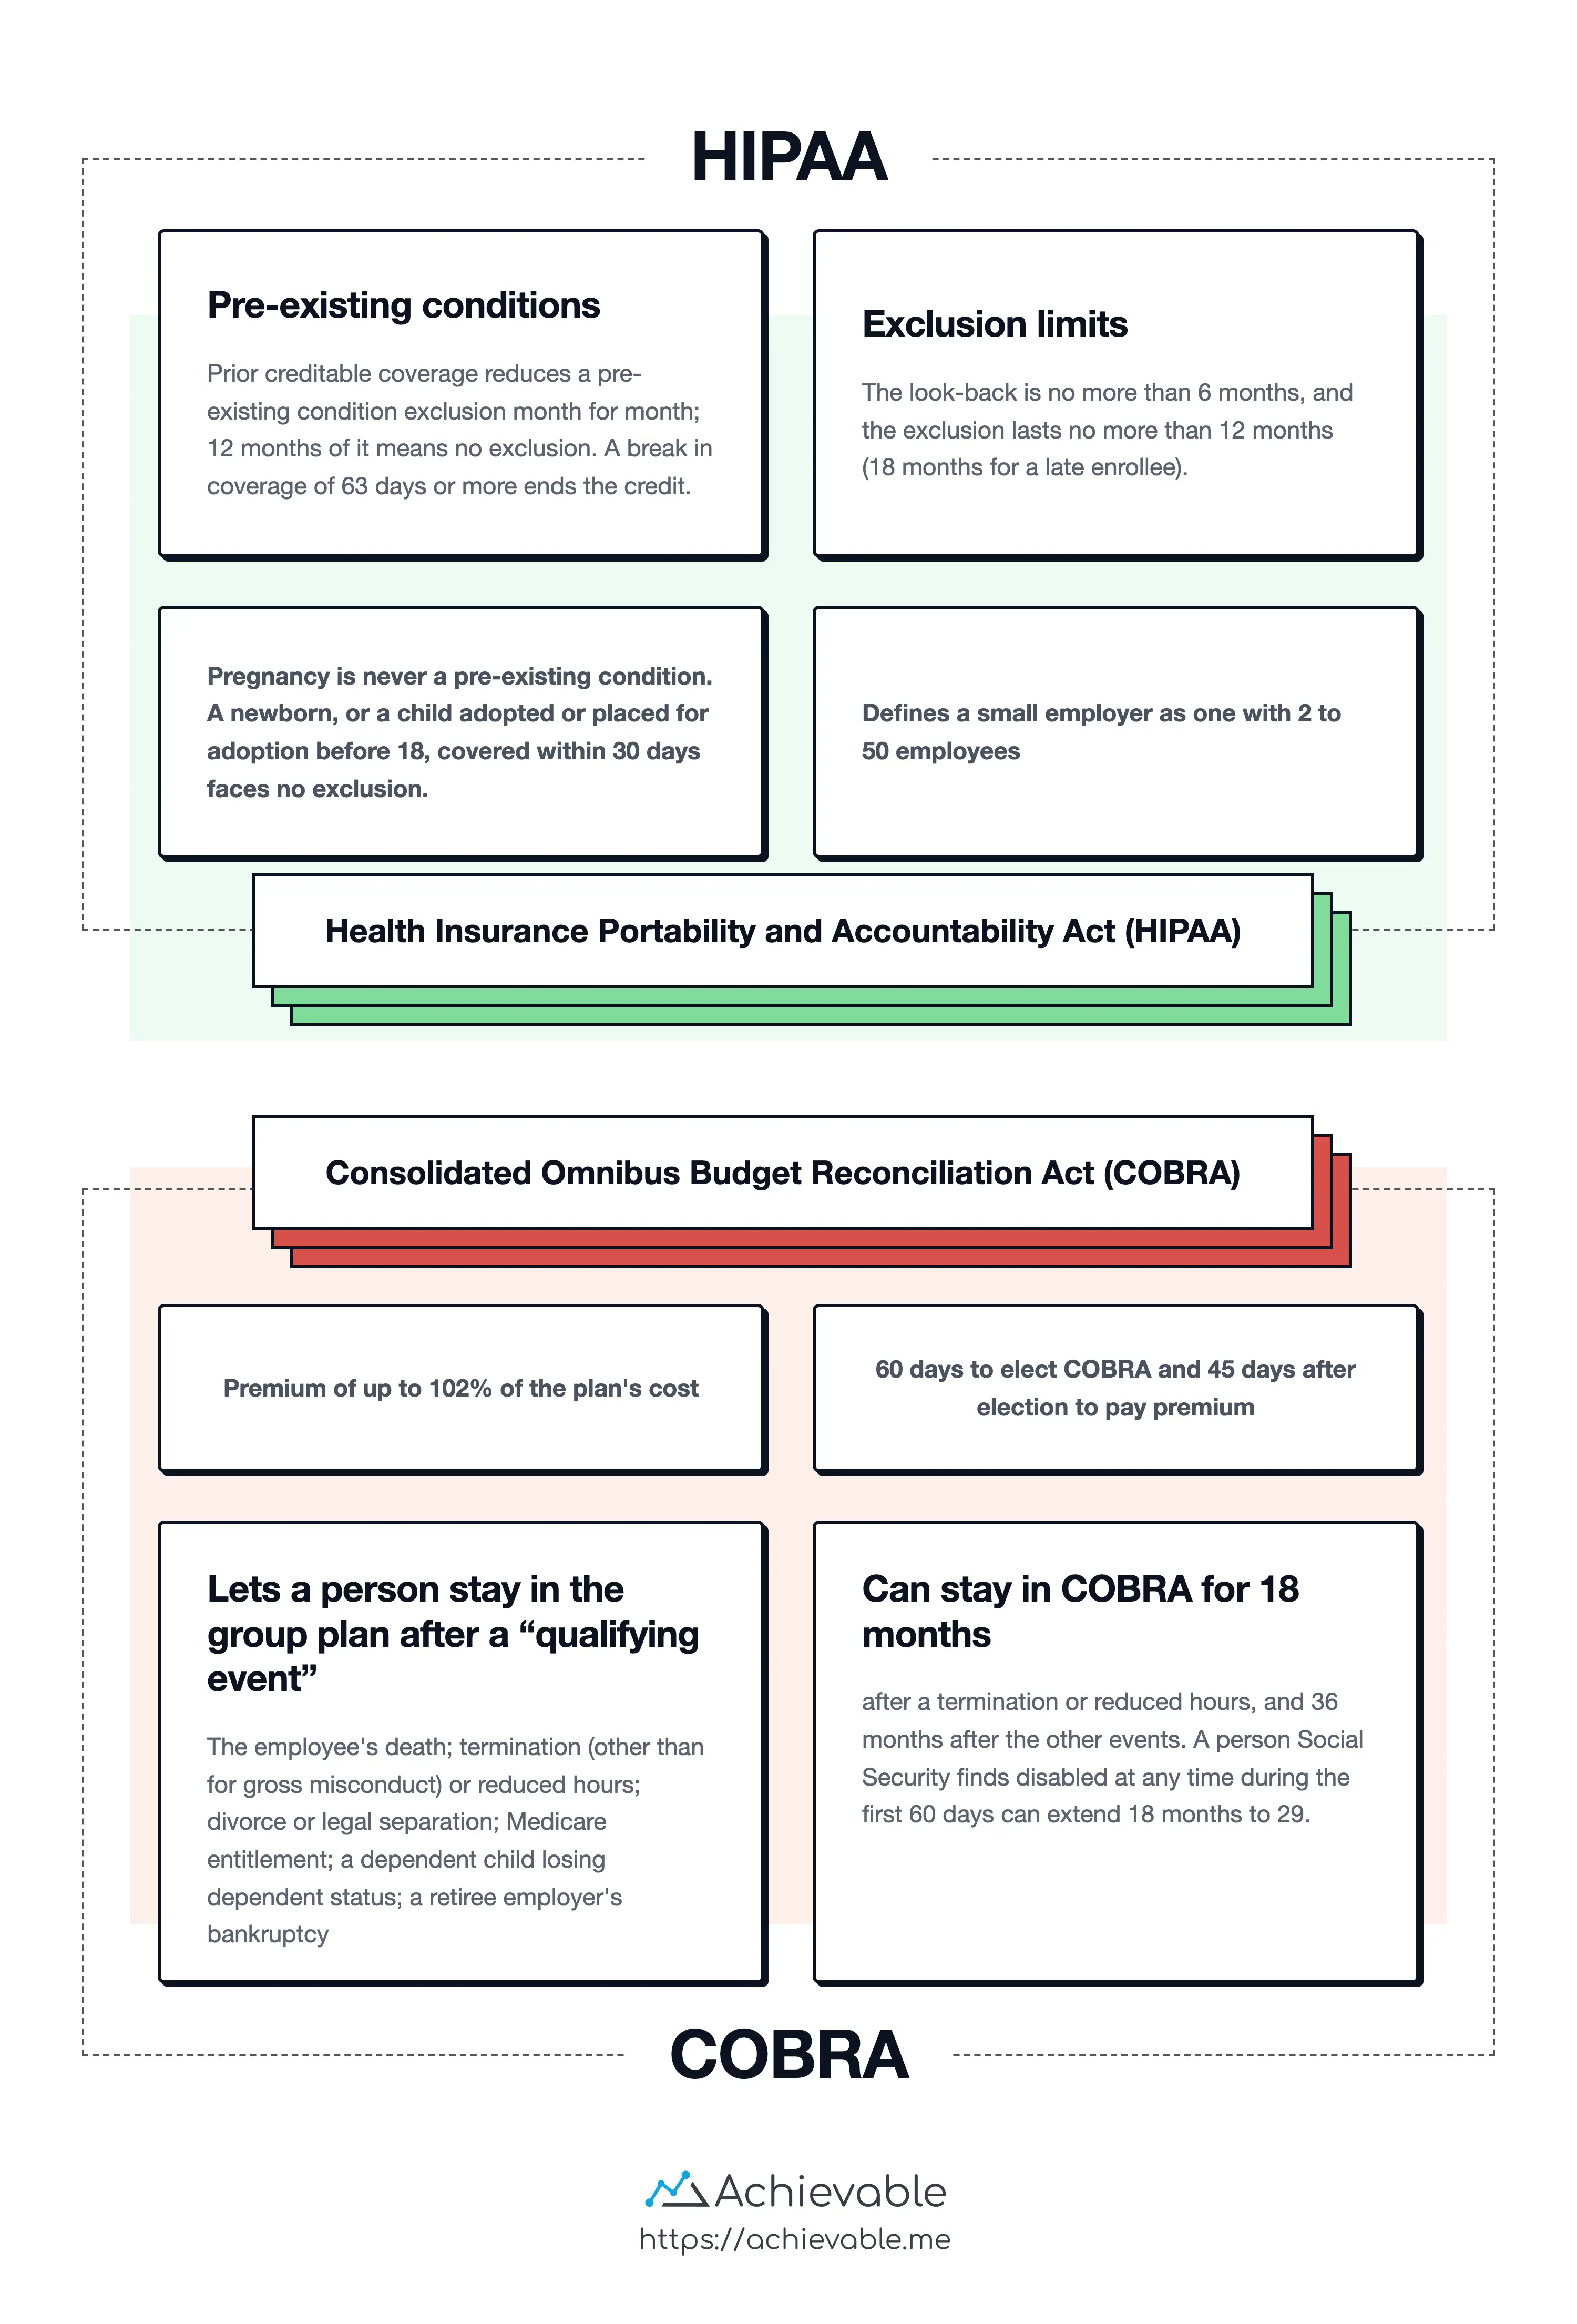
COBRA and HIPAA

Other means of covering groups

Blanket disability insurance provides definite, ascertainable benefits to a changing, nameless group of people (the class). Anyone who enters the covered class is automatically covered. When they leave the class, coverage ends.

For example, a scout camp could purchase a blanket disability policy that pays a flat dollar amount (maybe $5,000) to anyone who sustains an injury requiring medical care while attending the camp.

Franchise insurance is similar to the concept of METs (Multiple Employer Trusts), but with franchise insurance, each eligible participant is issued an individual policy. Premium levels are reduced somewhat from those of regular individual policies because of savings in underwriting expenses and plan administration costs.

Another form of group coverage similar to the MET is the Multiple Employer Welfare Association (MEWA), which is an alternative to true group insurance. MEWAs provide self-funded health care benefits to employees of several large employers. In recent years, the growth of MEWAs has slowed due to increased requirements governing legal reserves.

Lesson summary

  • Group underwriting does not assess individuals but considers group data like size and claims history.
  • Group premiums are determined by factors such as morbidity, claims experience, and policy benefits.
  • Requirements like participation percentages reduce adverse selection in group plans.

Under the Health Insurance Portability and Accountability Act (HIPAA), insurers must offer group health insurance to small employers without regard to health status. HIPAA also limits pre-existing condition exclusions and bars treating pregnancy as a pre-existing condition.

  • Qualifying events like termination or death enable conversion to an individual policy without requiring evidence of insurability.
  • The Consolidated Omnibus Budget Reconciliation Act (COBRA) demands that employers provide continuation of benefits after qualifying events.

Alternative group coverage includes blanket disability insurance and franchise insurance, catering to nameless groups with specific benefits. Multiple Employer Welfare Associations (MEWA) offer self-funded benefits to employees of large companies.

Chapter vocabulary

Definitions
Conversion privilege
The right granted the insured to change his/her coverage from a group policy to individual policy. If a member of a group has a qualifying event he/she is given an opportunity to secure an individual policy within a specified period thereafter, regardless of whether or not he/she is in good health at that time.
Noncontributory
A general term used to designate any plan of insurance (usually group) for which the employer pays the entire premium and the employee contributes no part of the premium.

Introduction / ACA note

  • Chapter covers traditional pre-ACA rules (pre-existing conditions, COBRA) still tested in original form
  • ACA-specific updates covered in separate chapter

Group underwriting

  • Evaluates risk of entire group, not individuals; no physical exams/individual apps
  • Reviewed factors: group size, average age, type of work, claims history
  • Insurer accepts/rejects whole group; reviews claims experience at each anniversary
  • Premium variables: interest, expenses, morbidity, claims experience, policy benefits
  • Morbidity tables predict illness/disability rates by age (like mortality tables for death)

Participation requirements

  • Noncontributory plans (employer pays 100% premium): require 100% employee enrollment
  • Contributory plans (employer & employee share cost): require ≥75% participation
  • Employer typically pays 50%+ of premium to qualify as contributory

Plan termination/replacement rules

  • Employees must be notified of discontinuation
  • Totally disabled at discontinuance: reasonable extension of benefits (NAIC model: at least 12 months under major medical; under other medical coverage, 90 days or an accrued-liability provision)
  • New insurer must cover all previously eligible employees, disregarding pre-existing conditions
  • Prior insurer remains liable only for its accrued liabilities and extensions of benefits (NAIC model)

HIPAA (Health Insurance Portability and Accountability Act)

  • Requires insurers to offer group coverage to small employers (2–50 employees) regardless of health status
  • Pre-existing condition rules:
    • Look-back period: max 6 months
    • Probationary period: max 12 months
    • Prior creditable coverage reduces the probationary period; none after 12+ months of prior coverage with a break under 63 days
  • Pregnancy not pre-existing; newborns covered from birth
    • Childbirth stay (Newborns’ and Mothers’ Health Protection Act, not HIPAA): 48 hrs (vaginal), 96 hrs (C-section)
    • Newborn enrollment: 30 days, no pre-existing limitations
  • Special dependent coverage notes:
    • Group health plans: a child placed for adoption is covered from placement, before the adoption is final (federal law, not HIPAA)
    • Dependents covered until age 26 (ACA) regardless of status
    • Disabled dependents covered indefinitely until self-supporting

Conversion privilege (group policy or state law); HIPAA new-hire portability

  • Allows conversion to individual policy within 31 days of qualifying event
  • No evidence of insurability required
  • Who may convert depends on the policy and state law (e.g., Wyoming: coverage ending for any reason after 3+ months, except unpaid contribution or replacement within 31 days; also surviving spouse/children, divorced spouse, child no longer dependent)
  • New employees with 12+ months prior group coverage (gap <63 days) get immediate coverage, no waiting periods

COBRA (Consolidated Omnibus Budget Reconciliation Act)

  • Applies to employers with 20+ employees; requires continuation of group benefits after qualifying event
  • Premium: up to 102% of normal premium
  • Coverage duration: 18 months standard; 36 months for death, divorce or legal separation, Medicare entitlement, or dependent aging out; disability extends 18 to 29 months
  • Election window: 60 days to notify; premium due within 45 days of election
  • Enables “free coverage” gap-filling strategy before new job coverage begins
  • HIPAA requires insurers to offer ≥2 guaranteed-issue individual plans to those who exhausted COBRA and have no other coverage option

Other means of covering groups

  • Blanket disability insurance: covers a changing, nameless class; coverage begins/ends with class membership (e.g., camp attendees)
  • Franchise insurance: similar to METs but issues individual policies; lower premiums due to reduced admin costs
  • Multiple Employer Welfare Association (MEWA): self-funded benefits for employees of multiple large employers; growth slowed due to stricter reserve requirements

Chapter vocabulary

  • Conversion privilege: right to switch from group to individual policy after qualifying event, without insurability proof
  • Noncontributory: plan where employer pays full premium, employee contributes nothing

Sign up for free to take 45 quiz questions on this topic

Previous
Next  | 19. The Affordable Care Act (ACA)
All rights reserved ©2016 - 2026 Achievable, Inc.

Group Health Underwriting

Some of the rules in this chapter, such as pre-existing condition limitations and COBRA continuation, have been changed or modified by the Affordable Care Act (ACA). However, for exam purposes, these provisions are still tested in their original form. A separate chapter covers ACA-specific updates in detail. This chapter focuses on traditional group health underwriting topics that remain common on exams.

Group underwriting

Group health underwriting evaluates the risk of the group as a whole, not each individual. Underwriters typically don’t require physical exams or individual applications. Instead, they review group-level information such as:

  • Size of the group
  • Average age
  • Type of work performed
  • Claims history

Because working populations are generally healthier than the overall population, group plans usually present lower morbidity risk. If the group qualifies, the insurer accepts or rejects the entire group (not individual members).

On each anniversary date, group underwriters review the previous year’s claims experience. This information is used, to some extent, to help determine the next year’s premium.

The variables used to calculate a group health premium are fundamentally the same as those used for an individual health policy. However, health premium calculations are generally more complex than life insurance premium calculations. Key variables include:

  • Interest
  • Expenses
  • Morbidity
  • Claims experience
  • Policy benefits

Similar to mortality tables (which show how many people are expected to die at a given age), morbidity tables show how many people, out of a large group, are expected to become ill or disabled at a given age.

Insurers also impose requirements on group plans to reduce adverse selection and keep administrative costs low. One common requirement is participation percentage:

  • Noncontributory plans (employer pays the full premium) typically require 100% of eligible employees to enroll.
  • Contributory plans (employer and employees share the cost) typically require at least 75% participation.

Insurers often require the employer to pay part of the employee’s premium - commonly 50% or more - for the plan to qualify as contributory.

Employers are free to switch insurance carriers for their group coverage or terminate coverage altogether. Statutory rules regulate the terms and conditions that must be followed when this occurs.

The employees must be notified that the policy is being discontinued.

If a group health plan is discontinued, the plan must provide a reasonable extension of benefits for anyone who is totally disabled on the date it ends. Under the NAIC’s Group Coverage Discontinuance and Replacement Model Regulation, the extension must last at least 12 months under major medical coverage. Under other hospital or medical expense coverage, the plan must provide either an extension of at least 90 days or an accrued-liability provision. Benefits during the extension may be limited to the disabling condition and remain subject to the plan’s usual benefit limits.

When one insurer replaces another:

  • The prior insurer remains liable only to the extent of its accrued liabilities and extensions of benefits.
  • The new insurer must cover all employees who were eligible to participate under the prior insurer.
  • The new insurer must disregard any pre-existing conditions that would otherwise make a participant uninsurable.

Group insurance concepts

Health insurance portability and accountability act (HIPAA)

Under HIPAA, any insurer in the business of writing group health insurance must make the product available to small employer groups (2 to 50 employees) without regard to health status.

HIPAA limits how pre-existing conditions can be handled:

  • The look-back period for pre-existing conditions is limited to 6 months.
  • The maximum probationary period is 12 months (pre-existing conditions will be covered 12 months after enrollment).
  • Each month of prior creditable coverage reduces the probationary period, but coverage before a break of 63 days or more does not count. So if an individual enters a group plan fewer than 63 days after leaving another group plan that covered them for at least 12 months, the new insurer cannot assign a probationary period for pre-existing conditions.

Pregnancy is not a pre-existing condition, and newborn children must be covered from the moment of birth. Under a separate federal law, the Newborns’ and Mothers’ Health Protection Act, a group health plan that covers childbirth may not limit the hospital stay to less than the following, unless the attending provider, in consultation with the mother, decides on an earlier discharge:

  • A 48-hour hospital stay after a vaginal delivery
  • A 96-hour hospital stay after a caesarean birth

The newborn may be enrolled within 30 days without any pre-existing condition limitations.

Sidenote
Know this...

While this is not part of HIPAA, it fits nicely here…and is on the test!

  1. Under federal law, a group health plan that covers dependent children must cover a child placed with an employee for adoption on the same terms as a natural child, even before the adoption is final.
  2. Under the ACA, a dependent child may generally remain covered under a parent’s health plan until age 26, regardless of student status, marital status, residency, or financial dependence.
  3. A mentally or physically handicapped child (any age) can be covered as a dependent on his/her parents policy until he/she becomes self supporting.

A group health policy may include a conversion privilege, and some states’ laws require one. This allows members of the group to convert their coverage to an individual health insurance policy for 31 days after leaving a group plan due to a qualifying event.

The key value of this provision is that evidence of insurability is not required. This can be especially important for someone who has health problems or pre-existing conditions at the time of the qualifying event.

Which events give the right to convert depends on the policy and the state’s law. Wyoming’s law is one example. A member who has been insured under the group for at least 3 months may convert when the member’s group coverage ends for any reason, unless it ended because the member did not pay a required contribution, or the discontinued group coverage was replaced by similar group coverage within 31 days. The privilege also extends to:

  • The surviving spouse and children, when the member dies
  • A spouse who stops being an eligible family member, as on divorce, and the children whose coverage ends at the same time
  • A child who stops being an eligible dependent

Under HIPAA, employers must make full health care coverage available immediately (upon eligibility) to newly hired employees who were previously covered by a group policy for at least 12 months, with no break in coverage greater than 63 days. Coverage must be made available with no probationary, look back, or waiting periods.

Consolidated omnibus budget reconciliation act (COBRA)

COBRA is a federal law that requires, upon the occurrence of a qualifying event, employers with 20 or more employees to provide continuation of benefits under the employer’s group insurance plan for former employees and their dependents (at 102% of the required premium). COBRA provides transitional health care coverage until the employee and dependents can obtain coverage elsewhere.

Generally, the maximum period of coverage continuation is 18 months. However, if the qualifying event was the employee’s death, divorce or legal separation, or entitlement to Medicare, or a dependent child losing dependent status (for example, by attaining age 26), the maximum period of coverage continuation is 36 months. Disability is not a qualifying event, but a qualified beneficiary whom Social Security finds to have been disabled at any time during the first 60 days of continuation coverage can extend the 18 months to 29 months.

Upon the occurrence of a qualifying event, the employee or dependent has 60 days to notify the group insurer or plan administrator of their election to stay in the group plan through COBRA.

In effect, former employees may use the 60 days as a period of “free coverage,” by electing COBRA and paying the premium only if a claim arises. If the employee takes a new job (and enrolls in a new group plan), their new group coverage will most likely take effect before the transitional period allowed under COBRA expires. However, if COBRA is elected, the premium must be paid within 45 days.

HIPAA requires that every insurer who offers individual health insurance must offer at least two plans on a guaranteed issue basis to any individual who has elected and exhausted COBRA and is not eligible for coverage under any other group plan, Medicare, or Medicaid.

COBRA and HIPAA

Other means of covering groups

Blanket disability insurance provides definite, ascertainable benefits to a changing, nameless group of people (the class). Anyone who enters the covered class is automatically covered. When they leave the class, coverage ends.

For example, a scout camp could purchase a blanket disability policy that pays a flat dollar amount (maybe $5,000) to anyone who sustains an injury requiring medical care while attending the camp.

Franchise insurance is similar to the concept of METs (Multiple Employer Trusts), but with franchise insurance, each eligible participant is issued an individual policy. Premium levels are reduced somewhat from those of regular individual policies because of savings in underwriting expenses and plan administration costs.

Another form of group coverage similar to the MET is the Multiple Employer Welfare Association (MEWA), which is an alternative to true group insurance. MEWAs provide self-funded health care benefits to employees of several large employers. In recent years, the growth of MEWAs has slowed due to increased requirements governing legal reserves.

Lesson summary

  • Group underwriting does not assess individuals but considers group data like size and claims history.
  • Group premiums are determined by factors such as morbidity, claims experience, and policy benefits.
  • Requirements like participation percentages reduce adverse selection in group plans.

Under the Health Insurance Portability and Accountability Act (HIPAA), insurers must offer group health insurance to small employers without regard to health status. HIPAA also limits pre-existing condition exclusions and bars treating pregnancy as a pre-existing condition.

  • Qualifying events like termination or death enable conversion to an individual policy without requiring evidence of insurability.
  • The Consolidated Omnibus Budget Reconciliation Act (COBRA) demands that employers provide continuation of benefits after qualifying events.

Alternative group coverage includes blanket disability insurance and franchise insurance, catering to nameless groups with specific benefits. Multiple Employer Welfare Associations (MEWA) offer self-funded benefits to employees of large companies.

Chapter vocabulary

Definitions
Conversion privilege
The right granted the insured to change his/her coverage from a group policy to individual policy. If a member of a group has a qualifying event he/she is given an opportunity to secure an individual policy within a specified period thereafter, regardless of whether or not he/she is in good health at that time.
Noncontributory
A general term used to designate any plan of insurance (usually group) for which the employer pays the entire premium and the employee contributes no part of the premium.
Key points

Introduction / ACA note

  • Chapter covers traditional pre-ACA rules (pre-existing conditions, COBRA) still tested in original form
  • ACA-specific updates covered in separate chapter

Group underwriting

  • Evaluates risk of entire group, not individuals; no physical exams/individual apps
  • Reviewed factors: group size, average age, type of work, claims history
  • Insurer accepts/rejects whole group; reviews claims experience at each anniversary
  • Premium variables: interest, expenses, morbidity, claims experience, policy benefits
  • Morbidity tables predict illness/disability rates by age (like mortality tables for death)

Participation requirements

  • Noncontributory plans (employer pays 100% premium): require 100% employee enrollment
  • Contributory plans (employer & employee share cost): require ≥75% participation
  • Employer typically pays 50%+ of premium to qualify as contributory

Plan termination/replacement rules

  • Employees must be notified of discontinuation
  • Totally disabled at discontinuance: reasonable extension of benefits (NAIC model: at least 12 months under major medical; under other medical coverage, 90 days or an accrued-liability provision)
  • New insurer must cover all previously eligible employees, disregarding pre-existing conditions
  • Prior insurer remains liable only for its accrued liabilities and extensions of benefits (NAIC model)

HIPAA (Health Insurance Portability and Accountability Act)

  • Requires insurers to offer group coverage to small employers (2–50 employees) regardless of health status
  • Pre-existing condition rules:
    • Look-back period: max 6 months
    • Probationary period: max 12 months
    • Prior creditable coverage reduces the probationary period; none after 12+ months of prior coverage with a break under 63 days
  • Pregnancy not pre-existing; newborns covered from birth
    • Childbirth stay (Newborns’ and Mothers’ Health Protection Act, not HIPAA): 48 hrs (vaginal), 96 hrs (C-section)
    • Newborn enrollment: 30 days, no pre-existing limitations
  • Special dependent coverage notes:
    • Group health plans: a child placed for adoption is covered from placement, before the adoption is final (federal law, not HIPAA)
    • Dependents covered until age 26 (ACA) regardless of status
    • Disabled dependents covered indefinitely until self-supporting

Conversion privilege (group policy or state law); HIPAA new-hire portability

  • Allows conversion to individual policy within 31 days of qualifying event
  • No evidence of insurability required
  • Who may convert depends on the policy and state law (e.g., Wyoming: coverage ending for any reason after 3+ months, except unpaid contribution or replacement within 31 days; also surviving spouse/children, divorced spouse, child no longer dependent)
  • New employees with 12+ months prior group coverage (gap <63 days) get immediate coverage, no waiting periods

COBRA (Consolidated Omnibus Budget Reconciliation Act)

  • Applies to employers with 20+ employees; requires continuation of group benefits after qualifying event
  • Premium: up to 102% of normal premium
  • Coverage duration: 18 months standard; 36 months for death, divorce or legal separation, Medicare entitlement, or dependent aging out; disability extends 18 to 29 months
  • Election window: 60 days to notify; premium due within 45 days of election
  • Enables “free coverage” gap-filling strategy before new job coverage begins
  • HIPAA requires insurers to offer ≥2 guaranteed-issue individual plans to those who exhausted COBRA and have no other coverage option

Other means of covering groups

  • Blanket disability insurance: covers a changing, nameless class; coverage begins/ends with class membership (e.g., camp attendees)
  • Franchise insurance: similar to METs but issues individual policies; lower premiums due to reduced admin costs
  • Multiple Employer Welfare Association (MEWA): self-funded benefits for employees of multiple large employers; growth slowed due to stricter reserve requirements

Chapter vocabulary

  • Conversion privilege: right to switch from group to individual policy after qualifying event, without insurability proof
  • Noncontributory: plan where employer pays full premium, employee contributes nothing

More from Group Health Insurance

  • Group Insurance Essentials