This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
Life
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
1. General Insurance Concepts
2. Producer Roles and Receipt Types
3. Principles of Life Insurance
4. Underwriting
5. Term Life Insurance
6. Whole Life Insurance
7. Variable Insurance Products
8. Group Life Insurance
9. Life Insurance Provisions
10. Annuities
10.1 Annuity Basics and Accumulation
10.2 Payouts and Advanced Options
11. Taxation of Life Insurance Products
12. Qualified Retirement Plans
Wrapping up
Achievable logoAchievable logo
10.2 Payouts and Advanced Options
Achievable Life
10. Annuities

Payouts and Advanced Options

10 min read
Font
Discuss
Share
Feedback

Annuity (benefit) payment options

When an annuity is annuitized, the owner chooses how the accumulated value will be paid out. It helps to sort the options along two lines before looking at each one.

Life contingency options versus annuities certain. A life contingency option makes payments that depend on someone being alive: payments continue for as long as the annuitant (or annuitants) lives. Straight life, life with period certain, refund, joint life, and joint and survivor options are all life contingency options. An annuity certain pays for a fixed period or until a fixed amount is exhausted, regardless of whether the annuitant is living. The period certain (fixed period) option is an annuity certain. It guarantees the payments but not income for life, so the annuitant can outlive it.

Single life versus multiple life. A single life option is measured by one annuitant’s life. A multiple life option covers two or more annuitants, most often spouses. Joint life pays until the first death; joint and survivor pays until the last death. Promising payments for longer, whether by continuing them to the last of two deaths or by guaranteeing them to a beneficiary, lowers the amount of each payment.

The available annuity payout options are as follows:

  • Life income (straight): This is typically the riskiest payout option for the owner because it has the highest monthly payment, but no payments continue after death. Payments are guaranteed for the annuitant’s life and stop when the annuitant dies.

  • Period certain (fixed period annuity): This payout option provides payments for a fixed period (for example, 10 or 20 years). If the annuitant dies during that period, a beneficiary receives the remaining payments. If the annuitant lives beyond the period, payments stop when the period ends.

  • Life annuity with period certain: Payments are guaranteed for the annuitant’s lifetime or for a specified period (for example, 10 or 20 years), whichever is longer. If the annuitant dies during the guaranteed period, the beneficiary receives the remaining payments. If the annuitant lives beyond the period, payments continue for life.

  • Refund: This is typically the most conservative option and has the lowest payments. If the annuitant dies before receiving payments equal to the contract’s value at annuitization, the beneficiary receives the remaining balance. Refunds may be paid either in a lump sum (cash refund) or in continued installments (installment refund).

  • Joint and survivor (joint and last survivor): This payout option covers two or more people, commonly spouses. The contract pays monthly as long as at least one annuitant is living. Depending on the contract, the payment may stay the same or be reduced when the first annuitant dies.

  • Joint life: Covers two or more annuitants, but payments stop at the first annuitant’s death. Because payments end sooner, it pays more per month than joint and survivor.
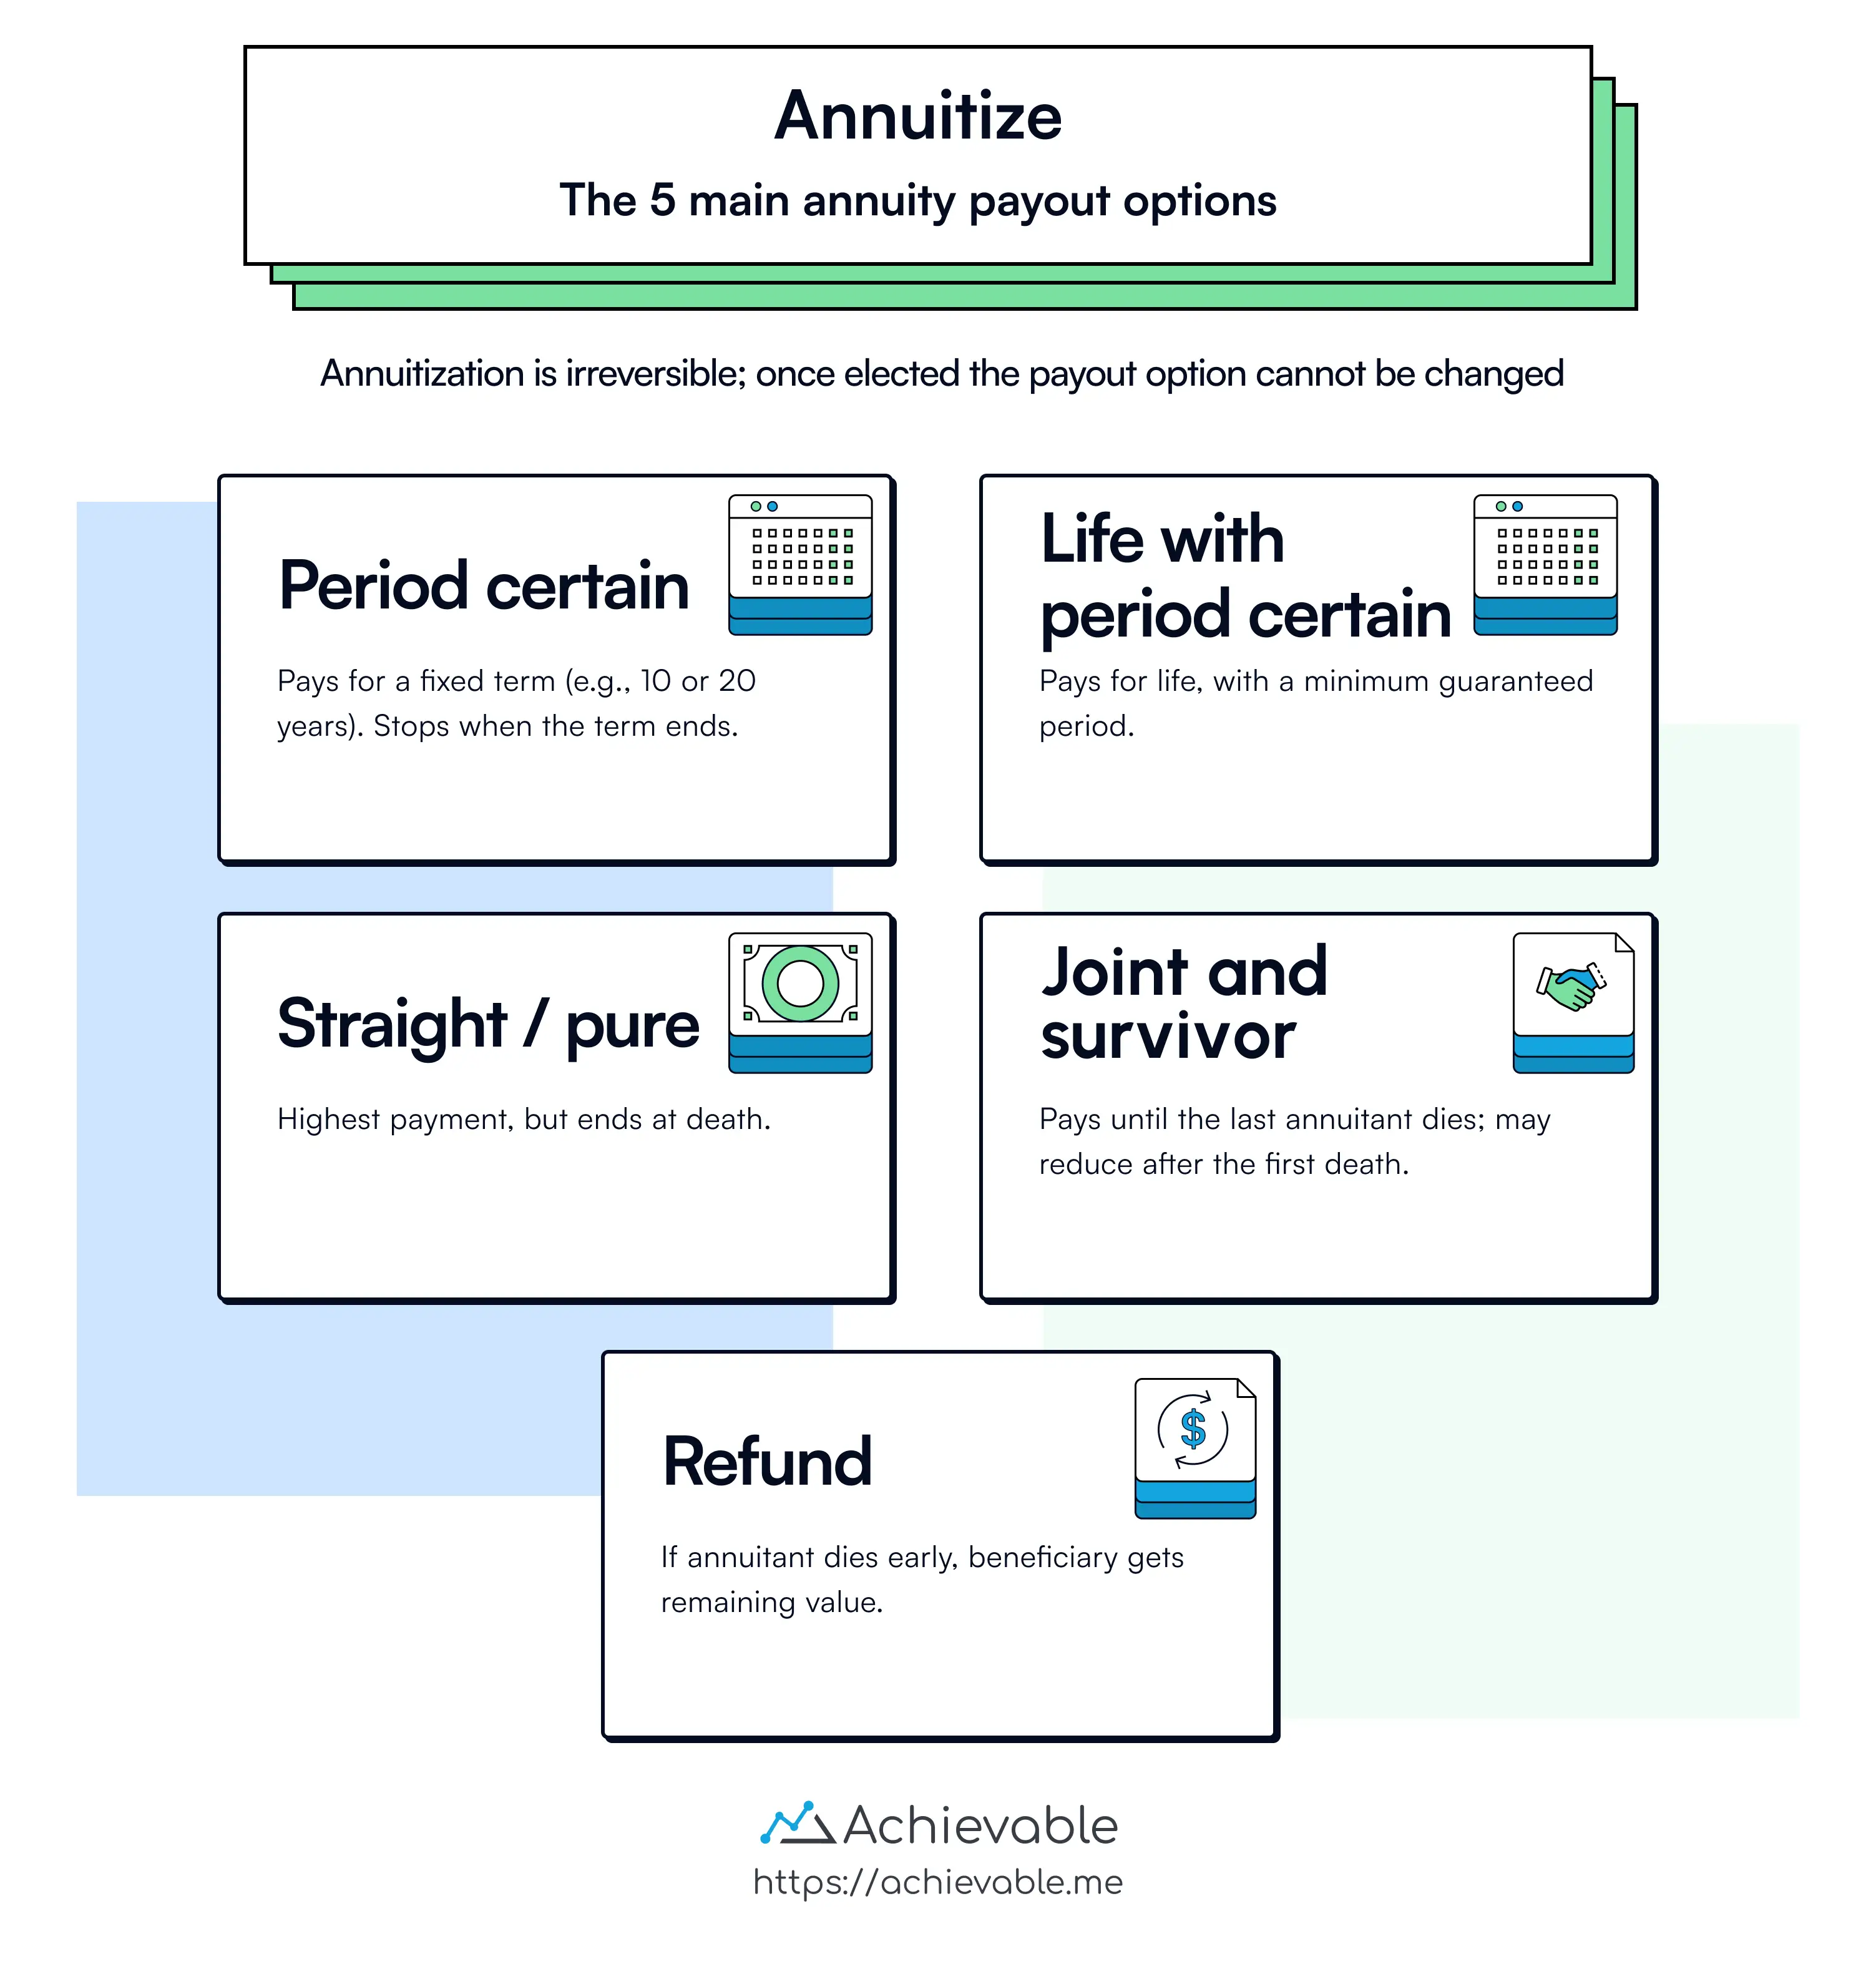
Available annuity payout options

Taxation of annuity payments differs from withdrawals during the accumulation stage. Once a contract has been annuitized for the annuitant’s life or life expectancy, the 10% early withdrawal penalty no longer applies, because the payments are a series of substantially equal payments for life rather than withdrawals. A period certain payout from a deferred annuity that begins before age 59½ does not qualify on that ground. Tax applies only to the portion of each payment that represents growth.

  • Fixed annuity payments stay the same each month.
  • Variable annuity payments may change based on investment performance.

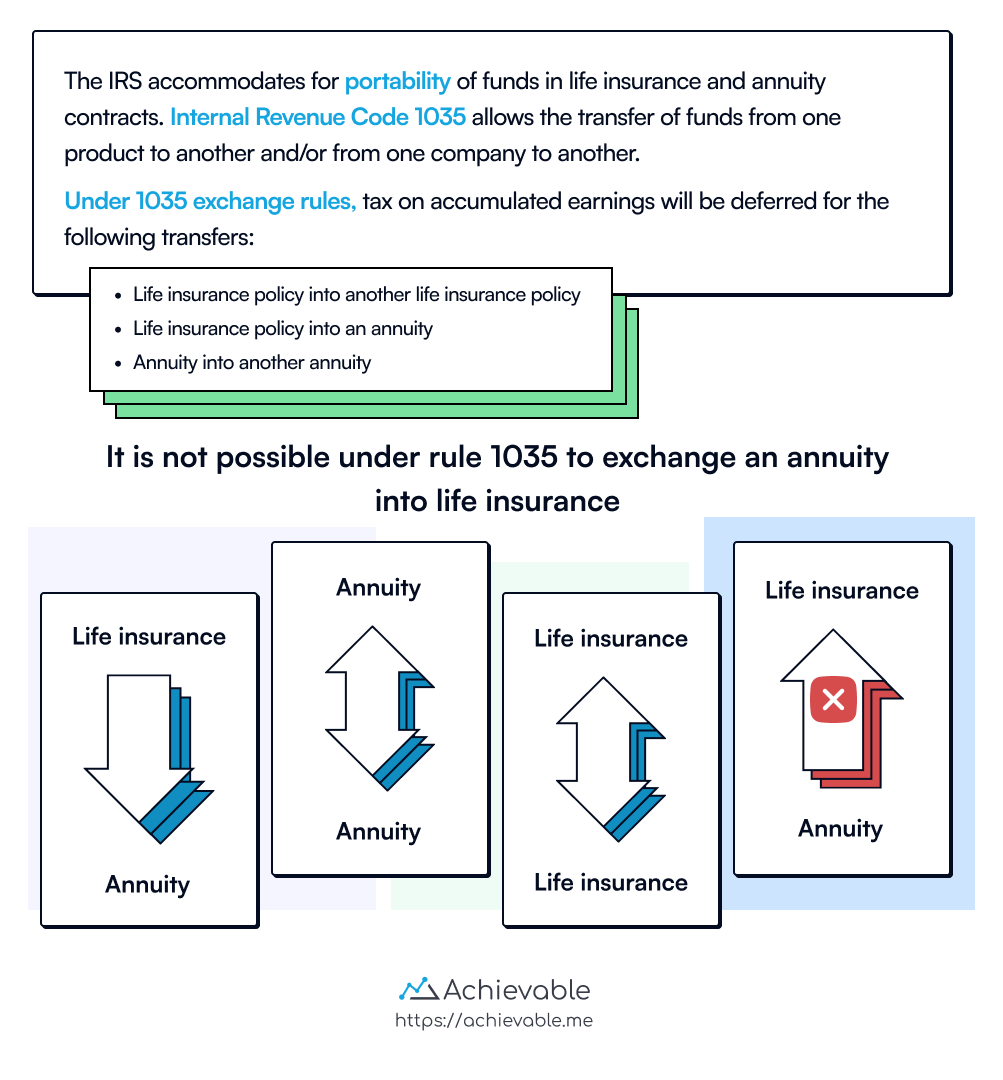
The IRS allows portability of funds in life insurance and annuity contracts. Internal Revenue Code 1035 allows the transfer of funds from one product to another, or from one company to another. Under 1035 exchange rules, tax on accumulated earnings is deferred for the following transfers:

  • Life insurance policy into another life insurance policy
  • Life insurance policy into an annuity
  • Annuity into another annuity
Sidenote
Know this...

It is not possible under rule 1035 to transfer an annuity into life insurance

Internal Revenue Code 1035 rules

Equity indexed annuities

Equity indexed annuities are fixed annuities that guarantee against loss of principal if held to term. With an equity indexed annuity, interest credited is linked to the upward movement of a designated index, such as the Standard and Poor’s 500 (S&P 500).

  • If the index moves upward, the interest rate is based on some portion of the increase.
  • If the index moves downward, the equity indexed annuity does not lose value.

Market value adjusted annuities

Another fixed annuity product with a market-driven aspect is the market value adjusted annuity. Unlike an equity indexed annuity (where interest is linked to an index), a market value adjusted annuity’s interest rate remains fixed. The market value adjustment feature applies only if the contract is surrendered before the contract period expires.

If a market value adjusted annuity owner surrenders the contract early, both a surrender charge and a market value adjustment apply.

  • If interest rates decrease during the contract period, the adjustment is positive and may add to the contract’s surrender value.
  • If interest rates increase during the contract period, the adjustment is negative and may increase the contract’s surrender charge.
Sidenote
Know this...

Marketing material of market value adjusted annuities must plainly state that the adjustment may be positive or negative.

Lesson summary

IRS rules under Code 1035 allow portability of funds between life insurance and annuity contracts, deferring tax on certain transfers such as life-to-life, life-to-annuity, and annuity-to-annuity. Transfers from an annuity into life insurance are not permitted.

  • Equity indexed annuities offer principal protection and interest linked to an index’s upward movement without downside risk.
  • Market value adjusted annuities have fixed interest rates but include a market value adjustment feature upon early surrender, which can increase or decrease surrender value based on interest rate changes.

Payout options are either life contingency options, which pay as long as an annuitant lives, or annuities certain, which pay for a fixed period regardless of whether the annuitant is living. They may be measured by a single life or by multiple lives. Available annuity payout options include life income, period certain, life annuity with period certain, refund, joint life, and joint and survivor. Joint life stops paying at the first annuitant’s death and pays more per month, while joint and survivor pays until the last annuitant dies and may be reduced after the first death. Each option balances monthly income against guarantees for beneficiaries.

Chapter vocabulary

Definitions
Equity Indexed Annuity
A fixed annuity that earns interest or provides benefits that are linked to an external reference or equity index, subject to a minimum guarantee.
Fixed Annuity
An annuity that guarantees a specific rate of return. In the case of a deferred annuity, a minimum rate of interest is guaranteed during the savings phase. During the payment phase, a fixed amount of income, paid on a regular schedule, is guaranteed.
Index Annuity
Equity Indexed Annuity (also called Index Annuity): A fixed annuity that earns interest tied to an external equity index, such as the S&P 500, while protecting principal if held to term.
Joint-Life Annuity
Payout option covering two or more annuitants that stops paying at the first annuitant’s death.
Joint and Survivor Annuity
Payout option covering two or more annuitants that continues to pay until the last annuitant dies, sometimes at a reduced amount after the first death.
Market-Value Adjusted Annuity
An annuity whose accumulated value is subject to a market value adjustment on surrender. The market value adjustment may be positive or negative depending on the movement of interest rates since the inception of the contract.
1035 Exchange
A nontaxable exchange of life insurance policies or annuities, as provided under section 1035 of the Internal Revenue Code.

Payout option categories

  • Life contingency options: pay only while annuitant(s) alive (straight life, period certain life, refund, joint life, joint and survivor)
  • Annuity certain: pays fixed period/amount regardless of survival (e.g., period certain/fixed period annuity); annuitant can outlive it
  • Single life (one annuitant) vs. multiple life (two+, usually spouses); longer guarantees = lower payments

Specific payout options

  • Life income (straight): highest payment, riskiest—stops at death, nothing to beneficiary
  • Period certain: pays fixed term (e.g., 10/20 yrs); beneficiary gets remainder if annuitant dies early
  • Life with period certain: pays for life or guaranteed period, whichever longer
  • Refund: lowest payment, most conservative; beneficiary gets remaining contract value (lump sum or installments) if annuitant dies early
  • Joint life: stops at first death, higher monthly payment
  • Joint and survivor: pays until last death, may reduce after first death, lower monthly payment

Taxation of annuitized payments

  • Once annuitized over life/life expectancy, 10% early withdrawal penalty no longer applies (treated as substantially equal lifetime payments)
  • Period certain payout starting before 59½ does NOT avoid the penalty
  • Only the growth portion of each payment is taxed
  • Fixed annuity payments are level; variable annuity payments fluctuate with investment performance

1035 Exchange rules

  • Allows tax-deferred transfer of funds between contracts:
    • Life insurance → life insurance
    • Life insurance → annuity
    • Annuity → annuity
  • Not allowed: annuity → life insurance

Equity indexed annuities

  • Fixed annuity guaranteeing no loss of principal if held to term
  • Interest credited based on upward movement of an index (e.g., S&P 500)
  • No index movement loss ever reduces contract value

Market value adjusted annuities

  • Fixed interest rate, but includes a market value adjustment (MVA) if surrendered early
  • Interest rates fall → positive adjustment (adds value); interest rates rise → negative adjustment (increases surrender charge)
  • Marketing materials must disclose adjustment can be positive or negative

Sign up for free to take 18 quiz questions on this topic

Previous
Next  | 11. Taxation of Life Insurance Products
All rights reserved ©2016 - 2026 Achievable, Inc.

Payouts and Advanced Options

Annuity (benefit) payment options

When an annuity is annuitized, the owner chooses how the accumulated value will be paid out. It helps to sort the options along two lines before looking at each one.

Life contingency options versus annuities certain. A life contingency option makes payments that depend on someone being alive: payments continue for as long as the annuitant (or annuitants) lives. Straight life, life with period certain, refund, joint life, and joint and survivor options are all life contingency options. An annuity certain pays for a fixed period or until a fixed amount is exhausted, regardless of whether the annuitant is living. The period certain (fixed period) option is an annuity certain. It guarantees the payments but not income for life, so the annuitant can outlive it.

Single life versus multiple life. A single life option is measured by one annuitant’s life. A multiple life option covers two or more annuitants, most often spouses. Joint life pays until the first death; joint and survivor pays until the last death. Promising payments for longer, whether by continuing them to the last of two deaths or by guaranteeing them to a beneficiary, lowers the amount of each payment.

The available annuity payout options are as follows:

  • Life income (straight): This is typically the riskiest payout option for the owner because it has the highest monthly payment, but no payments continue after death. Payments are guaranteed for the annuitant’s life and stop when the annuitant dies.

  • Period certain (fixed period annuity): This payout option provides payments for a fixed period (for example, 10 or 20 years). If the annuitant dies during that period, a beneficiary receives the remaining payments. If the annuitant lives beyond the period, payments stop when the period ends.

  • Life annuity with period certain: Payments are guaranteed for the annuitant’s lifetime or for a specified period (for example, 10 or 20 years), whichever is longer. If the annuitant dies during the guaranteed period, the beneficiary receives the remaining payments. If the annuitant lives beyond the period, payments continue for life.

  • Refund: This is typically the most conservative option and has the lowest payments. If the annuitant dies before receiving payments equal to the contract’s value at annuitization, the beneficiary receives the remaining balance. Refunds may be paid either in a lump sum (cash refund) or in continued installments (installment refund).

  • Joint and survivor (joint and last survivor): This payout option covers two or more people, commonly spouses. The contract pays monthly as long as at least one annuitant is living. Depending on the contract, the payment may stay the same or be reduced when the first annuitant dies.

  • Joint life: Covers two or more annuitants, but payments stop at the first annuitant’s death. Because payments end sooner, it pays more per month than joint and survivor.

Available annuity payout options

Taxation of annuity payments differs from withdrawals during the accumulation stage. Once a contract has been annuitized for the annuitant’s life or life expectancy, the 10% early withdrawal penalty no longer applies, because the payments are a series of substantially equal payments for life rather than withdrawals. A period certain payout from a deferred annuity that begins before age 59½ does not qualify on that ground. Tax applies only to the portion of each payment that represents growth.

  • Fixed annuity payments stay the same each month.
  • Variable annuity payments may change based on investment performance.

The IRS allows portability of funds in life insurance and annuity contracts. Internal Revenue Code 1035 allows the transfer of funds from one product to another, or from one company to another. Under 1035 exchange rules, tax on accumulated earnings is deferred for the following transfers:

  • Life insurance policy into another life insurance policy
  • Life insurance policy into an annuity
  • Annuity into another annuity
Sidenote
Know this...

It is not possible under rule 1035 to transfer an annuity into life insurance

Internal Revenue Code 1035 rules

Equity indexed annuities

Equity indexed annuities are fixed annuities that guarantee against loss of principal if held to term. With an equity indexed annuity, interest credited is linked to the upward movement of a designated index, such as the Standard and Poor’s 500 (S&P 500).

  • If the index moves upward, the interest rate is based on some portion of the increase.
  • If the index moves downward, the equity indexed annuity does not lose value.

Market value adjusted annuities

Another fixed annuity product with a market-driven aspect is the market value adjusted annuity. Unlike an equity indexed annuity (where interest is linked to an index), a market value adjusted annuity’s interest rate remains fixed. The market value adjustment feature applies only if the contract is surrendered before the contract period expires.

If a market value adjusted annuity owner surrenders the contract early, both a surrender charge and a market value adjustment apply.

  • If interest rates decrease during the contract period, the adjustment is positive and may add to the contract’s surrender value.
  • If interest rates increase during the contract period, the adjustment is negative and may increase the contract’s surrender charge.
Sidenote
Know this...

Marketing material of market value adjusted annuities must plainly state that the adjustment may be positive or negative.

Lesson summary

IRS rules under Code 1035 allow portability of funds between life insurance and annuity contracts, deferring tax on certain transfers such as life-to-life, life-to-annuity, and annuity-to-annuity. Transfers from an annuity into life insurance are not permitted.

  • Equity indexed annuities offer principal protection and interest linked to an index’s upward movement without downside risk.
  • Market value adjusted annuities have fixed interest rates but include a market value adjustment feature upon early surrender, which can increase or decrease surrender value based on interest rate changes.

Payout options are either life contingency options, which pay as long as an annuitant lives, or annuities certain, which pay for a fixed period regardless of whether the annuitant is living. They may be measured by a single life or by multiple lives. Available annuity payout options include life income, period certain, life annuity with period certain, refund, joint life, and joint and survivor. Joint life stops paying at the first annuitant’s death and pays more per month, while joint and survivor pays until the last annuitant dies and may be reduced after the first death. Each option balances monthly income against guarantees for beneficiaries.

Chapter vocabulary

Definitions
Equity Indexed Annuity
A fixed annuity that earns interest or provides benefits that are linked to an external reference or equity index, subject to a minimum guarantee.
Fixed Annuity
An annuity that guarantees a specific rate of return. In the case of a deferred annuity, a minimum rate of interest is guaranteed during the savings phase. During the payment phase, a fixed amount of income, paid on a regular schedule, is guaranteed.
Index Annuity
Equity Indexed Annuity (also called Index Annuity): A fixed annuity that earns interest tied to an external equity index, such as the S&P 500, while protecting principal if held to term.
Joint-Life Annuity
Payout option covering two or more annuitants that stops paying at the first annuitant’s death.
Joint and Survivor Annuity
Payout option covering two or more annuitants that continues to pay until the last annuitant dies, sometimes at a reduced amount after the first death.
Market-Value Adjusted Annuity
An annuity whose accumulated value is subject to a market value adjustment on surrender. The market value adjustment may be positive or negative depending on the movement of interest rates since the inception of the contract.
1035 Exchange
A nontaxable exchange of life insurance policies or annuities, as provided under section 1035 of the Internal Revenue Code.
Key points

Payout option categories

  • Life contingency options: pay only while annuitant(s) alive (straight life, period certain life, refund, joint life, joint and survivor)
  • Annuity certain: pays fixed period/amount regardless of survival (e.g., period certain/fixed period annuity); annuitant can outlive it
  • Single life (one annuitant) vs. multiple life (two+, usually spouses); longer guarantees = lower payments

Specific payout options

  • Life income (straight): highest payment, riskiest—stops at death, nothing to beneficiary
  • Period certain: pays fixed term (e.g., 10/20 yrs); beneficiary gets remainder if annuitant dies early
  • Life with period certain: pays for life or guaranteed period, whichever longer
  • Refund: lowest payment, most conservative; beneficiary gets remaining contract value (lump sum or installments) if annuitant dies early
  • Joint life: stops at first death, higher monthly payment
  • Joint and survivor: pays until last death, may reduce after first death, lower monthly payment

Taxation of annuitized payments

  • Once annuitized over life/life expectancy, 10% early withdrawal penalty no longer applies (treated as substantially equal lifetime payments)
  • Period certain payout starting before 59½ does NOT avoid the penalty
  • Only the growth portion of each payment is taxed
  • Fixed annuity payments are level; variable annuity payments fluctuate with investment performance

1035 Exchange rules

  • Allows tax-deferred transfer of funds between contracts:
    • Life insurance → life insurance
    • Life insurance → annuity
    • Annuity → annuity
  • Not allowed: annuity → life insurance

Equity indexed annuities

  • Fixed annuity guaranteeing no loss of principal if held to term
  • Interest credited based on upward movement of an index (e.g., S&P 500)
  • No index movement loss ever reduces contract value

Market value adjusted annuities

  • Fixed interest rate, but includes a market value adjustment (MVA) if surrendered early
  • Interest rates fall → positive adjustment (adds value); interest rates rise → negative adjustment (increases surrender charge)
  • Marketing materials must disclose adjustment can be positive or negative

More from Annuities

  • Annuity Basics and Accumulation