


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
ACCA Financial Accounting
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. The context and purpose of financial reporting
2. Accounting principles, concepts and qualitative characteristics
3. Double-entry bookkeeping and accounting systems
4. Recording transactions and events
5. Reconciliations
6. Preparing trial balance
7. Preparing financial statements
7.1 Statements of profit or loss and financial position
7.2 Statement of cash flow
7.2.1 Introduction to cashflow statement
7.2.2 Operating cashflows
7.2.3 Investing and financing cashflows
7.2.4 Comprehensive question
7.2.5 Benefits and drawbacks
7.3 Incomplete records
7.4 Events after the reporting period
7.5 Disclosure-notes
8. Preparing basic consolidated financial statements
9. Interpretation of financial statements
Wrapping up
Achievable logoAchievable logo
7.2.3 Investing and financing cashflows
Achievable ACCA Financial Accounting
7. Preparing financial statements
7.2. Statement of cash flow
Our ACCA course is currently in development and is a work-in-progress.

Investing and financing cashflows

7 min read
Font
Discuss
Share
Feedback

This chapter focuses on how to calculate cash flows from investing activities and financing activities. Together with operating activities, these two sections complete the statement of cash flows and give users a clear picture of how a business:

  • acquires and disposes of long-term assets
  • raises capital
  • returns funds to its providers of finance

Learning objective

By the end of this chapter, you should be able to:

  • calculate the figures needed for the statement of cash flows in accordance with IFRS Accounting Standards, including:
    • cash flows from investing activities
    • cash flows from financing activities
  • identify the treatment of given transactions in a statement of cash flows

IAS 7, as amended by IFRS 18, sets out where interest and dividends belong for an entity without a specified main business activity involving investing or financing - there’s no longer a policy choice.

Investing activities include:

  • purchase or sale of property, plant and equipment, intangible assets, and investments
  • interest received
  • dividends received

Financing activities include:

  • proceeds from issuing shares
  • loans raised or repaid
  • interest paid
  • dividends paid

Cash flow from investing activities

Investing activities focus on the acquisition and disposal of long-term assets and investments. The cash paid for acquisitions and cash received from disposals may not be given directly in the question. When that happens, you’ll use the work-back approach and the movements shown in the statement of financial position.

The work-back approach involves constructing a ledger account for the relevant non-current asset using the information available, typically the opening and closing balances from the statement of financial position, along with any additional information about disposals, depreciation charges, or revaluations during the period. The cash figure then becomes the balancing figure in the ledger account.

Only cash transactions appear in the statement of cash flows. If a non-current asset was acquired through a non-cash transaction (for example, by means of a lease or in exchange for shares), that transaction does not appear in the investing activities section. Instead, it must be disclosed separately as a significant non-cash transaction, in accordance with IAS 7.

Note: Disposals can make the work-back approach more complicated. Where needed, prepare separate accounts for the disposal of asset account and the non-current asset account. Refer to disposal of assets to refresh your memory.

Illustration: investing activities

The opening and closing carrying amounts of property, plant and equipment were $850,000 and $920,000 respectively. During the period, equipment with an original cost of $80,000 and accumulated depreciation of $58,000 was sold at a profit of $6,000.

Required: Calculate cash flows from investing activities.

Suggested solution:

  1. Compute the additions (acquisition) of property, plant and equipment during the period.
(spoiler)
T-account showing PPE totalling 942,000.
PPE ledger account
Achievable

Note: Since the asset was disposed of, the carrying amount (CA) must be written off. Here, the opening and closing balances are given at carrying amount, so you write off the carrying amount, not the original cost. If the question had instead given opening and closing balances at cost, then you would write off the cost of the asset disposed of. The key point is to work with like terms.

This example assumes no depreciation charge for the year. In exam questions, the depreciation charge for the year is credited to the PPE (carrying amount) account alongside the disposal, which increases the balancing additions figure. Any revaluation surplus during the year is debited to the account, because it is a non-cash increase in carrying amount.

  1. Calculate proceeds from the disposal
(spoiler)
T-account showing asset disposal totalling 28,000.
Asset disposal ledger account
Achievable

Recall that when an asset is disposed of, the carrying amount of the asset is transferred to a disposal account. Any profit or loss on disposal is the difference between the proceeds received and the carrying amount of the asset. In this case, the carrying amount is $22,000 ($80,000 cost less $58,000 accumulated depreciation), and a profit of $6,000 was made, so the proceeds must be $28,000. Gain (profit) on disposal is on the debit side of the asset disposal account.

Let’s prepare the cash flow.

(spoiler)

Cash flow from investing activities:

$
Cash paid for property, plant, and equipment (92,000)
Cash received from disposal of equipment 28,000
Net cash flow from investing activities (64,000)

Cash flows from financing activities

Financing activities reflect how the entity raises capital and returns capital to providers.

The work-back approach also applies here. If the cash figure is not directly given, you can derive it by constructing the relevant ledger account and treating the cash movement as the balancing figure.

Dividend payments often need extra care. The cash paid for dividends is not always the same as the dividends declared:

  • Dividends declared increase the dividend payable liability.
  • Dividends paid reduce the dividend payable liability.

So, to find the cash outflow for dividends, you adjust the declared amount for the movement in the dividend payable balance (as shown in the illustration below).

Illustration: financing activities

The extract of the statement of financial position of Asempa Ltd is given as follows.

Closing balances Opening balance
Equity: $ $
Share capital 450,000 400,000
Share premium 130,000 100,000
Liabilities:
Long-term loan 200,000 250,000
Dividend payable 18,000 12,000

Dividends declared during the year were $75,000.

Required: Calculate cash flows from financing activities.

Suggested solution:

You may decide to draw up the general ledgers to determine the cash flow. For share capital, share premium, and loans, this can often be read directly from the movements:

  • An increase (closing balance higher than opening balance) is usually a cash inflow.
  • A decrease (closing balance lower than opening balance) is usually a cash outflow.

Watch out for a bonus issue of shares or shares issued for non-cash consideration (for example, in exchange for assets) - these change share capital without any cash moving, so they must be excluded. Dividends paid cannot be read from the movement in the dividend payable balance; they must be worked out from the dividend payable account, as shown below.

You can confirm each figure by drawing up the relevant ledger accounts.

(spoiler)
$
Proceeds from issue of shares 80,000
Payments of long-term loan (50,000)
Dividend paid (69,000)
Net cash flow from financing activities (39,000)

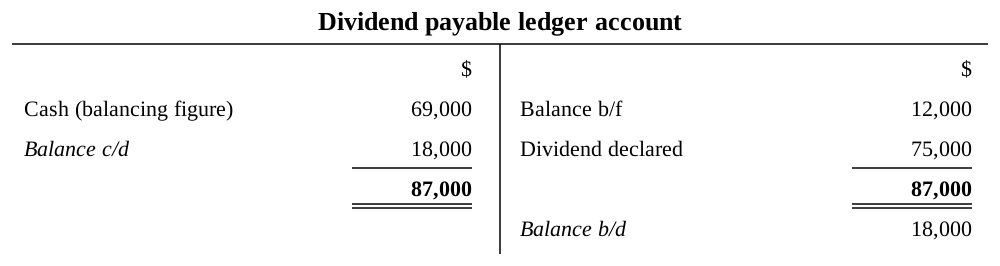
Dividends paid: opening payable 12,000 + declared 75,000 − closing payable 18,000 = 69,000.

Dividend payable ledger account: cash of 69,000 found as the balancing figure and balance c/d of 18,000 on the debit side; balance b/f of 12,000 and dividend declared of 75,000 on the credit side; totals of 87,000; balance b/d of 18,000.
Dividend payable ledger account
Achievable

Classifying investing vs financing activities

  • Investing activities: purchase/sale of PPE, intangibles, investments; interest received; dividends received
  • Financing activities: share issue proceeds; loans raised/repaid; interest paid; dividends paid
  • IAS 7 (amended by IFRS 18): placement of interest/dividends is now fixed, not a policy choice, for entities without specified investing/financing main business

Work-back approach for investing activities

  • Used when cash paid for acquisitions/received from disposals isn’t given directly
  • Build a ledger account for the non-current asset using opening/closing SOFP balances; cash figure = balancing figure
  • Only cash transactions go in the statement of cash flows
    • Non-cash acquisitions (e.g. via lease or shares) excluded; disclosed separately as significant non-cash transactions (IAS 7)
  • With disposals, prepare separate disposal of asset account and non-current asset account
    • Match like terms: if balances given at carrying amount, write off carrying amount; if at cost, write off cost
    • Depreciation charge for the year credited to PPE account (increases additions balancing figure); revaluation surplus debited (non-cash increase)
    • Disposal account: carrying amount transferred in; proceeds = carrying amount + profit (or − loss); profit shown on debit side

Financing activities and the work-back approach

  • Share capital, share premium, loans: cash flow often read directly from movement (increase = inflow, decrease = outflow)
    • Exclude bonus issues or shares issued for non-cash consideration (e.g. for assets) — no cash movement
  • Dividends paid ≠ dividends declared; must adjust for movement in dividend payable liability
    • Formula: opening payable + dividends declared − closing payable = cash paid
    • Confirm via dividend payable ledger account (cash = balancing figure)

Sign up for free to take 12 quiz questions on this topic

Previous
Next  | 7.2.4 Comprehensive question
All rights reserved ©2016 - 2026 Achievable, Inc.

Investing and financing cashflows

This chapter focuses on how to calculate cash flows from investing activities and financing activities. Together with operating activities, these two sections complete the statement of cash flows and give users a clear picture of how a business:

  • acquires and disposes of long-term assets
  • raises capital
  • returns funds to its providers of finance

Learning objective

By the end of this chapter, you should be able to:

  • calculate the figures needed for the statement of cash flows in accordance with IFRS Accounting Standards, including:
    • cash flows from investing activities
    • cash flows from financing activities
  • identify the treatment of given transactions in a statement of cash flows

IAS 7, as amended by IFRS 18, sets out where interest and dividends belong for an entity without a specified main business activity involving investing or financing - there’s no longer a policy choice.

Investing activities include:

  • purchase or sale of property, plant and equipment, intangible assets, and investments
  • interest received
  • dividends received

Financing activities include:

  • proceeds from issuing shares
  • loans raised or repaid
  • interest paid
  • dividends paid

Cash flow from investing activities

Investing activities focus on the acquisition and disposal of long-term assets and investments. The cash paid for acquisitions and cash received from disposals may not be given directly in the question. When that happens, you’ll use the work-back approach and the movements shown in the statement of financial position.

The work-back approach involves constructing a ledger account for the relevant non-current asset using the information available, typically the opening and closing balances from the statement of financial position, along with any additional information about disposals, depreciation charges, or revaluations during the period. The cash figure then becomes the balancing figure in the ledger account.

Only cash transactions appear in the statement of cash flows. If a non-current asset was acquired through a non-cash transaction (for example, by means of a lease or in exchange for shares), that transaction does not appear in the investing activities section. Instead, it must be disclosed separately as a significant non-cash transaction, in accordance with IAS 7.

Note: Disposals can make the work-back approach more complicated. Where needed, prepare separate accounts for the disposal of asset account and the non-current asset account. Refer to disposal of assets to refresh your memory.

Illustration: investing activities

The opening and closing carrying amounts of property, plant and equipment were $850,000 and $920,000 respectively. During the period, equipment with an original cost of $80,000 and accumulated depreciation of $58,000 was sold at a profit of $6,000.

Required: Calculate cash flows from investing activities.

Suggested solution:

  1. Compute the additions (acquisition) of property, plant and equipment during the period.
(spoiler)

Note: Since the asset was disposed of, the carrying amount (CA) must be written off. Here, the opening and closing balances are given at carrying amount, so you write off the carrying amount, not the original cost. If the question had instead given opening and closing balances at cost, then you would write off the cost of the asset disposed of. The key point is to work with like terms.

This example assumes no depreciation charge for the year. In exam questions, the depreciation charge for the year is credited to the PPE (carrying amount) account alongside the disposal, which increases the balancing additions figure. Any revaluation surplus during the year is debited to the account, because it is a non-cash increase in carrying amount.

  1. Calculate proceeds from the disposal
(spoiler)

Recall that when an asset is disposed of, the carrying amount of the asset is transferred to a disposal account. Any profit or loss on disposal is the difference between the proceeds received and the carrying amount of the asset. In this case, the carrying amount is $22,000 ($80,000 cost less $58,000 accumulated depreciation), and a profit of $6,000 was made, so the proceeds must be $28,000. Gain (profit) on disposal is on the debit side of the asset disposal account.

Let’s prepare the cash flow.

(spoiler)

Cash flow from investing activities:

$
Cash paid for property, plant, and equipment (92,000)
Cash received from disposal of equipment 28,000
Net cash flow from investing activities (64,000)

Cash flows from financing activities

Financing activities reflect how the entity raises capital and returns capital to providers.

The work-back approach also applies here. If the cash figure is not directly given, you can derive it by constructing the relevant ledger account and treating the cash movement as the balancing figure.

Dividend payments often need extra care. The cash paid for dividends is not always the same as the dividends declared:

  • Dividends declared increase the dividend payable liability.
  • Dividends paid reduce the dividend payable liability.

So, to find the cash outflow for dividends, you adjust the declared amount for the movement in the dividend payable balance (as shown in the illustration below).

Illustration: financing activities

The extract of the statement of financial position of Asempa Ltd is given as follows.

Closing balances Opening balance
Equity: $ $
Share capital 450,000 400,000
Share premium 130,000 100,000
Liabilities:
Long-term loan 200,000 250,000
Dividend payable 18,000 12,000

Dividends declared during the year were $75,000.

Required: Calculate cash flows from financing activities.

Suggested solution:

You may decide to draw up the general ledgers to determine the cash flow. For share capital, share premium, and loans, this can often be read directly from the movements:

  • An increase (closing balance higher than opening balance) is usually a cash inflow.
  • A decrease (closing balance lower than opening balance) is usually a cash outflow.

Watch out for a bonus issue of shares or shares issued for non-cash consideration (for example, in exchange for assets) - these change share capital without any cash moving, so they must be excluded. Dividends paid cannot be read from the movement in the dividend payable balance; they must be worked out from the dividend payable account, as shown below.

You can confirm each figure by drawing up the relevant ledger accounts.

(spoiler)
$
Proceeds from issue of shares 80,000
Payments of long-term loan (50,000)
Dividend paid (69,000)
Net cash flow from financing activities (39,000)

Dividends paid: opening payable 12,000 + declared 75,000 − closing payable 18,000 = 69,000.

Key points

Classifying investing vs financing activities

  • Investing activities: purchase/sale of PPE, intangibles, investments; interest received; dividends received
  • Financing activities: share issue proceeds; loans raised/repaid; interest paid; dividends paid
  • IAS 7 (amended by IFRS 18): placement of interest/dividends is now fixed, not a policy choice, for entities without specified investing/financing main business

Work-back approach for investing activities

  • Used when cash paid for acquisitions/received from disposals isn’t given directly
  • Build a ledger account for the non-current asset using opening/closing SOFP balances; cash figure = balancing figure
  • Only cash transactions go in the statement of cash flows
    • Non-cash acquisitions (e.g. via lease or shares) excluded; disclosed separately as significant non-cash transactions (IAS 7)
  • With disposals, prepare separate disposal of asset account and non-current asset account
    • Match like terms: if balances given at carrying amount, write off carrying amount; if at cost, write off cost
    • Depreciation charge for the year credited to PPE account (increases additions balancing figure); revaluation surplus debited (non-cash increase)
    • Disposal account: carrying amount transferred in; proceeds = carrying amount + profit (or − loss); profit shown on debit side

Financing activities and the work-back approach

  • Share capital, share premium, loans: cash flow often read directly from movement (increase = inflow, decrease = outflow)
    • Exclude bonus issues or shares issued for non-cash consideration (e.g. for assets) — no cash movement
  • Dividends paid ≠ dividends declared; must adjust for movement in dividend payable liability
    • Formula: opening payable + dividends declared − closing payable = cash paid
    • Confirm via dividend payable ledger account (cash = balancing figure)

More from Statement of cash flow

  • Introduction to cashflow statement
  • Operating cashflows
  • Comprehensive question
  • Benefits and drawbacks