


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
ACCA Financial Accounting
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. The context and purpose of financial reporting
2. Accounting principles, concepts and qualitative characteristics
3. Double-entry bookkeeping and accounting systems
4. Recording transactions and events
4.1 Sales, purchases, receivables and payables
4.2 Inventories
4.3 Accounting for non-current asset
4.3.1 Accounting for tangible non-current assets
4.3.2 Depreciation
4.3.3 Disposal of tangible non-current asset
4.3.4 Revaluation of tangible non-current asset
4.3.5 Disclosure of tangible non-current asset
4.3.6 Intangible non-current asset and amortisation
4.4 Accruals and prepayments
4.5 Provisions and contingencies
4.6 Capital structure and finance costs
4.7 Components of equity
5. Reconciliations
6. Preparing trial balance
7. Preparing financial statements
8. Preparing basic consolidated financial statements
9. Interpretation of financial statements
Wrapping up
Achievable logoAchievable logo
4.3.3 Disposal of tangible non-current asset
Achievable ACCA Financial Accounting
4. Recording transactions and events
4.3. Accounting for non-current asset
Our ACCA course is currently in development and is a work-in-progress.

Disposal of tangible non-current asset

8 min read
Font
Discuss
Share
Feedback

This chapter explains the accounting treatment for disposals of tangible non-current assets. You’ll learn how to record disposals and part-exchange transactions in line with IFRS Accounting Standards, including how to calculate and record any gain or loss on disposal. Disclosure of PPE movements and the non-current asset register are covered in a later chapter.

Learning objectives

By the end of this chapter, you should be able to:

  • Record the acquisition and disposal of tangible non-current assets in the general ledger accounts in accordance with IFRS Accounting Standards.
  • Calculate and record gains or losses on disposal of tangible non-current assets in the statement of profit or loss, including part exchange transactions.

Introduction

Businesses sometimes dispose of tangible non-current assets before the end of their useful life, or at the end of their useful life when a residual value remains. Because selling non-current assets isn’t part of normal trading activities, the proceeds are treated as capital income, not business revenue.

A disposal is recorded through a disposal of non-current assets process. This process removes the asset from the accounting records and reports any resulting gain or loss in the statement of profit or loss.

Definitions
Gain on disposal of non-current asset
A gain arises when the asset’s carrying amount at the date of sale is less than the net proceeds.
Loss on disposal of non-current asset
A loss arises when the asset’s carrying amount at the date of sale is greater than the net proceeds.

A gain on disposal isn’t revenue - it’s capital income, reported separately from trading activity. Under IFRS 18, a gain or loss on disposal of property, plant and equipment used in operations is presented within the operating category of profit or loss, not as part of revenue.

If the asset being disposed of had previously been revalued, the gain or loss is measured against its revalued carrying amount rather than cost less accumulated depreciation. The revaluation model is covered in the next chapter.

Accounting for disposal of non-current asset

When a tangible non-current asset is acquired, it’s recorded in the non-current asset ledger. At each year-end, depreciation is charged to profit or loss, with the corresponding credit posted to accumulated depreciation.

When an asset is disposed of, it must be removed from the books. To do that, we transfer the asset’s cost and accumulated depreciation to a disposal of non-current asset account, record the proceeds, and then calculate the gain or loss.

Disposal steps

Upon the disposal of a tangible non-current asset:

  1. Derecognise the asset, by transferring the cost from the asset account to the disposal of asset account as shown in the journal.

    Debit: Disposal of non-current asset account

    Credit: Non-current asset account

  2. Derecognise the accumulated depreciation, by transferring it from the accumulated depreciation account as at the date of the sale to the disposal of asset account as shown in the journal.

    Debit: Accumulated depreciation account

    Credit: Disposal of non-current asset account

  3. Record the proceeds from the disposal as shown in the journal:

    Debit: Cash or receivable account

    Credit: Disposal of non-current asset account

  4. Balance off the disposal of asset accounts. There is a gain on disposal when the balancing figure is on the debit, and it is a loss on disposal when the balancing figure is on the credit.

    • When it is loss on disposal, the journal entry will be:

      Debit: Statement of profit or loss (loss on disposal)

      Credit: Disposal of non-current asset account

    • When it is a gain on disposal, the journal entry will be:

      Debit: Disposal of non-current asset account

      Credit: Statement of profit or loss (gain on disposal)

Illustration: disposal of tangible non-current asset

D&D Ltd acquired a factory plant for $100,000 on 1 January 20X0 with an estimated residual value of zero and depreciated over its useful life of 5 years. At the end of the year 3 (i.e., 31 December 20X2), D&D sold the plant for $45,000 cash. Illustrate the accounting treatment of the transaction in the financial statement.

Suggested solution:

Work through the following before checking the solution: what’s the annual depreciation, the accumulated depreciation at the disposal date, the carrying amount at the disposal date, and the gain or loss on disposal?

(spoiler)
  • Annual depreciation: ($100,000 - 0) / 5 years = $20,000
  • Accumulated depreciation at the disposal date (3 years of use): $20,000 × 3 = $60,000
  • Carrying amount at the disposal date (cost minus accumulated depreciation): $100,000 - $60,000 = $40,000
  • Gain or loss on disposal (proceeds minus carrying amount): $45,000 - $40,000 = $5,000 (gain)

The calculations tell you the gain or loss, but you also need to know the journal entries that record the disposal in the general ledger. The journal to account for the disposal is shown below.

Description Debit ($) Credit ($)
Derecognising the factory plant cost
Disposal of asset 100,000
Factory plant 100,000
Derecognise the accumulated depreciation
Accumulated depreciation 60,000
Disposal of asset 60,000
Recognise the proceeds from the disposal
Cash and Bank 45,000
Disposal of asset 45,000
Transfer gain to profit or loss
Disposal of asset 5,000
Profit or loss 5,000

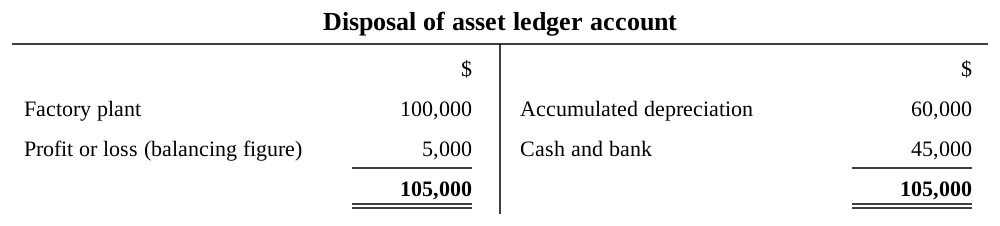
The disposal of the asset ledger account is shown below.

Disposal of asset ledger account: factory plant of 100,000 and profit or loss of 5,000, the gain found as the balancing figure, on the debit side; accumulated depreciation of 60,000 and cash and bank of 45,000 on the credit side; totals of 105,000.
Disposal of asset ledger account
Achievable

Disposal of asset: part exchange transactions

Sometimes, a business acquires a new non-current asset by exchanging an old one and paying an additional amount. The value assigned to the old asset in this arrangement is called the trade-in price.

In a part-exchange, the trade-in price is treated as the proceeds from disposal of the old asset. So, instead of crediting cash or receivables, you credit the trade-in value to the disposal account. The cost of the new asset (trade-in value + additional cash paid) is then debited to the non-current asset account.

Illustration: part exchange transactions

D&D Ltd acquired a factory plant for $100,000 on 1 January 20X0 with an estimated residual value of zero and depreciated over its useful life of 5 years. At the end of year 3 (i.e., 31 December 20X2), D&D traded in the plant for $30,000 for the purchase of a new asset costing $120,000.

Illustrate the accounting treatment of the transaction in the financial statement.

Suggested solution:

The step-by-step guide in the earlier illustration above should guide you to solve this question.

  1. What are the journal entries to be passed for the disposal of the factory plant as well as the purchase of the new asset?
(spoiler)

Journal entries

Steps 1 and 2 - derecognising the old factory plant’s cost and its accumulated depreciation - are identical to the first illustration above: debit disposal of asset $100,000 / credit factory plant $100,000, and debit accumulated depreciation $60,000 / credit disposal of asset $60,000. This leaves a carrying amount of $40,000.

The trade-in allowance of $30,000 is less than this $40,000 carrying amount, so the disposal results in a loss: $40,000 − $30,000 = $10,000.

Description Debit ($) Credit ($)
Recognise the trade-in allowance as the proceeds
Trade-in allowance 30,000
Disposal of asset 30,000
Recognise the value of the new factory plant
Factory plant 120,000
Cash and bank 90,000
Trade-in allowance 30,000
Transfer loss to profit or loss
Profit or loss 10,000
Disposal of asset 10,000

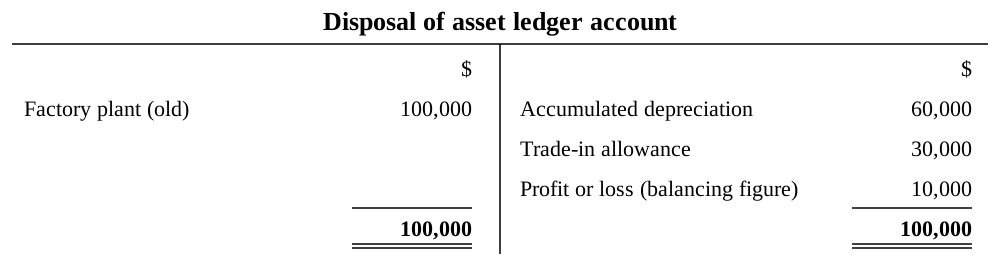
The disposal of the asset ledger account is shown below.

Disposal of asset ledger account: factory plant (old) of 100,000 on the debit side; accumulated depreciation of 60,000, trade-in allowance of 30,000 and loss on disposal of 10,000, taken to profit or loss as the balancing figure, on the credit side; totals of 100,000.
Disposal of asset ledger account (part exchange)
Achievable

Disposal basics

  • Proceeds from selling non-current assets are capital income, not revenue
  • Gain: carrying amount < net proceeds; Loss: carrying amount > net proceeds
  • Under IFRS 18, gain/loss on disposal of PPE used in operations sits in operating profit or loss, separate from revenue
  • If asset was previously revalued, compare proceeds to revalued carrying amount (not cost less depreciation)

Recording a disposal: four steps

  • Derecognise cost: debit Disposal account / credit Asset account
  • Derecognise accumulated depreciation: debit Accumulated depreciation / credit Disposal account
  • Record proceeds: debit Cash/receivable / credit Disposal account
  • Balance the disposal account:
    • Balancing figure on debit side = gain → debit Disposal, credit Statement of profit or loss
    • Balancing figure on credit side = loss → debit Statement of profit or loss, credit Disposal
  • Carrying amount = cost − accumulated depreciation to date of sale; compare to proceeds to find gain/loss

Part-exchange transactions

  • Old asset’s trade-in price is treated as its disposal proceeds (credited to Disposal account instead of cash)
  • New asset’s cost = trade-in value + additional cash paid, debited to the Non-current asset account
  • Gain/loss still calculated by comparing old asset’s carrying amount to the trade-in allowance (proceeds)
  • Example: carrying amount $40,000 vs trade-in $30,000 → $10,000 loss on disposal

Sign up for free to take 9 quiz questions on this topic

Previous
Next  | 4.3.4 Revaluation of tangible non-current asset
All rights reserved ©2016 - 2026 Achievable, Inc.

Disposal of tangible non-current asset

This chapter explains the accounting treatment for disposals of tangible non-current assets. You’ll learn how to record disposals and part-exchange transactions in line with IFRS Accounting Standards, including how to calculate and record any gain or loss on disposal. Disclosure of PPE movements and the non-current asset register are covered in a later chapter.

Learning objectives

By the end of this chapter, you should be able to:

  • Record the acquisition and disposal of tangible non-current assets in the general ledger accounts in accordance with IFRS Accounting Standards.
  • Calculate and record gains or losses on disposal of tangible non-current assets in the statement of profit or loss, including part exchange transactions.

Introduction

Businesses sometimes dispose of tangible non-current assets before the end of their useful life, or at the end of their useful life when a residual value remains. Because selling non-current assets isn’t part of normal trading activities, the proceeds are treated as capital income, not business revenue.

A disposal is recorded through a disposal of non-current assets process. This process removes the asset from the accounting records and reports any resulting gain or loss in the statement of profit or loss.

Definitions
Gain on disposal of non-current asset
A gain arises when the asset’s carrying amount at the date of sale is less than the net proceeds.
Loss on disposal of non-current asset
A loss arises when the asset’s carrying amount at the date of sale is greater than the net proceeds.

A gain on disposal isn’t revenue - it’s capital income, reported separately from trading activity. Under IFRS 18, a gain or loss on disposal of property, plant and equipment used in operations is presented within the operating category of profit or loss, not as part of revenue.

If the asset being disposed of had previously been revalued, the gain or loss is measured against its revalued carrying amount rather than cost less accumulated depreciation. The revaluation model is covered in the next chapter.

Accounting for disposal of non-current asset

When a tangible non-current asset is acquired, it’s recorded in the non-current asset ledger. At each year-end, depreciation is charged to profit or loss, with the corresponding credit posted to accumulated depreciation.

When an asset is disposed of, it must be removed from the books. To do that, we transfer the asset’s cost and accumulated depreciation to a disposal of non-current asset account, record the proceeds, and then calculate the gain or loss.

Disposal steps

Upon the disposal of a tangible non-current asset:

  1. Derecognise the asset, by transferring the cost from the asset account to the disposal of asset account as shown in the journal.

    Debit: Disposal of non-current asset account

    Credit: Non-current asset account

  2. Derecognise the accumulated depreciation, by transferring it from the accumulated depreciation account as at the date of the sale to the disposal of asset account as shown in the journal.

    Debit: Accumulated depreciation account

    Credit: Disposal of non-current asset account

  3. Record the proceeds from the disposal as shown in the journal:

    Debit: Cash or receivable account

    Credit: Disposal of non-current asset account

  4. Balance off the disposal of asset accounts. There is a gain on disposal when the balancing figure is on the debit, and it is a loss on disposal when the balancing figure is on the credit.

    • When it is loss on disposal, the journal entry will be:

      Debit: Statement of profit or loss (loss on disposal)

      Credit: Disposal of non-current asset account

    • When it is a gain on disposal, the journal entry will be:

      Debit: Disposal of non-current asset account

      Credit: Statement of profit or loss (gain on disposal)

Illustration: disposal of tangible non-current asset

D&D Ltd acquired a factory plant for $100,000 on 1 January 20X0 with an estimated residual value of zero and depreciated over its useful life of 5 years. At the end of the year 3 (i.e., 31 December 20X2), D&D sold the plant for $45,000 cash. Illustrate the accounting treatment of the transaction in the financial statement.

Suggested solution:

Work through the following before checking the solution: what’s the annual depreciation, the accumulated depreciation at the disposal date, the carrying amount at the disposal date, and the gain or loss on disposal?

(spoiler)
  • Annual depreciation: ($100,000 - 0) / 5 years = $20,000
  • Accumulated depreciation at the disposal date (3 years of use): $20,000 × 3 = $60,000
  • Carrying amount at the disposal date (cost minus accumulated depreciation): $100,000 - $60,000 = $40,000
  • Gain or loss on disposal (proceeds minus carrying amount): $45,000 - $40,000 = $5,000 (gain)

The calculations tell you the gain or loss, but you also need to know the journal entries that record the disposal in the general ledger. The journal to account for the disposal is shown below.

Description Debit ($) Credit ($)
Derecognising the factory plant cost
Disposal of asset 100,000
Factory plant 100,000
Derecognise the accumulated depreciation
Accumulated depreciation 60,000
Disposal of asset 60,000
Recognise the proceeds from the disposal
Cash and Bank 45,000
Disposal of asset 45,000
Transfer gain to profit or loss
Disposal of asset 5,000
Profit or loss 5,000

The disposal of the asset ledger account is shown below.

Disposal of asset: part exchange transactions

Sometimes, a business acquires a new non-current asset by exchanging an old one and paying an additional amount. The value assigned to the old asset in this arrangement is called the trade-in price.

In a part-exchange, the trade-in price is treated as the proceeds from disposal of the old asset. So, instead of crediting cash or receivables, you credit the trade-in value to the disposal account. The cost of the new asset (trade-in value + additional cash paid) is then debited to the non-current asset account.

Illustration: part exchange transactions

D&D Ltd acquired a factory plant for $100,000 on 1 January 20X0 with an estimated residual value of zero and depreciated over its useful life of 5 years. At the end of year 3 (i.e., 31 December 20X2), D&D traded in the plant for $30,000 for the purchase of a new asset costing $120,000.

Illustrate the accounting treatment of the transaction in the financial statement.

Suggested solution:

The step-by-step guide in the earlier illustration above should guide you to solve this question.

  1. What are the journal entries to be passed for the disposal of the factory plant as well as the purchase of the new asset?
(spoiler)

Journal entries

Steps 1 and 2 - derecognising the old factory plant’s cost and its accumulated depreciation - are identical to the first illustration above: debit disposal of asset $100,000 / credit factory plant $100,000, and debit accumulated depreciation $60,000 / credit disposal of asset $60,000. This leaves a carrying amount of $40,000.

The trade-in allowance of $30,000 is less than this $40,000 carrying amount, so the disposal results in a loss: $40,000 − $30,000 = $10,000.

Description Debit ($) Credit ($)
Recognise the trade-in allowance as the proceeds
Trade-in allowance 30,000
Disposal of asset 30,000
Recognise the value of the new factory plant
Factory plant 120,000
Cash and bank 90,000
Trade-in allowance 30,000
Transfer loss to profit or loss
Profit or loss 10,000
Disposal of asset 10,000

The disposal of the asset ledger account is shown below.

Key points

Disposal basics

  • Proceeds from selling non-current assets are capital income, not revenue
  • Gain: carrying amount < net proceeds; Loss: carrying amount > net proceeds
  • Under IFRS 18, gain/loss on disposal of PPE used in operations sits in operating profit or loss, separate from revenue
  • If asset was previously revalued, compare proceeds to revalued carrying amount (not cost less depreciation)

Recording a disposal: four steps

  • Derecognise cost: debit Disposal account / credit Asset account
  • Derecognise accumulated depreciation: debit Accumulated depreciation / credit Disposal account
  • Record proceeds: debit Cash/receivable / credit Disposal account
  • Balance the disposal account:
    • Balancing figure on debit side = gain → debit Disposal, credit Statement of profit or loss
    • Balancing figure on credit side = loss → debit Statement of profit or loss, credit Disposal
  • Carrying amount = cost − accumulated depreciation to date of sale; compare to proceeds to find gain/loss

Part-exchange transactions

  • Old asset’s trade-in price is treated as its disposal proceeds (credited to Disposal account instead of cash)
  • New asset’s cost = trade-in value + additional cash paid, debited to the Non-current asset account
  • Gain/loss still calculated by comparing old asset’s carrying amount to the trade-in allowance (proceeds)
  • Example: carrying amount $40,000 vs trade-in $30,000 → $10,000 loss on disposal

More from Accounting for non-current asset

  • Accounting for tangible non-current assets
  • Depreciation
  • Revaluation of tangible non-current asset
  • Disclosure of tangible non-current asset
  • Intangible non-current asset and amortisation