


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
ACCA Financial Accounting
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. The context and purpose of financial reporting
2. Accounting principles, concepts and qualitative characteristics
3. Double-entry bookkeeping and accounting systems
4. Recording transactions and events
4.1 Sales, purchases, receivables and payables
4.2 Inventories
4.3 Accounting for non-current asset
4.3.1 Accounting for tangible non-current assets
4.3.2 Depreciation
4.3.3 Disposal of tangible non-current asset
4.3.4 Revaluation of tangible non-current asset
4.3.5 Disclosure of tangible non-current asset
4.3.6 Intangible non-current asset and amortisation
4.4 Accruals and prepayments
4.5 Provisions and contingencies
4.6 Capital structure and finance costs
4.7 Components of equity
5. Reconciliations
6. Preparing trial balance
7. Preparing financial statements
8. Preparing basic consolidated financial statements
9. Interpretation of financial statements
Wrapping up
Achievable logoAchievable logo
4.3.2 Depreciation
Achievable ACCA Financial Accounting
4. Recording transactions and events
4.3. Accounting for non-current asset
Our ACCA course is currently in development and is a work-in-progress.

Depreciation

13 min read
Font
Discuss
Share
Feedback

This chapter introduces depreciation and explains why it matters in financial reporting. You’ll see how depreciation is recorded in the general ledger, how it affects both the statement of profit or loss and the statement of financial position, and how accumulated depreciation builds up over time.

Learning objectives

By the end of this chapter, you should be able to:

  • Explain the purpose of depreciation.
  • Calculate the charge for depreciation using straight-line and diminishing balance (reducing-balance) methods.
  • Identify the circumstances where different methods of depreciation would be appropriate.
  • Illustrate how the depreciation charge and accumulated depreciation are recorded in the general ledger accounts.
  • Calculate the adjustments to depreciation necessary if changes are made in the estimated useful life and/or residual value of a tangible non-current asset.
  • Record depreciation in the statement of profit or loss and statement of financial position.

Definition of key terms

As covered in the previous chapter, the full cost of a non-current asset is not expensed in the year of acquisition. Instead, the portion of the asset’s economic benefits that is consumed each period is charged to profit or loss as depreciation.

Definitions
Depreciation
The systematic allocation of the depreciable amount of an asset over its useful life.
Depreciable amount
The cost of an asset or its revalued amount (when revalued) minus its residual value.
Residual value
The estimated amount the entity would currently obtain from disposing of the asset, after deducting the estimated costs of disposal, if the asset were already of the age and in the condition expected at the end of its useful life.
Useful life
The period over which an asset is expected to be used by the entity. Physical wear and tear, technological advancements, usage patterns, and economic conditions are factors that need to be considered before estimating the useful life of an asset.

Methods of depreciation

There are several methods of depreciation. However, for the purposes of the syllabus, we will focus on:

  • Straight line method
  • Reducing balance method

Straight line method

This is the simplest and most commonly used method. Under the straight-line method, the asset’s depreciable amount is spread evenly over its useful life, so the annual depreciation expense is constant.

The formula is:

Depreciation charge=Useful lifeCost of asset−Residual value​

Under this method, except where the asset is being revalued (covered later, in Revaluation of tangible non-current asset), the annual depreciation charge will be the same each year.

Illustration: straight line method

Assume Gyabaku Ltd acquired the machine for $543,000 on 1 January 20X0. Gyabaku Ltd must estimate the machine’s useful life (the period over which it will be used in operations); organisations typically specify useful lives for each asset class in their accounting policies. Its estimated useful life is 10 years with a residual value of $10,000.

The depreciable amount is the cost minus the residual value: $543,000 - $10,000 = $533,000.

The annual charge is:

10 years$543,000−$10,000​=$53,300 per year

Each year, the carrying amount (also called net book value) falls by the $53,300 depreciation charge: from $543,000 at acquisition to $489,700 at the end of 20X0, $436,400 at the end of 20X1, and $383,100 at the end of 20X2.

Note: Carrying amount (net book value) = cost less accumulated depreciation. Equivalently, each year’s closing carrying amount is the opening carrying amount minus that year’s charge.

Straight line method: depreciation in percentage

Because the annual depreciation charge under the straight-line method is constant, it can also be expressed as a percentage. Check what the percentage is stated on:

  • On cost: multiply the cost by the percentage. Using the example above, the charge of $53,300 is approximately 9.8% on cost ($53,300/$543,000, rounded to one decimal place).
  • On the depreciable amount: multiply cost less residual value by the percentage. The same charge is 10% of the depreciable amount ($53,300/$533,000), which is one year of the 10-year useful life.

If a straight-line rate is given with no base stated and the asset has a residual value, apply it to the depreciable amount, because depreciation allocates the depreciable amount over the useful life. With no residual value, cost and the depreciable amount are the same figure.

Straight-line method: mid-year acquisitions

Sometimes, non-current assets are acquired partway through the year. In that case, the depreciation treatment depends on the firm’s accounting policy - for example:

  • Prorating depreciation based on the period of use, or
  • Charging a full year’s depreciation regardless of the acquisition date.

Illustration: mid-year acquisitions

Assume Gyabaku Ltd acquired the machine at a cost of $543,000 on 1 July 20X0. Its estimated useful life is 10 years with a residual value of $10,000. It is the firm’s policy to depreciate assets from the date of purchase.

The depreciation for the first three years is:

Year-end Computations Depreciation charge
31 December 20X0 10 years$543,000−$10,000​×12 months6 months​ $26,650
31 December 20X1 10 years$543,000−$10,000​ $53,300
31 December 20X2 10 years$543,000−$10,000​ $53,300

Since the asset was acquired partway through the year, the first year’s depreciation is prorated based on the number of months the asset was in use.

Reducing balance method

The reducing balance method calculates depreciation as a fixed percentage of the asset’s carrying amount (CA) at the beginning of each year. The carrying amount, also called the net book value (NBV), declines each year as depreciation is charged.

This method often better reflects the pattern of economic benefits for many assets, because it charges higher depreciation in the earlier years and lower depreciation in the later years.

The formula is:

Depreciation charge=NBV at the beginning of the year×% of depreciation

In most cases, the depreciation rate under the reducing balance method will be provided. If it is not given, it can be calculated using:

% of depreciation charge=1−nCostResidual value​​

where n = useful life

Like the straight-line method, the reducing balance method also applies the mid-year acquisition rule, meaning depreciation may need to be prorated based on when the asset was purchased.

Illustration: reducing balance method

Assume an entity acquires a factory plant at a cost of $100,000 on 1 January 20X0. The annual depreciation rate is 10%. The annual depreciation at the end of each year will be:

Year-end NBV at year beginning (A) Depreciation charge (10% of NBV) (B = 10% x A) NBV at year end (C = A - B)
31 Dec. 20X0 $100,000 $10,000 $90,000
31 Dec. 20X1 $90,000 $9,000 $81,000
31 Dec. 20X2 $81,000 $8,100 $72,900

Choosing between the two methods depends on how an asset’s economic benefits are used up. Straight-line suits assets whose benefits are consumed evenly over time, such as buildings and fixtures. Reducing balance suits assets that generate more benefit in their early years or lose value quickly, such as vehicles and IT equipment. The method chosen should reflect the pattern in which the asset’s benefits are expected to be consumed.

Changes in estimated useful life and residual value

Depreciation under both methods depends on an asset’s useful life and residual value. Since these are management estimates, they can change over time as circumstances change or new information becomes available.

When the useful life or residual value changes, the depreciation charge will also change. The revised charge is based on the carrying amount of the asset at the date of the change, spread over the remaining useful life.

So, where the straight line method is being used, the formula becomes:

Depreciation charge=Remaining useful lifeCarrying amount at the date of change−Residual value​

Illustration: changes in useful life

D&D Ltd acquired a factory plant for $100,000 on 1 January 20X0, with an estimated residual value of zero, and depreciated it over a useful life of 10 years. On 31 December 20X4, the useful life was revised to 13 years in total (so 8 years remain).

Follow these steps when there are changes in estimated useful life:

  1. Calculate the original annual depreciation.
  2. Determine the number of years of useful life already used as at the date of the change.
  3. Compute the accumulated depreciation and use it to find the carrying amount at the date of the change.
  4. Determine the remaining useful life from the date of the change.
  5. Compute the revised annual depreciation using the carrying amount and the remaining useful life.

Example: applying the steps

  • Step 1: annual depreciation = ($100,000 - $0) / 10 years = $10,000 a year.
  • Step 2: by 31 December 20X4, the asset has been used for 5 years (20X0 to 20X4).
  • Step 3: accumulated depreciation = $10,000 x 5 years = $50,000, so the carrying amount = $100,000 - $50,000 = $50,000.
  • Step 4: a total useful life of 13 years, less the 5 years already used, leaves 8 years remaining.
  • Step 5: revised annual depreciation = ($50,000 - $0) / 8 years = $6,250 a year, starting 1 January 20X5.

Depreciation already charged up to 31 December 20X4 isn’t adjusted - changes in estimates are applied prospectively, affecting only the current and future periods.

If the residual value were also revised to $2,000 on 31 December 20X4, the revised charge would instead be ($50,000 - $2,000) / 8 years = $6,000 a year.

Answer: revised annual depreciation = $6,250 a year (or $6,000 a year if the residual value is also revised to $2,000).

Journal entries for tangible non-current assets

Three key ledger accounts are used:

  • Non-current asset account
  • Depreciation expense account
  • Accumulated depreciation account

Acquisition of asset: When a non-current asset is purchased

Debit: Non-current asset
Credit: Cash or payables

The balance in the asset account remains at cost until the asset is disposed of or fully utilised.

Recording depreciation: At year-end, depreciation is charged as:

Debit: Depreciation expense
Credit: Accumulated depreciation

The depreciation expense reduces profit, while accumulated depreciation offsets the asset’s cost in the statement of financial position.

Illustration: journal entries for tangible non-current assets

D&D Ltd acquired a factory plant for $100,000 on 1 January 20X0 with an estimated residual value of zero and depreciated it over its useful life of 5 years.

Required: Present the accounting entries of how the transaction will be accounted for, as well as extracts in the statement of profit or loss and statement of financial position.

Suggested solution:

The solutions are presented in T-account form instead of the general journal entries only.

Upon purchase of the factory plant on 1 January 20X0:

Ledger entries showing the purchase of a factory plant with cash for 100,000.
Factory plant and cash ledger entries
Achievable

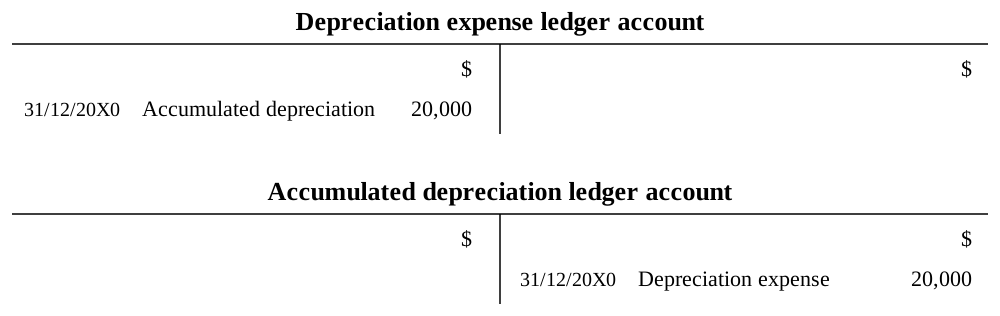
At the end of year 1 (i.e., 31 December 20X0) depreciation charge (($100,000 - $0) / 5 years = $20,000) is posted as:

T-accounts on 31/12/20X0: depreciation expense debited with accumulated depreciation of 20,000; accumulated depreciation credited with depreciation expense of 20,000.
Depreciation expense and accumulated depreciation ledger accounts
Achievable

At year-end, the depreciation expense is transferred to the statement of profit or loss. Meanwhile, accumulated depreciation is deducted from the asset’s cost to show its net book value.

Depreciation is recorded annually through the depreciation expense and accumulated depreciation accounts. The yearly charge is transferred to the statement of profit or loss, while the accumulated depreciation balance is carried forward and increased by each new year’s charge. See below.

Ledger showing annual depreciation of 20,000 transferred to profit or loss each year.
Depreciation expense ledger over five years
Achievable
Ledger showing accumulated depreciation increasing annually to 100,000.
Accumulated depreciation ledger over five years
Achievable

As shown in the accumulated depreciation account, at any point in time, the carrying amount of the non-current asset is the original cost minus accumulated depreciation.

Statement of profit or loss (extract): depreciation of $20,000 is charged in profit or loss in each of years 1 to 5.

Statement of financial position (extract)

$
Year 1: 31/12/20X0 Factory plant ($100,000 - $20,000) 80,000
Year 2: 31/12/20X1 Factory plant ($100,000 - $40,000) 60,000
Year 3: 31/12/20X2 Factory plant ($100,000 - $60,000) 40,000
Year 4: 31/12/20X3 Factory plant ($100,000 - $80,000) 20,000
Year 5: 31/12/20X4 Factory plant ($100,000 - $100,000) 0

The statement of financial position extract shows how depreciation reduces the carrying amount over the years. With no residual value, the asset’s carrying amount is zero at the end of year 5.

Depreciation basics

  • Depreciation: systematic allocation of an asset’s depreciable amount over its useful life (not a cash expense, just an accounting allocation)
  • Depreciable amount = cost (or revalued amount) − residual value
  • Useful life and residual value are management estimates, affected by wear, technology, usage, and economic conditions

Straight-line method

  • Formula: Depreciation charge=Useful lifeCost−Residual value​
  • Produces a constant annual charge; carrying amount (NBV) = cost − accumulated depreciation, declining evenly
  • Can be expressed as a percentage: check whether rate applies to cost or to depreciable amount (if unstated and residual value exists, apply to depreciable amount)
  • Mid-year acquisitions: depreciation may be prorated by months in use or charged in full, per company policy

Reducing balance method

  • Formula: Depreciation charge=NBV at year start×%
  • Charges more depreciation early, less later — fits assets losing value/usefulness quickly (vehicles, IT equipment)
  • If rate not given: %=1−nCostResidual value​​, where n = useful life
  • Straight-line better suits assets with even benefit consumption (buildings, fixtures); method choice should match the asset’s actual usage pattern

Changes in useful life/residual value

  • Estimates can be revised; changes applied prospectively (past depreciation not restated)
  • Steps: find original annual charge → years already depreciated → accumulated depreciation & current carrying amount → remaining useful life → revised charge
  • Revised formula: Depreciation charge=Remaining useful lifeCarrying amount at change date−Residual value​

Recording depreciation in the ledger

  • Three key accounts: non-current asset (stays at cost), depreciation expense, accumulated depreciation
  • Acquisition: Dr Non-current asset / Cr Cash or Payables
  • Annual charge: Dr Depreciation expense / Cr Accumulated depreciation
  • Depreciation expense is transferred to profit or loss each period; accumulated depreciation balance grows each year and is deducted from asset cost to find carrying amount on the statement of financial position

Sign up for free to take 13 quiz questions on this topic

Previous
Next  | 4.3.3 Disposal of tangible non-current asset
All rights reserved ©2016 - 2026 Achievable, Inc.

Depreciation

This chapter introduces depreciation and explains why it matters in financial reporting. You’ll see how depreciation is recorded in the general ledger, how it affects both the statement of profit or loss and the statement of financial position, and how accumulated depreciation builds up over time.

Learning objectives

By the end of this chapter, you should be able to:

  • Explain the purpose of depreciation.
  • Calculate the charge for depreciation using straight-line and diminishing balance (reducing-balance) methods.
  • Identify the circumstances where different methods of depreciation would be appropriate.
  • Illustrate how the depreciation charge and accumulated depreciation are recorded in the general ledger accounts.
  • Calculate the adjustments to depreciation necessary if changes are made in the estimated useful life and/or residual value of a tangible non-current asset.
  • Record depreciation in the statement of profit or loss and statement of financial position.

Definition of key terms

As covered in the previous chapter, the full cost of a non-current asset is not expensed in the year of acquisition. Instead, the portion of the asset’s economic benefits that is consumed each period is charged to profit or loss as depreciation.

Definitions
Depreciation
The systematic allocation of the depreciable amount of an asset over its useful life.
Depreciable amount
The cost of an asset or its revalued amount (when revalued) minus its residual value.
Residual value
The estimated amount the entity would currently obtain from disposing of the asset, after deducting the estimated costs of disposal, if the asset were already of the age and in the condition expected at the end of its useful life.
Useful life
The period over which an asset is expected to be used by the entity. Physical wear and tear, technological advancements, usage patterns, and economic conditions are factors that need to be considered before estimating the useful life of an asset.

Methods of depreciation

There are several methods of depreciation. However, for the purposes of the syllabus, we will focus on:

  • Straight line method
  • Reducing balance method

Straight line method

This is the simplest and most commonly used method. Under the straight-line method, the asset’s depreciable amount is spread evenly over its useful life, so the annual depreciation expense is constant.

The formula is:

Depreciation charge=Useful lifeCost of asset−Residual value​

Under this method, except where the asset is being revalued (covered later, in Revaluation of tangible non-current asset), the annual depreciation charge will be the same each year.

Illustration: straight line method

Assume Gyabaku Ltd acquired the machine for $543,000 on 1 January 20X0. Gyabaku Ltd must estimate the machine’s useful life (the period over which it will be used in operations); organisations typically specify useful lives for each asset class in their accounting policies. Its estimated useful life is 10 years with a residual value of $10,000.

The depreciable amount is the cost minus the residual value: $543,000 - $10,000 = $533,000.

The annual charge is:

10 years$543,000−$10,000​=$53,300 per year

Each year, the carrying amount (also called net book value) falls by the $53,300 depreciation charge: from $543,000 at acquisition to $489,700 at the end of 20X0, $436,400 at the end of 20X1, and $383,100 at the end of 20X2.

Note: Carrying amount (net book value) = cost less accumulated depreciation. Equivalently, each year’s closing carrying amount is the opening carrying amount minus that year’s charge.

Straight line method: depreciation in percentage

Because the annual depreciation charge under the straight-line method is constant, it can also be expressed as a percentage. Check what the percentage is stated on:

  • On cost: multiply the cost by the percentage. Using the example above, the charge of $53,300 is approximately 9.8% on cost ($53,300/$543,000, rounded to one decimal place).
  • On the depreciable amount: multiply cost less residual value by the percentage. The same charge is 10% of the depreciable amount ($53,300/$533,000), which is one year of the 10-year useful life.

If a straight-line rate is given with no base stated and the asset has a residual value, apply it to the depreciable amount, because depreciation allocates the depreciable amount over the useful life. With no residual value, cost and the depreciable amount are the same figure.

Straight-line method: mid-year acquisitions

Sometimes, non-current assets are acquired partway through the year. In that case, the depreciation treatment depends on the firm’s accounting policy - for example:

  • Prorating depreciation based on the period of use, or
  • Charging a full year’s depreciation regardless of the acquisition date.

Illustration: mid-year acquisitions

Assume Gyabaku Ltd acquired the machine at a cost of $543,000 on 1 July 20X0. Its estimated useful life is 10 years with a residual value of $10,000. It is the firm’s policy to depreciate assets from the date of purchase.

The depreciation for the first three years is:

Year-end Computations Depreciation charge
31 December 20X0 10 years$543,000−$10,000​×12 months6 months​ $26,650
31 December 20X1 10 years$543,000−$10,000​ $53,300
31 December 20X2 10 years$543,000−$10,000​ $53,300

Since the asset was acquired partway through the year, the first year’s depreciation is prorated based on the number of months the asset was in use.

Reducing balance method

The reducing balance method calculates depreciation as a fixed percentage of the asset’s carrying amount (CA) at the beginning of each year. The carrying amount, also called the net book value (NBV), declines each year as depreciation is charged.

This method often better reflects the pattern of economic benefits for many assets, because it charges higher depreciation in the earlier years and lower depreciation in the later years.

The formula is:

Depreciation charge=NBV at the beginning of the year×% of depreciation

In most cases, the depreciation rate under the reducing balance method will be provided. If it is not given, it can be calculated using:

% of depreciation charge=1−nCostResidual value​​

where n = useful life

Like the straight-line method, the reducing balance method also applies the mid-year acquisition rule, meaning depreciation may need to be prorated based on when the asset was purchased.

Illustration: reducing balance method

Assume an entity acquires a factory plant at a cost of $100,000 on 1 January 20X0. The annual depreciation rate is 10%. The annual depreciation at the end of each year will be:

Year-end NBV at year beginning (A) Depreciation charge (10% of NBV) (B = 10% x A) NBV at year end (C = A - B)
31 Dec. 20X0 $100,000 $10,000 $90,000
31 Dec. 20X1 $90,000 $9,000 $81,000
31 Dec. 20X2 $81,000 $8,100 $72,900

Choosing between the two methods depends on how an asset’s economic benefits are used up. Straight-line suits assets whose benefits are consumed evenly over time, such as buildings and fixtures. Reducing balance suits assets that generate more benefit in their early years or lose value quickly, such as vehicles and IT equipment. The method chosen should reflect the pattern in which the asset’s benefits are expected to be consumed.

Changes in estimated useful life and residual value

Depreciation under both methods depends on an asset’s useful life and residual value. Since these are management estimates, they can change over time as circumstances change or new information becomes available.

When the useful life or residual value changes, the depreciation charge will also change. The revised charge is based on the carrying amount of the asset at the date of the change, spread over the remaining useful life.

So, where the straight line method is being used, the formula becomes:

Depreciation charge=Remaining useful lifeCarrying amount at the date of change−Residual value​

Illustration: changes in useful life

D&D Ltd acquired a factory plant for $100,000 on 1 January 20X0, with an estimated residual value of zero, and depreciated it over a useful life of 10 years. On 31 December 20X4, the useful life was revised to 13 years in total (so 8 years remain).

Follow these steps when there are changes in estimated useful life:

  1. Calculate the original annual depreciation.
  2. Determine the number of years of useful life already used as at the date of the change.
  3. Compute the accumulated depreciation and use it to find the carrying amount at the date of the change.
  4. Determine the remaining useful life from the date of the change.
  5. Compute the revised annual depreciation using the carrying amount and the remaining useful life.

Example: applying the steps

  • Step 1: annual depreciation = ($100,000 - $0) / 10 years = $10,000 a year.
  • Step 2: by 31 December 20X4, the asset has been used for 5 years (20X0 to 20X4).
  • Step 3: accumulated depreciation = $10,000 x 5 years = $50,000, so the carrying amount = $100,000 - $50,000 = $50,000.
  • Step 4: a total useful life of 13 years, less the 5 years already used, leaves 8 years remaining.
  • Step 5: revised annual depreciation = ($50,000 - $0) / 8 years = $6,250 a year, starting 1 January 20X5.

Depreciation already charged up to 31 December 20X4 isn’t adjusted - changes in estimates are applied prospectively, affecting only the current and future periods.

If the residual value were also revised to $2,000 on 31 December 20X4, the revised charge would instead be ($50,000 - $2,000) / 8 years = $6,000 a year.

Answer: revised annual depreciation = $6,250 a year (or $6,000 a year if the residual value is also revised to $2,000).

Journal entries for tangible non-current assets

Three key ledger accounts are used:

  • Non-current asset account
  • Depreciation expense account
  • Accumulated depreciation account

Acquisition of asset: When a non-current asset is purchased

Debit: Non-current asset
Credit: Cash or payables

The balance in the asset account remains at cost until the asset is disposed of or fully utilised.

Recording depreciation: At year-end, depreciation is charged as:

Debit: Depreciation expense
Credit: Accumulated depreciation

The depreciation expense reduces profit, while accumulated depreciation offsets the asset’s cost in the statement of financial position.

Illustration: journal entries for tangible non-current assets

D&D Ltd acquired a factory plant for $100,000 on 1 January 20X0 with an estimated residual value of zero and depreciated it over its useful life of 5 years.

Required: Present the accounting entries of how the transaction will be accounted for, as well as extracts in the statement of profit or loss and statement of financial position.

Suggested solution:

The solutions are presented in T-account form instead of the general journal entries only.

Upon purchase of the factory plant on 1 January 20X0:

At the end of year 1 (i.e., 31 December 20X0) depreciation charge (($100,000 - $0) / 5 years = $20,000) is posted as:

At year-end, the depreciation expense is transferred to the statement of profit or loss. Meanwhile, accumulated depreciation is deducted from the asset’s cost to show its net book value.

Depreciation is recorded annually through the depreciation expense and accumulated depreciation accounts. The yearly charge is transferred to the statement of profit or loss, while the accumulated depreciation balance is carried forward and increased by each new year’s charge. See below.

As shown in the accumulated depreciation account, at any point in time, the carrying amount of the non-current asset is the original cost minus accumulated depreciation.

Statement of profit or loss (extract): depreciation of $20,000 is charged in profit or loss in each of years 1 to 5.

Statement of financial position (extract)

$
Year 1: 31/12/20X0 Factory plant ($100,000 - $20,000) 80,000
Year 2: 31/12/20X1 Factory plant ($100,000 - $40,000) 60,000
Year 3: 31/12/20X2 Factory plant ($100,000 - $60,000) 40,000
Year 4: 31/12/20X3 Factory plant ($100,000 - $80,000) 20,000
Year 5: 31/12/20X4 Factory plant ($100,000 - $100,000) 0

The statement of financial position extract shows how depreciation reduces the carrying amount over the years. With no residual value, the asset’s carrying amount is zero at the end of year 5.

Key points

Depreciation basics

  • Depreciation: systematic allocation of an asset’s depreciable amount over its useful life (not a cash expense, just an accounting allocation)
  • Depreciable amount = cost (or revalued amount) − residual value
  • Useful life and residual value are management estimates, affected by wear, technology, usage, and economic conditions

Straight-line method

  • Formula: Depreciation charge=Useful lifeCost−Residual value​
  • Produces a constant annual charge; carrying amount (NBV) = cost − accumulated depreciation, declining evenly
  • Can be expressed as a percentage: check whether rate applies to cost or to depreciable amount (if unstated and residual value exists, apply to depreciable amount)
  • Mid-year acquisitions: depreciation may be prorated by months in use or charged in full, per company policy

Reducing balance method

  • Formula: Depreciation charge=NBV at year start×%
  • Charges more depreciation early, less later — fits assets losing value/usefulness quickly (vehicles, IT equipment)
  • If rate not given: %=1−nCostResidual value​​, where n = useful life
  • Straight-line better suits assets with even benefit consumption (buildings, fixtures); method choice should match the asset’s actual usage pattern

Changes in useful life/residual value

  • Estimates can be revised; changes applied prospectively (past depreciation not restated)
  • Steps: find original annual charge → years already depreciated → accumulated depreciation & current carrying amount → remaining useful life → revised charge
  • Revised formula: Depreciation charge=Remaining useful lifeCarrying amount at change date−Residual value​

Recording depreciation in the ledger

  • Three key accounts: non-current asset (stays at cost), depreciation expense, accumulated depreciation
  • Acquisition: Dr Non-current asset / Cr Cash or Payables
  • Annual charge: Dr Depreciation expense / Cr Accumulated depreciation
  • Depreciation expense is transferred to profit or loss each period; accumulated depreciation balance grows each year and is deducted from asset cost to find carrying amount on the statement of financial position

More from Accounting for non-current asset

  • Accounting for tangible non-current assets
  • Disposal of tangible non-current asset
  • Revaluation of tangible non-current asset
  • Disclosure of tangible non-current asset
  • Intangible non-current asset and amortisation