


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
ACCA Financial Accounting
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. The context and purpose of financial reporting
2. Accounting principles, concepts and qualitative characteristics
3. Double-entry bookkeeping and accounting systems
4. Recording transactions and events
5. Reconciliations
6. Preparing trial balance
7. Preparing financial statements
7.1 Statements of profit or loss and financial position
7.2 Statement of cash flow
7.3 Incomplete records
7.4 Events after the reporting period
7.5 Disclosure-notes
8. Preparing basic consolidated financial statements
9. Interpretation of financial statements
Wrapping up
Achievable logoAchievable logo
7.3 Incomplete records
Achievable ACCA Financial Accounting
7. Preparing financial statements
Our ACCA course is currently in development and is a work-in-progress.

Incomplete records

11 min read
Font
Discuss
Share
Feedback

This chapter introduces techniques for identifying missing accounting information when records are incomplete, enabling you to prepare financial statements.

Learning objective

By the end of this chapter, you should be able to:

  • Apply techniques used in incomplete record situations:
    • Use of the accounting equation
    • Use of general ledger accounts to calculate missing figures
    • Use of cash and/or bank summaries
    • Use of profit percentages to calculate missing figures.
Definitions
Incomplete records
A situation where a business does not maintain a full double-entry bookkeeping system, resulting in missing or incomplete accounting information.

This is common in small businesses that only keep basic records such as cash books, bank statements, or invoices.

Many small businesses, especially sole traders, don’t maintain complete accounting records. They may only record cash receipts and payments and keep invoices on file. However, for tax purposes, loan applications, or business analysis, they still need financial statements.

In these cases, accountants use specific techniques to reconstruct missing information and prepare complete financial statements from the records that are available.

Incomplete records techniques

The main challenge is preparing accurate financial statements (statement of financial position and statement of profit or loss) or determining a particular ledger balance from limited information. The sections below walk through each of the four techniques listed in the learning objective above.

Use of the accounting equation

The accounting equation is a foundation for solving incomplete records problems. Refer to the earlier chapter on the accounting equation.

When you know the opening and closing net assets (Assets - Liabilities), the drawings made during the period, and any capital introduced, you can calculate profit.

Illustration: Calculating profit using the accounting equation

Sarah runs a small retail shop. She doesn’t keep proper books but has prepared statements of her assets and liabilities:

At January 1, 2024:

  • Inventory: $15,000
  • Trade receivables: $8,000
  • Cash: $2,000
  • Equipment (net): $20,000
  • Trade payables: $6,000
  • Bank loan: $10,000

At December 31, 2024:

  • Inventory: $18,000
  • Trade receivables: $10,000
  • Cash: $3,500
  • Equipment (net): $18,000
  • Trade payables: $7,500
  • Bank loan: $8,000

Sarah withdrew $25,000 during the year for personal use.

Required: Calculate Sarah’s profit for the year ended December 31, 2024.

Step 1: Calculate opening capital (net asset) - find the difference between the total assets and total liabilities as at January 1, 2024.

(spoiler)

Opening assets = $15,000 + $8,000 + $2,000 + $20,000 = $45,000

Opening liabilities = $6,000 + $10,000 = $16,000

Opening capital (net asset) = $45,000 - $16,000 = $29,000

Step 2: Calculate closing capital - find the difference between the total assets and total liabilities as at December 31, 2024.

(spoiler)

Closing assets = $18,000 + $10,000 + $3,500 + $18,000 = $49,500

Closing liabilities = $7,500 + $8,000 = $15,500

Closing capital (net asset) = $49,500 - $15,500 = $34,000

Step 3: Calculate profit - use the accounting equation

(spoiler)

Profit = closing net assets − opening net assets + drawings − capital introduced

Sarah introduced no new capital during the year, so that term is zero.

Profit = $34,000 - $29,000 + $25,000 - $0

Profit = $30,000

Answer: Sarah made a profit of $30,000 for the year.

When to use this technique

The accounting equation method is most useful when:

  • You have complete statements of assets and liabilities at two points in time
  • Drawings and any capital introduced are known
  • No detailed income and expense information is available
  • You need to calculate the total profit for the period

Use of general ledger accounts

When some information is available but certain figures are missing, you can reconstruct ledger accounts (T-accounts) to calculate the unknown amounts.

Every ledger account follows the format: Opening balance + increases - decreases = closing balance

If you know three of these four elements, you can calculate the fourth (the missing figure).

Illustration 1: Calculating credit sales

John’s business has the following information for 2024:

  • Trade receivables at January 1: $12,000
  • Trade receivables at December 31: $15,000
  • Cash received from customers: $85,000
  • Irrecoverable debts written off: $2,000
  • Discounts allowed to customers: $1,500

Required: Calculate total credit sales for the year.

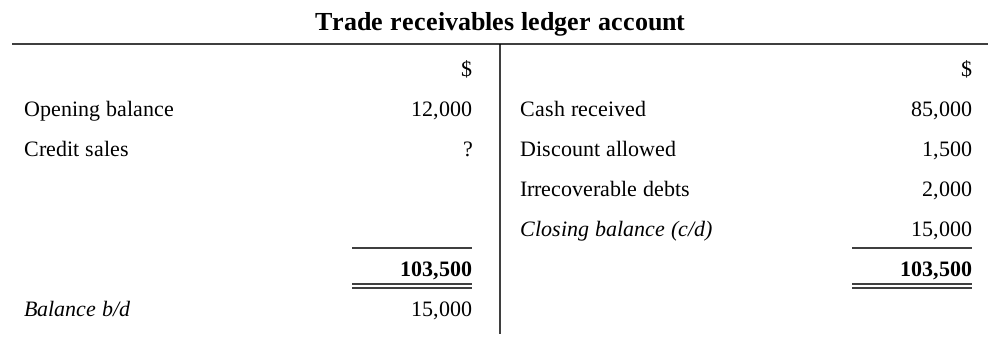
Trade receivables ledger account: opening balance of 12,000 and credit sales still to find on the debit side; cash received of 85,000, discount allowed of 1,500, irrecoverable debts of 2,000 and closing balance c/d of 15,000 on the credit side; totals of 103,500; balance b/d of 15,000.
Trade receivables ledger account
Achievable
(spoiler)

Calculate the balancing figure:

Opening balance + credit sales = cash + discounts + irrecoverable debts + closing balance

$12,000 + credit sales = $85,000 + $1,500 + $2,000 + $15,000

$12,000 + credit sales = $103,500

Credit sales = $103,500 - $12,000

Credit sales = $91,500

Answer: Credit sales for the year were $91,500.

IFRS 15 insight: a settlement discount a customer takes reduces revenue - it is not recorded as an expense. A trade discount is never recorded at all.

Illustration 2: Calculating credit purchases

Maria’s business has the following information regarding suppliers:

  • Trade payables at January 1: $8,500
  • Trade payables at December 31: $9,800
  • Payments to suppliers during the year: $76,000
  • Discounts received from suppliers: $1,200
  • Returns to suppliers: $500

Required: Calculate total credit purchases for the year.

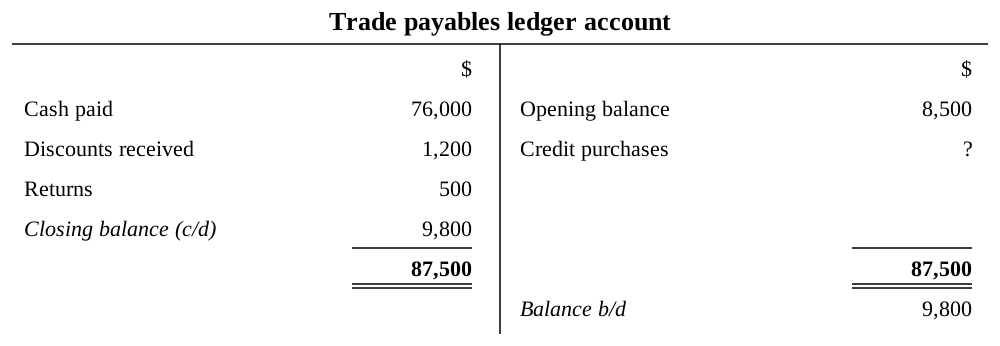
Trade payables ledger account: cash paid of 76,000, discounts received of 1,200, returns of 500 and closing balance c/d of 9,800 on the debit side; opening balance of 8,500 and credit purchases still to find on the credit side; totals of 87,500; balance b/d of 9,800.
Trade payables ledger account
Achievable
(spoiler)

Calculate the balancing figure:

Cash paid + discounts + returns + closing balance = opening balance + credit purchases

$76,000 + $1,200 + $500 + $9,800 = $8,500 + credit purchases

$87,500 = $8,500 + credit purchases

Credit purchases = $87,500 - $8,500

Credit purchases = $79,000

Answer: Credit purchases for the year were $79,000.

Use of cash and/or bank summaries

Many small businesses only keep a record of cash movements. You can summarise these receipts and payments in a single cash or bank account and use it the same way as any other ledger account: if you know three of the four elements (opening balance, receipts, payments, closing balance), you can solve for the missing one - often drawings, cash stolen, or cash takings banked.

Illustration: Calculating drawings from a cash summary

A trader keeps no formal cash book, but the following is known about cash held on the premises during the year:

  • Cash in hand at January 1: $500
  • Cash takings during the year: $42,000
  • Cash paid for shop expenses: $6,500
  • Cash banked during the year: $33,000
  • Cash in hand at December 31: $800

Required: Calculate the drawings taken from cash takings during the year.

(spoiler)

Opening cash + cash takings − cash expenses − cash banked − closing cash = drawings

$500 + $42,000 − $6,500 − $33,000 − $800 = drawings

Drawings = $2,200

Answer: Drawings for the year were $2,200.

Use of profit percentages (margins and mark-ups)

Many businesses work with standard profit margins or mark-ups. When these percentages are known, you can calculate missing figures such as sales, purchases, or cost of goods sold.

Definitions
Mark-up
The profit expressed as a percentage of cost.
Margin (gross profit margin)
The profit expressed as a percentage of the selling price or sales.

Mark-up %=Cost of salesProfit​×100

Margin %=SalesProfit​×100

Watch out: a mark-up percentage applies to cost, not to sales. Applying it directly to the sales figure overstates profit - convert it to a margin first if you need a percentage of sales.

Sometimes you may need to convert a mark-up to a margin, or a margin to a mark-up, before you can calculate the missing figure.

From mark-up to margin:

Margin %=100%+Mark-up %Mark-up %​×100

For example, a 25% mark-up is a 20% margin: 25% ÷ (100% + 25%) × 100 = 0.2 × 100 = 20, so the margin is 20%.

From margin to mark-up:

Mark-up %=100%−Margin %Margin %​×100

For example, a 20% margin is a 25% mark-up: 20% ÷ (100% − 20%) × 100 = 0.25 × 100 = 25, so the mark-up is 25%.

Illustration: Using mark-up to calculate sales

A retailer has the following information:

  • Opening inventory: $15,000
  • Purchases: $95,000
  • Closing inventory: $18,000
  • The business applies a mark-up of 40% on cost

Required: Calculate the sales revenue.

(1) Calculate cost of sales:

(spoiler)

Cost of sales = opening inventory + purchases - closing inventory

Cost of sales = $15,000 + $95,000 - $18,000

Cost of sales = $92,000

(2) Calculate the profit since mark-up is on cost

(spoiler)

With a 40% mark-up on cost: Profit = 40% x $92,000 = $36,800

(3) Calculate sales:

(spoiler)

Gross profit = sales - cost of sales

Sales = profit + cost of sales

Sales = $36,800 + $92,000 = $128,800

Answer: Sales revenue for the year was $128,800.

Illustration: Using margin to calculate purchases

A business has the following information:

  • Sales for the year: $200,000
  • Gross profit margin: 30% on sales
  • Opening inventory: $25,000
  • Closing inventory: $28,000

Required: Calculate purchases for the year.

Step 1: Calculate gross profit

(spoiler)

Gross profit = 30% × $200,000

Gross profit = $60,000

Step 2: Calculate cost of sales

(spoiler)

Cost of sales = sales - gross profit

Cost of sales = $200,000 - $60,000

Cost of sales = $140,000

Step 3: Calculate purchases

(spoiler)

Using the cost of sales formula:

Cost of sales = opening inventory + purchases - closing inventory

$140,000 = $25,000 + purchases - $28,000

$140,000 = purchases - $3,000

Purchases = $140,000 + $3,000

Purchases = $143,000

Answer: Purchases for the year were $143,000.

Illustration: Calculating missing inventory

A fire destroyed part of the inventory in a warehouse on October 15, 2024. For insurance purposes, the business needs to determine the value of lost inventory. Available information:

  • Inventory at January 1, 2024: $42,000
  • Inventory remaining after the fire on October 15, 2024: $30,000
  • Purchases from January to October 15: $300,000
  • Sales from January to October 15: $380,000
  • The business consistently achieves a margin of 25%.

Required: Calculate the estimated value of inventory destroyed.

Step 1: Calculate gross profit

(spoiler)

Gross profit = 25% × $380,000

Gross profit = $95,000

Step 2: Calculate cost of sales

(spoiler)

Cost of sales = sales - gross profit

Cost of sales = $380,000 - $95,000

Cost of sales = $285,000

Step 3: Calculate closing inventory

(spoiler)

Using the cost of sales formula:

Cost of sales = opening inventory + purchases - closing inventory

$285,000 = $42,000 + $300,000 - closing inventory

Closing inventory = $42,000 + $300,000 - $285,000

Closing inventory = $57,000

Step 4: Calculate the inventory lost

(spoiler)

We expected that the closing inventory should be $57,000. However, the question indicated that the inventory after the fire was $30,000. Hence,

Inventory lost = $57,000 - $30,000 = $27,000

Answer: Inventory worth $27,000 was destroyed in the fire. This amount would be the basis for the insurance claim (subject to policy terms).

Incomplete records overview

  • Occurs when a business lacks full double-entry records (common for sole traders/small businesses)
  • Financial statements still needed for tax, loans, analysis
  • Four main techniques: accounting equation, ledger accounts, cash/bank summaries, profit percentages

Accounting equation method

  • Formula: Profit = closing net assets − opening net assets + drawings − capital introduced
  • Net assets = total assets − total liabilities (calculated at both start and end of period)
  • Best used when only opening/closing asset-liability positions and drawings/capital figures are known (no detailed income/expense data)

Reconstructing ledger accounts

  • Core logic: opening balance + increases − decreases = closing balance; solve for the unknown when 3 of 4 elements are known
  • Trade receivables account: opening balance + credit sales = cash received + discounts allowed + irrecoverable debts + closing balance
  • Trade payables account: cash paid + discounts received + returns + closing balance = opening balance + credit purchases
  • IFRS 15 note: settlement discounts reduce revenue (not an expense); trade discounts are never recorded

Cash/bank summaries

  • Same balancing logic applied to cash or bank accounts
  • Formula: opening cash + receipts − payments − closing cash = missing figure (often drawings, theft, or unbanked takings)
  • Useful when only cash movements are tracked, no formal cash book kept

Profit percentages (margins and mark-ups)

  • Mark-up % = Cost of salesProfit​×100 (profit as % of cost)
  • Margin % = SalesProfit​×100 (profit as % of sales)
  • Conversion formulas:
    • Margin % = 100%+Mark-up %Mark-up %​×100
    • Mark-up % = 100%−Margin %Margin %​×100
  • Caution: never apply a mark-up % directly to sales—convert to margin first
  • Cost of sales formula ties it together: opening inventory + purchases − closing inventory = cost of sales
  • Used to back-calculate sales, purchases, or inventory (e.g., estimating fire/theft losses) when percentage and partial figures are known

Sign up for free to take 12 quiz questions on this topic

Previous
Next  | 7.4 Events after the reporting period
All rights reserved ©2016 - 2026 Achievable, Inc.

Incomplete records

This chapter introduces techniques for identifying missing accounting information when records are incomplete, enabling you to prepare financial statements.

Learning objective

By the end of this chapter, you should be able to:

  • Apply techniques used in incomplete record situations:
    • Use of the accounting equation
    • Use of general ledger accounts to calculate missing figures
    • Use of cash and/or bank summaries
    • Use of profit percentages to calculate missing figures.
Definitions
Incomplete records
A situation where a business does not maintain a full double-entry bookkeeping system, resulting in missing or incomplete accounting information.

This is common in small businesses that only keep basic records such as cash books, bank statements, or invoices.

Many small businesses, especially sole traders, don’t maintain complete accounting records. They may only record cash receipts and payments and keep invoices on file. However, for tax purposes, loan applications, or business analysis, they still need financial statements.

In these cases, accountants use specific techniques to reconstruct missing information and prepare complete financial statements from the records that are available.

Incomplete records techniques

The main challenge is preparing accurate financial statements (statement of financial position and statement of profit or loss) or determining a particular ledger balance from limited information. The sections below walk through each of the four techniques listed in the learning objective above.

Use of the accounting equation

The accounting equation is a foundation for solving incomplete records problems. Refer to the earlier chapter on the accounting equation.

When you know the opening and closing net assets (Assets - Liabilities), the drawings made during the period, and any capital introduced, you can calculate profit.

Illustration: Calculating profit using the accounting equation

Sarah runs a small retail shop. She doesn’t keep proper books but has prepared statements of her assets and liabilities:

At January 1, 2024:

  • Inventory: $15,000
  • Trade receivables: $8,000
  • Cash: $2,000
  • Equipment (net): $20,000
  • Trade payables: $6,000
  • Bank loan: $10,000

At December 31, 2024:

  • Inventory: $18,000
  • Trade receivables: $10,000
  • Cash: $3,500
  • Equipment (net): $18,000
  • Trade payables: $7,500
  • Bank loan: $8,000

Sarah withdrew $25,000 during the year for personal use.

Required: Calculate Sarah’s profit for the year ended December 31, 2024.

Step 1: Calculate opening capital (net asset) - find the difference between the total assets and total liabilities as at January 1, 2024.

(spoiler)

Opening assets = $15,000 + $8,000 + $2,000 + $20,000 = $45,000

Opening liabilities = $6,000 + $10,000 = $16,000

Opening capital (net asset) = $45,000 - $16,000 = $29,000

Step 2: Calculate closing capital - find the difference between the total assets and total liabilities as at December 31, 2024.

(spoiler)

Closing assets = $18,000 + $10,000 + $3,500 + $18,000 = $49,500

Closing liabilities = $7,500 + $8,000 = $15,500

Closing capital (net asset) = $49,500 - $15,500 = $34,000

Step 3: Calculate profit - use the accounting equation

(spoiler)

Profit = closing net assets − opening net assets + drawings − capital introduced

Sarah introduced no new capital during the year, so that term is zero.

Profit = $34,000 - $29,000 + $25,000 - $0

Profit = $30,000

Answer: Sarah made a profit of $30,000 for the year.

When to use this technique

The accounting equation method is most useful when:

  • You have complete statements of assets and liabilities at two points in time
  • Drawings and any capital introduced are known
  • No detailed income and expense information is available
  • You need to calculate the total profit for the period

Use of general ledger accounts

When some information is available but certain figures are missing, you can reconstruct ledger accounts (T-accounts) to calculate the unknown amounts.

Every ledger account follows the format: Opening balance + increases - decreases = closing balance

If you know three of these four elements, you can calculate the fourth (the missing figure).

Illustration 1: Calculating credit sales

John’s business has the following information for 2024:

  • Trade receivables at January 1: $12,000
  • Trade receivables at December 31: $15,000
  • Cash received from customers: $85,000
  • Irrecoverable debts written off: $2,000
  • Discounts allowed to customers: $1,500

Required: Calculate total credit sales for the year.

(spoiler)

Calculate the balancing figure:

Opening balance + credit sales = cash + discounts + irrecoverable debts + closing balance

$12,000 + credit sales = $85,000 + $1,500 + $2,000 + $15,000

$12,000 + credit sales = $103,500

Credit sales = $103,500 - $12,000

Credit sales = $91,500

Answer: Credit sales for the year were $91,500.

IFRS 15 insight: a settlement discount a customer takes reduces revenue - it is not recorded as an expense. A trade discount is never recorded at all.

Illustration 2: Calculating credit purchases

Maria’s business has the following information regarding suppliers:

  • Trade payables at January 1: $8,500
  • Trade payables at December 31: $9,800
  • Payments to suppliers during the year: $76,000
  • Discounts received from suppliers: $1,200
  • Returns to suppliers: $500

Required: Calculate total credit purchases for the year.

(spoiler)

Calculate the balancing figure:

Cash paid + discounts + returns + closing balance = opening balance + credit purchases

$76,000 + $1,200 + $500 + $9,800 = $8,500 + credit purchases

$87,500 = $8,500 + credit purchases

Credit purchases = $87,500 - $8,500

Credit purchases = $79,000

Answer: Credit purchases for the year were $79,000.

Use of cash and/or bank summaries

Many small businesses only keep a record of cash movements. You can summarise these receipts and payments in a single cash or bank account and use it the same way as any other ledger account: if you know three of the four elements (opening balance, receipts, payments, closing balance), you can solve for the missing one - often drawings, cash stolen, or cash takings banked.

Illustration: Calculating drawings from a cash summary

A trader keeps no formal cash book, but the following is known about cash held on the premises during the year:

  • Cash in hand at January 1: $500
  • Cash takings during the year: $42,000
  • Cash paid for shop expenses: $6,500
  • Cash banked during the year: $33,000
  • Cash in hand at December 31: $800

Required: Calculate the drawings taken from cash takings during the year.

(spoiler)

Opening cash + cash takings − cash expenses − cash banked − closing cash = drawings

$500 + $42,000 − $6,500 − $33,000 − $800 = drawings

Drawings = $2,200

Answer: Drawings for the year were $2,200.

Use of profit percentages (margins and mark-ups)

Many businesses work with standard profit margins or mark-ups. When these percentages are known, you can calculate missing figures such as sales, purchases, or cost of goods sold.

Definitions
Mark-up
The profit expressed as a percentage of cost.
Margin (gross profit margin)
The profit expressed as a percentage of the selling price or sales.

Mark-up %=Cost of salesProfit​×100

Margin %=SalesProfit​×100

Watch out: a mark-up percentage applies to cost, not to sales. Applying it directly to the sales figure overstates profit - convert it to a margin first if you need a percentage of sales.

Sometimes you may need to convert a mark-up to a margin, or a margin to a mark-up, before you can calculate the missing figure.

From mark-up to margin:

Margin %=100%+Mark-up %Mark-up %​×100

For example, a 25% mark-up is a 20% margin: 25% ÷ (100% + 25%) × 100 = 0.2 × 100 = 20, so the margin is 20%.

From margin to mark-up:

Mark-up %=100%−Margin %Margin %​×100

For example, a 20% margin is a 25% mark-up: 20% ÷ (100% − 20%) × 100 = 0.25 × 100 = 25, so the mark-up is 25%.

Illustration: Using mark-up to calculate sales

A retailer has the following information:

  • Opening inventory: $15,000
  • Purchases: $95,000
  • Closing inventory: $18,000
  • The business applies a mark-up of 40% on cost

Required: Calculate the sales revenue.

(1) Calculate cost of sales:

(spoiler)

Cost of sales = opening inventory + purchases - closing inventory

Cost of sales = $15,000 + $95,000 - $18,000

Cost of sales = $92,000

(2) Calculate the profit since mark-up is on cost

(spoiler)

With a 40% mark-up on cost: Profit = 40% x $92,000 = $36,800

(3) Calculate sales:

(spoiler)

Gross profit = sales - cost of sales

Sales = profit + cost of sales

Sales = $36,800 + $92,000 = $128,800

Answer: Sales revenue for the year was $128,800.

Illustration: Using margin to calculate purchases

A business has the following information:

  • Sales for the year: $200,000
  • Gross profit margin: 30% on sales
  • Opening inventory: $25,000
  • Closing inventory: $28,000

Required: Calculate purchases for the year.

Step 1: Calculate gross profit

(spoiler)

Gross profit = 30% × $200,000

Gross profit = $60,000

Step 2: Calculate cost of sales

(spoiler)

Cost of sales = sales - gross profit

Cost of sales = $200,000 - $60,000

Cost of sales = $140,000

Step 3: Calculate purchases

(spoiler)

Using the cost of sales formula:

Cost of sales = opening inventory + purchases - closing inventory

$140,000 = $25,000 + purchases - $28,000

$140,000 = purchases - $3,000

Purchases = $140,000 + $3,000

Purchases = $143,000

Answer: Purchases for the year were $143,000.

Illustration: Calculating missing inventory

A fire destroyed part of the inventory in a warehouse on October 15, 2024. For insurance purposes, the business needs to determine the value of lost inventory. Available information:

  • Inventory at January 1, 2024: $42,000
  • Inventory remaining after the fire on October 15, 2024: $30,000
  • Purchases from January to October 15: $300,000
  • Sales from January to October 15: $380,000
  • The business consistently achieves a margin of 25%.

Required: Calculate the estimated value of inventory destroyed.

Step 1: Calculate gross profit

(spoiler)

Gross profit = 25% × $380,000

Gross profit = $95,000

Step 2: Calculate cost of sales

(spoiler)

Cost of sales = sales - gross profit

Cost of sales = $380,000 - $95,000

Cost of sales = $285,000

Step 3: Calculate closing inventory

(spoiler)

Using the cost of sales formula:

Cost of sales = opening inventory + purchases - closing inventory

$285,000 = $42,000 + $300,000 - closing inventory

Closing inventory = $42,000 + $300,000 - $285,000

Closing inventory = $57,000

Step 4: Calculate the inventory lost

(spoiler)

We expected that the closing inventory should be $57,000. However, the question indicated that the inventory after the fire was $30,000. Hence,

Inventory lost = $57,000 - $30,000 = $27,000

Answer: Inventory worth $27,000 was destroyed in the fire. This amount would be the basis for the insurance claim (subject to policy terms).

Key points

Incomplete records overview

  • Occurs when a business lacks full double-entry records (common for sole traders/small businesses)
  • Financial statements still needed for tax, loans, analysis
  • Four main techniques: accounting equation, ledger accounts, cash/bank summaries, profit percentages

Accounting equation method

  • Formula: Profit = closing net assets − opening net assets + drawings − capital introduced
  • Net assets = total assets − total liabilities (calculated at both start and end of period)
  • Best used when only opening/closing asset-liability positions and drawings/capital figures are known (no detailed income/expense data)

Reconstructing ledger accounts

  • Core logic: opening balance + increases − decreases = closing balance; solve for the unknown when 3 of 4 elements are known
  • Trade receivables account: opening balance + credit sales = cash received + discounts allowed + irrecoverable debts + closing balance
  • Trade payables account: cash paid + discounts received + returns + closing balance = opening balance + credit purchases
  • IFRS 15 note: settlement discounts reduce revenue (not an expense); trade discounts are never recorded

Cash/bank summaries

  • Same balancing logic applied to cash or bank accounts
  • Formula: opening cash + receipts − payments − closing cash = missing figure (often drawings, theft, or unbanked takings)
  • Useful when only cash movements are tracked, no formal cash book kept

Profit percentages (margins and mark-ups)

  • Mark-up % = Cost of salesProfit​×100 (profit as % of cost)
  • Margin % = SalesProfit​×100 (profit as % of sales)
  • Conversion formulas:
    • Margin % = 100%+Mark-up %Mark-up %​×100
    • Mark-up % = 100%−Margin %Margin %​×100
  • Caution: never apply a mark-up % directly to sales—convert to margin first
  • Cost of sales formula ties it together: opening inventory + purchases − closing inventory = cost of sales
  • Used to back-calculate sales, purchases, or inventory (e.g., estimating fire/theft losses) when percentage and partial figures are known

More from Preparing financial statements

  • Events after the reporting period
  • Disclosure-notes