





The general ledger and double-entry bookkeeping
Earlier, we noted that financial statement transactions originate from source documents and are first recorded in the books of prime entry (day books). These transactions are then posted to general ledger accounts through journal entries using double-entry bookkeeping. This chapter looks at the main types of ledger accounts and how to record transactions in them using journal entries.
Learning objectives
By the end of this lesson, you should be able to:
- Describe the main types of general ledger accounts, including their nature and function.
- Describe how financial data is initially recorded in the accounting system.
- Explain the use of journal entries and how journal entries are processed to general ledger accounts.
- Identify correct journal entries from a given narrative.
- Illustrate how to balance and close the general ledger accounts at the year-end.
The general ledger
For example, credit sales from the sales daybook are posted to both the sales ledger account and the receivables ledger account within the general ledger.
Every ledger account has two sides:
- Debit (Dr)
- Credit (Cr)
In a manual accounting system, ledger accounts are usually presented in a T-form (a T-account) as shown below.
Every financial transaction follows the duality concept - each transaction has two equal and opposite effects. One account is debited, and another is credited, following the rules of double-entry bookkeeping. Below are examples of some general ledger accounts and the related elements of the financial statements.
| Ledger account | Related element of the financial statement |
|---|---|
| Sales | Income |
| Trade receivables | Asset |
| Purchases | Expense |
| Trade payables | Liability |
| Cash and bank balance | Asset |
| Bank overdraft | Liability |
| Rent | Expense |
| Office building | Asset |
| Long-term loans | Liability |
| Ordinary shares | Equity |
| Inventories | Asset |
The narratives below use payables, the general name for amounts a business owes its suppliers. Amounts owed to suppliers of goods bought for resale are its trade payables.
Double-entry bookkeeping
Double-entry bookkeeping states that every transaction affects at least two ledger accounts: one debit and one credit, always with equal amounts. Each ledger account belongs to one of the five financial statement elements: assets, liabilities, equity, expenses, or income.
This principle is the foundation for all postings in the general ledger. It’s summarised in the table below.
| Assets & expenses related ledger | Income, liability and equity related ledger | |
|---|---|---|
| A debit entry | Increases the balance | Decreases the balance |
| A credit entry | Decreases the balance | Increases the balance |
Because a debit entry increases the balance of assets and expenses, these accounts are said to have a debit balance. In contrast, income, liability, and equity accounts are said to have a credit balance. These debit and credit rules are what keep the accounting equation in balance, as you’ll see in the next chapter, The accounting equation.
Passing journal entries
Passing journal entries means recording a transaction by debiting one ledger account and crediting another, following the double-entry principle. Routine transactions - such as credit sales or cash receipts - are posted straight from the day books. The journal itself is used for non-routine entries, like year-end adjustments, corrections of errors, and credit purchases of non-current assets. Exam questions commonly show any double entry in journal format (Dr account / Cr account), since it makes clear at a glance which accounts are debited and credited.
Format of a general journal is shown below
| Date | Description | Debit ($) | Credit ($) |
|---|---|---|---|
| GL account to be debited | xxx | ||
| GL account to be credited | xxx |
Step-by-step illustration
Use the steps below to turn a narrative into a journal entry.
Steps
- Identify all the ledger accounts involved in the narrative - this ensures the duality principle.
- Determine the effect on each ledger account - will it increase, decrease, or will one increase while the other decreases?
- Relate each ledger account to a financial statement element (asset, liability, equity, income, or expense).
- Apply the debit/credit rules from the table above.
Let’s demonstrate these guidelines using these narratives.
Narrative 1: Kofi sold goods worth $ 5,000 for cash.
- The two ledger accounts from the narratives are sales and cash.
- We have sold goods, so sales (i.e., revenue) will increase and since we are receiving cash it will also increase.
- Sales is an income and cash is an asset.
- Since cash (asset item) is increasing, we debit the cash general ledger account.
- Also because sales (i.e., income item) is increasing, we credit the sales general ledger account.
We make a journal entry for the transaction as depicted below.
| Ledger accounts | Debit ($) | Credit ($) |
|---|---|---|
| Cash | 5,000 | |
| Sales | 5,000 | |
| Being sales of goods for cash |
You can also show the same transaction using T-accounts. When you use a T-account, you record the entry on the debit or credit side and use the description to reference the corresponding account. This makes the duality concept visible: each entry points to the other account affected by the same transaction.
Try the next example on your own.
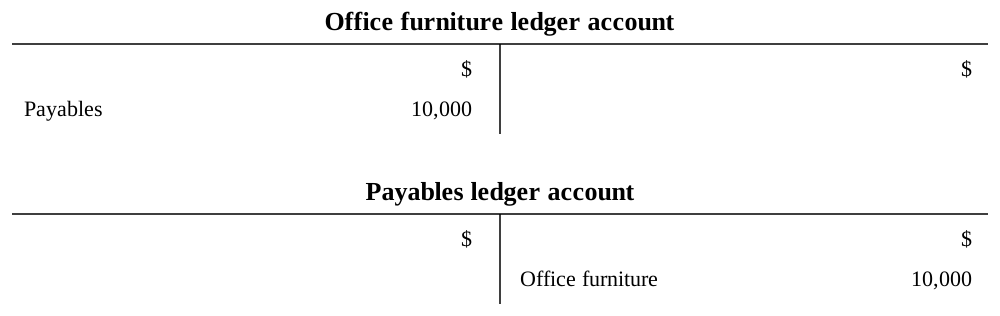
Narrative 2: Kofi bought office furniture costing $10,000 on credit.
- What are the two ledger accounts involved?
- What is the effect on each account?
- What financial statement elements do the ledger accounts relate to?
- What is the journal entry?
- The two ledger accounts are office furniture and payables.
- Kofi acquired office furniture, so office furniture increases. He bought it on credit, so payables (what he owes) also increase.
- Office furniture is an asset, and payables are a liability.
- Since office furniture (an asset) is increasing, we debit the office furniture ledger account. Since payables (a liability) are increasing, we credit the payables ledger account.
| Ledger accounts | Debit ($) | Credit ($) |
|---|---|---|
| Office furniture | 10,000 | |
| Payables | 10,000 | |
| Being purchase of office furniture on credit |
The T-account is shown below:
Try this example on your own.
Narrative 3: Kofi paid $3,000 cash to the furniture supplier.
- What are the two ledger accounts involved?
- What is the effect on each account?
- What financial statement elements do the ledger accounts relate to?
- What is the journal entry?
- The two ledger accounts are cash and payables.
- Kofi paid cash to the furniture supplier, so cash decreases and payables also decrease.
- Cash is an asset, and payables are a liability.
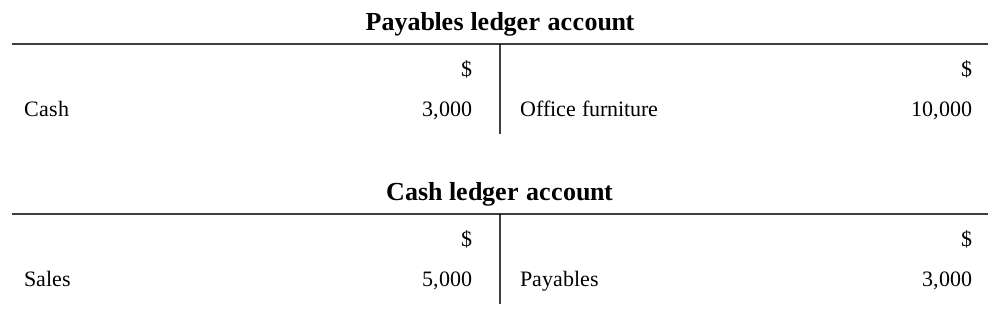
- Since cash (an asset) is decreasing, we credit the cash ledger account. Since payables (a liability) are decreasing, we debit the payables ledger account.
| Ledger accounts | Debit ($) | Credit ($) |
|---|---|---|
| Payables | 3,000 | |
| Cash | 3,000 | |
| Being cash payment to the furniture supplier |
The T-accounts, continued from the earlier narratives, are shown below:
Balancing a ledger account
In practice, many transactions occur, and many journal entries are posted. Periodically (daily, weekly, monthly, etc.), the accountant determines the net amount on each ledger account. This process is called balancing the account. Follow these steps when you want to balance any account.
Steps
- Draw total lines beneath the last debit and credit entries, leaving one line space.
- Add all debit entries and all credit entries separately.
- Enter the higher of the two totals on both sides of the account.
- Find the difference between the two sides.
- Record this difference as the Balance c/d on the side with the lower total, then bring it down as Balance b/d on the opposite side.
Demonstration of balancing an account
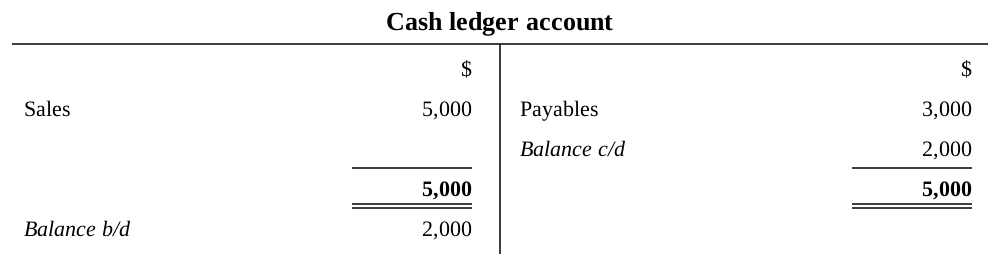
Let’s balance the ledger accounts we earlier created. Let’s demonstrate with the cash ledger account.
- Total debit balance is $5,000 as against a $ 3,000 total credit balance.
- We enter $ 5,000 as the total on both the debit and credit sides of the general ledger account.
- The shortfall of $ 2,000 (i.e., $ 5,000 minus $3,000) on the credit side becomes balance carried down (c/d).
- The shortfall is then carried to the opposite (i.e., debit) side as the balance brought down (b/d).
This is shown below.
Closing of ledger accounts
Closing a ledger account is similar to balancing off, but it occurs specifically at the end of the accounting year. The closing balances are used in preparing the financial statements.
- Income and expense related accounts are closed into the statement of profit or loss.
- Asset, liability, and equity related accounts are both carried forward to the next period as well as reported in the current year’s statement of financial position.
Rules for closing-off:
- Income accounts: debit the income ledger, credit the statement of profit or loss.
- Expense accounts: credit the expense ledger, debit the statement of profit or loss.
Example: closing Kofi’s sales account
At the year end, Kofi’s sales account (from Narrative 1) has a credit balance of $5,000. Being income, it’s closed to the statement of profit or loss: debit sales $5,000, credit statement of profit or loss $5,000, leaving the sales account with a nil balance ready for the new year. An expense account closes the same way but in the opposite direction - debit the statement of profit or loss, credit the expense ledger.
Cash, however, is an asset, so it isn’t closed. Its $2,000 debit balance from the balancing example above is simply carried down (b/d) and reported in the statement of financial position.