


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
ACCA Financial Accounting
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. The context and purpose of financial reporting
2. Accounting principles, concepts and qualitative characteristics
3. Double-entry bookkeeping and accounting systems
4. Recording transactions and events
5. Reconciliations
6. Preparing trial balance
7. Preparing financial statements
7.1 Statements of profit or loss and financial position
7.2 Statement of cash flow
7.2.1 Introduction to cashflow statement
7.2.2 Operating cashflows
7.2.3 Investing and financing cashflows
7.2.4 Comprehensive question
7.2.5 Benefits and drawbacks
7.3 Incomplete records
7.4 Events after the reporting period
7.5 Disclosure-notes
8. Preparing basic consolidated financial statements
9. Interpretation of financial statements
Wrapping up
Achievable logoAchievable logo
7.2.2 Operating cashflows
Achievable ACCA Financial Accounting
7. Preparing financial statements
7.2. Statement of cash flow
Our ACCA course is currently in development and is a work-in-progress.

Operating cashflows

12 min read
Font
Discuss
Share
Feedback

This chapter explains how to calculate cash flows from operating activities using two methods:

  • the direct method (showing actual cash receipts and payments)
  • the indirect method (adjusting profit for non-cash items and working capital changes)

Learning objective

By the end of this chapter, you should be able to:

  • Calculate the figures needed for the statement of cash flows in accordance with IFRS Accounting Standards, including:
    • Cash flows from operating activities (direct and indirect methods for calculating cash from operating activities before income taxes)
  • Identify the treatment of given transactions in a statement of cash flows

IAS 7 encourages entities to report cash flows from operating activities using the direct method. However, in practice, the direct method is rarely used.

Direct method

The direct method reports major classes of gross cash receipts (money coming in) and payments (money going out). This method can be useful for estimating future cash flows because it shows cash movements directly - information you don’t see in the same way under the indirect method.

$
Cash receipts from customers X
Cash paid to suppliers (X)
Cash paid to employees (X)
Cash paid for operating expenses (X)
Cash generated from operations X
Income taxes paid (X)
Net cash from operating activities X

Watch out: Rarely will the amounts for these items be given straightforwardly in a question. Usually, you must calculate each amount (as applicable) using information from the statement of profit or loss (for example, sales, cost of sales, and operating expenses) and the statement of financial position.

To do this, you’ll typically apply the double-entry principle and open up general ledger (T-) accounts to determine the cash payment or receipt. In many cases, the cash payment or receipt is the balancing figure - you find it by working backwards (a work back approach).

Work back approach example

In many questions, you’ll be given the opening and closing balances of an account (plus any non-cash activity during the period). From that, you should be able to work backwards to determine the cash payment or cash receipt.

Let’s see how that works.

A company reports revenue (credit) of $50,000 for a period in the statement of profit or loss. Trade receivables at the beginning and end of the period were $300,000 and $150,000, respectively.

Determine the cash received from customers for the period.

Do you know the answer?

(spoiler)

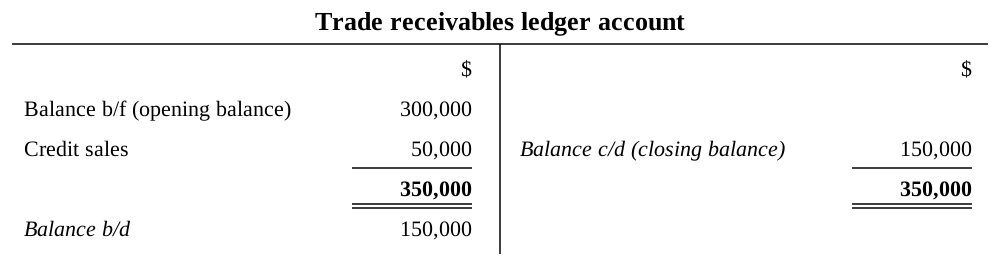
Step 1: Put all the necessary information from the question into the T-accounts.

Trade receivables ledger account, step 1: opening balance of 300,000 and credit sales of 50,000 on the debit side; closing balance c/d of 150,000 on the credit side, with the cash line still to find; totals of 350,000; balance b/d of 150,000.
Trade receivables closing balance
Achievable

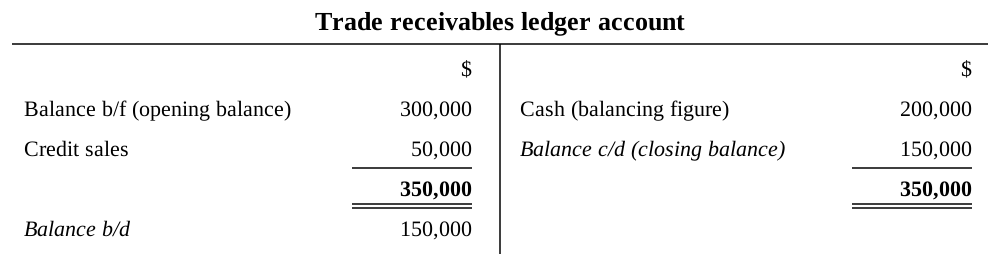
Step 2: Find the balancing figure that makes the T-account balance.

Trade receivables ledger account, step 2: cash of 200,000 found as the balancing figure on the credit side, with closing balance c/d of 150,000; totals of 350,000.
Trade receivables with balancing figure
Achievable

From the ledger account above, cash of $200,000 is credited in the trade receivables general ledger account. To complete the double entry, the Cash/Bank account must be debited by $200,000, which represents an increase in cash.

That means this balancing figure is a cash inflow (a cash receipt from customers).

Rule of thumb: When the balancing figure in an account is on the debit side, it represents a cash outflow (payment). When it is on the credit side, it represents a cash inflow (receipt).

Illustration: direct method

Asempa Ltd had the following transactions during the year ended 31 December 2024:

  • Inventory purchases: Total purchases from suppliers during the year: $45,800. Amount still owing to suppliers at year-end: $6,200. Trade payables brought forward (opening balance): $4,500
  • Rental expenses: Rent expense for the year is given as $18,000. Rent accruals at year-end were $2,000, and rent owing at the beginning of the year is $1,200.
  • Employee costs: Salaries and wages expense: $28,400. Accrued salaries at year-end (unpaid): $3,100. Accrued salaries brought forward: $2,800
  • Sales revenue: Total sales revenue for the year: $92,500. The trade receivables at year-end and year beginning were given as $8,700 and $6,300, respectively.
  • Income taxes: Income tax expense for the year: $1,000. Income tax payable at year-end: $400. Income tax payable at the beginning of the year: $600

Required: Prepare the Cash flows from operating activities section of the statement of cash flows for Asempa Ltd for the year ended 31 December 2024, using the direct method.

Suggested solution:

Hint: Calculate the cash payments and receipts carefully. You can use the T-account or statement approach - whichever works best for you. Just make sure you compute the figures yourself.

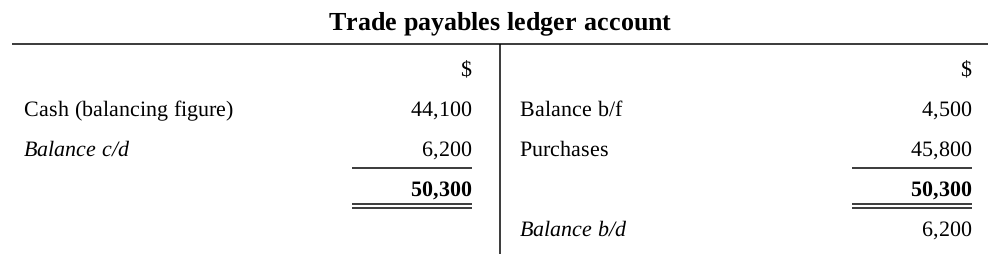
  1. Compute the cash payments to suppliers
(spoiler)
Trade payables ledger account: cash of 44,100 found as the balancing figure and balance c/d of 6,200 on the debit side; balance b/f of 4,500 and purchases of 45,800 on the credit side; totals of 50,300; balance b/d of 6,200.
Trade payables ledger account
Achievable

Cash paid to suppliers = $4,500 + $45,800 − $6,200 = $44,100

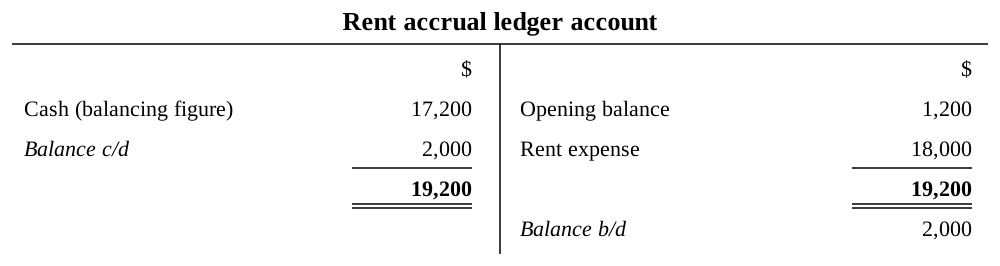
  1. Compute cash paid for rent expenses
(spoiler)
Rent accrual ledger account: cash of 17,200 found as the balancing figure and balance c/d of 2,000 on the debit side; opening balance of 1,200 and rent expense of 18,000 on the credit side; totals of 19,200; balance b/d of 2,000.
Rent accrual ledger account
Achievable

Cash paid for rent = $18,000 + $1,200 − $2,000 = $17,200

  1. Compute cash payments for salaries
(spoiler)
Salaries payable ledger account: cash of 28,100 found as the balancing figure and balance c/d of 3,100 on the debit side; opening balance of 2,800 and salaries expenses of 28,400 on the credit side; totals of 31,200; balance b/d of 3,100.
Salaries payable ledger account
Achievable

Cash paid for salaries = $28,400 + $2,800 − $3,100 = $28,100

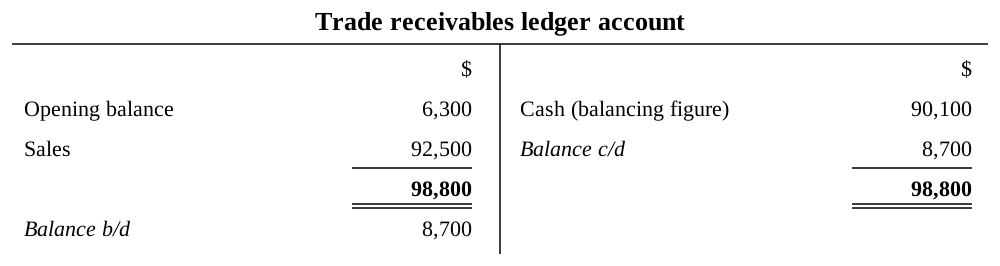
  1. Compute cash received from customers
(spoiler)
Trade receivables ledger account: opening balance of 6,300 and sales of 92,500 on the debit side; cash of 90,100 found as the balancing figure and balance c/d of 8,700 on the credit side; totals of 98,800; balance b/d of 8,700.
Trade receivables ledger account
Achievable

Cash received from customers = $6,300 + $92,500 − $8,700 = $90,100

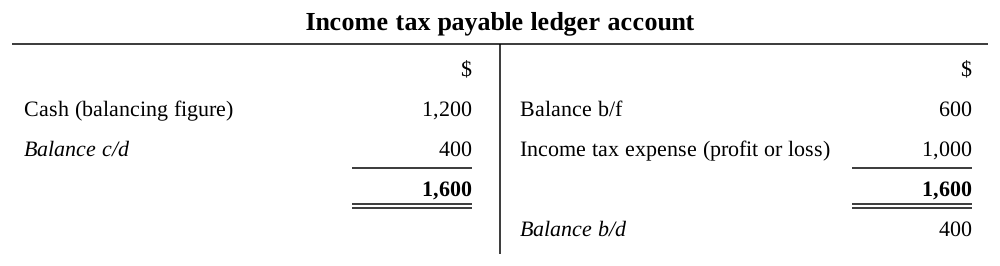
  1. Compute income tax paid
(spoiler)
Income tax payable ledger account: cash of 1,200 found as the balancing figure and balance c/d of 400 on the debit side; balance b/f of 600 and the income tax expense of 1,000, from profit or loss, on the credit side; totals of 1,600; balance b/d of 400.
Income tax payable ledger account
Achievable

Income tax paid = $600 + $1,000 − $400 = $1,200

Now prepare the cash flows from operating activities.

Cash flows from operating activities (direct method)

$
Cash received from customers 90,100
Cash paid to suppliers (44,100)
Cash paid for rent (17,200)
Cash paid to employees (28,100)
Cash generated from operations 700
Income tax paid (1,200)
Net cash from operating activities (500)

Indirect method

The indirect method starts with operating profit (IFRS 18 amended IAS 7 to make it the starting point) and then adjusts it for:

  • non-cash items
  • changes in working capital

Format

$
Operating profit X
Adjustments for:
Depreciation and amortisation X
Loss on disposal of assets X
Gain on disposal of assets (X)
Changes in working capital:
Increase in inventory (X)
Decrease in inventory X
Increase in trade receivables (X)
Decrease in trade receivables X
Increase in trade payables X
Decrease in trade payables (X)
Cash generated from operations X
Income taxes paid (X)
Net cash from operating activities X

Key adjustments explained:

  1. Non-cash expenses (add back): Depreciation, amortisation, and impairment losses reduce profit without using cash. These items are not actual cash outflows, but they were deducted when calculating profit. To move from accounting profit to operating cash flow, we add them back.
  2. Non-cash income (deduct): A gain on disposal of a non-current asset increases profit, but the sale proceeds are an investing cash inflow, not an operating one, so the gain is deducted here. (A revaluation gain on a non-current asset is recognised in other comprehensive income under IAS 16, not in profit or loss, so it never needs this adjustment.)
  3. Finance costs and investment income: operating profit is before both, so neither is adjusted here. Interest paid is shown under financing activities, and interest and dividends received under investing activities. A question that gives only profit before income taxes reaches operating profit first, by adding back finance costs and deducting investment income, as the illustration below shows.
  4. Working capital changes: An increase in inventory or trade receivables ties up cash, so it’s deducted; a decrease frees up cash, so it’s added. An increase in trade payables means less cash was paid out, so it’s added; a decrease means more cash was paid out, so it’s deducted.

Illustration: indirect method

SBC Ltd statement of profit or loss extracts are given as:

$
Profit before income taxes 180,000
Income tax expense (38,000)
Profit for the year 142,000

You have been given the following additional information. The items below were considered in the determination of profit before income taxes.

  • Depreciation charge: $45,000
  • Loss on disposal of equipment: $8,000
  • Interest expense: $12,000
  • Investment income: $5,000
  • Income taxes paid during the year: $38,000

An analysis of the statement of financial position shows that:

  • Inventory increased by $22,000
  • Trade receivables increased by $31,000
  • Trade payables decreased by $14,000

Required: Prepare the cash flows from operating activities section of the statement of cash flows for the period, using the indirect method.

Suggested solution:

$
Profit before income taxes 180,000
Add: finance costs 12,000
Less: investment income (5,000)
Operating profit 187,000
Adjustments for:
Depreciation charge 45,000
Loss on disposal of assets 8,000
240,000
Changes in working capital:
Increase in inventory (22,000)
Increase in trade receivables (31,000)
Decrease in trade payables (14,000)
Cash generated from operations 173,000
Income taxes paid (38,000)
Net cash from operating activities 135,000

The next chapter, Investing and financing cashflows, covers cash flows from investing and financing activities, completing the statement of cash flows.

Direct method basics

  • Reports gross cash receipts and payments (customers, suppliers, employees, operating expenses)
  • Format: cash receipts/payments → Cash generated from operations → less income taxes paid → Net cash from operating activities
  • Rarely used in practice despite IAS 7 encouraging it; useful for forecasting future cash flows since it shows actual cash movements

Work back approach (T-accounts)

  • Figures usually aren’t given directly—must derive via T-accounts using opening/closing balances plus statement of profit or loss activity (e.g., sales, purchases, expense)
  • Cash amount is typically the balancing figure
  • Rule of thumb: balancing figure on debit side = cash outflow; on credit side = cash inflow
  • General formula pattern: opening balance + period expense/sales − closing balance = cash paid/received

Direct method illustration (Asempa Ltd)

  • Cash paid to suppliers = opening payables + purchases − closing payables
  • Cash paid for rent = rent expense + opening accrual − closing accrual
  • Cash paid for salaries = salaries expense + opening accrual − closing accrual
  • Cash received from customers = opening receivables + sales − closing receivables
  • Income tax paid = opening tax payable + tax expense − closing tax payable
  • All figures combine into the operating cash flow statement format

Indirect method basics

  • Starts with operating profit (per IFRS 18 amendment to IAS 7), not profit before tax directly
  • Adjusts for non-cash items and working capital changes to reach cash generated from operations
  • Key adjustments:
    • Add back non-cash expenses (depreciation, amortisation, impairment, loss on disposal)
    • Deduct non-cash income (gain on disposal) — proceeds are investing activity, not operating
    • Revaluation gains (IAS 16) never adjusted here since they bypass profit or loss (go to OCI)
    • Operating profit excludes finance costs/investment income: interest paid shown under financing, interest/dividends received under investing
    • If only profit before tax is given, add back finance costs and deduct investment income to reach operating profit first
  • Working capital rules:
    • Increase in inventory/receivables = cash outflow (deduct)
    • Decrease in inventory/receivables = cash inflow (add)
    • Increase in payables = cash inflow (add, less cash paid out)
    • Decrease in payables = cash outflow (deduct, more cash paid out)

Indirect method illustration (SBC Ltd)

  • Start with profit before tax → add back finance costs, deduct investment income → operating profit
  • Add back depreciation and loss on disposal to operating profit
  • Adjust for working capital changes (inventory, receivables, payables)
  • Subtract income taxes paid to reach Net cash from operating activities

Sign up for free to take 16 quiz questions on this topic

Previous
Next  | 7.2.3 Investing and financing cashflows
All rights reserved ©2016 - 2026 Achievable, Inc.

Operating cashflows

This chapter explains how to calculate cash flows from operating activities using two methods:

  • the direct method (showing actual cash receipts and payments)
  • the indirect method (adjusting profit for non-cash items and working capital changes)

Learning objective

By the end of this chapter, you should be able to:

  • Calculate the figures needed for the statement of cash flows in accordance with IFRS Accounting Standards, including:
    • Cash flows from operating activities (direct and indirect methods for calculating cash from operating activities before income taxes)
  • Identify the treatment of given transactions in a statement of cash flows

IAS 7 encourages entities to report cash flows from operating activities using the direct method. However, in practice, the direct method is rarely used.

Direct method

The direct method reports major classes of gross cash receipts (money coming in) and payments (money going out). This method can be useful for estimating future cash flows because it shows cash movements directly - information you don’t see in the same way under the indirect method.

$
Cash receipts from customers X
Cash paid to suppliers (X)
Cash paid to employees (X)
Cash paid for operating expenses (X)
Cash generated from operations X
Income taxes paid (X)
Net cash from operating activities X

Watch out: Rarely will the amounts for these items be given straightforwardly in a question. Usually, you must calculate each amount (as applicable) using information from the statement of profit or loss (for example, sales, cost of sales, and operating expenses) and the statement of financial position.

To do this, you’ll typically apply the double-entry principle and open up general ledger (T-) accounts to determine the cash payment or receipt. In many cases, the cash payment or receipt is the balancing figure - you find it by working backwards (a work back approach).

Work back approach example

In many questions, you’ll be given the opening and closing balances of an account (plus any non-cash activity during the period). From that, you should be able to work backwards to determine the cash payment or cash receipt.

Let’s see how that works.

A company reports revenue (credit) of $50,000 for a period in the statement of profit or loss. Trade receivables at the beginning and end of the period were $300,000 and $150,000, respectively.

Determine the cash received from customers for the period.

Do you know the answer?

(spoiler)

Step 1: Put all the necessary information from the question into the T-accounts.

Step 2: Find the balancing figure that makes the T-account balance.

From the ledger account above, cash of $200,000 is credited in the trade receivables general ledger account. To complete the double entry, the Cash/Bank account must be debited by $200,000, which represents an increase in cash.

That means this balancing figure is a cash inflow (a cash receipt from customers).

Rule of thumb: When the balancing figure in an account is on the debit side, it represents a cash outflow (payment). When it is on the credit side, it represents a cash inflow (receipt).

Illustration: direct method

Asempa Ltd had the following transactions during the year ended 31 December 2024:

  • Inventory purchases: Total purchases from suppliers during the year: $45,800. Amount still owing to suppliers at year-end: $6,200. Trade payables brought forward (opening balance): $4,500
  • Rental expenses: Rent expense for the year is given as $18,000. Rent accruals at year-end were $2,000, and rent owing at the beginning of the year is $1,200.
  • Employee costs: Salaries and wages expense: $28,400. Accrued salaries at year-end (unpaid): $3,100. Accrued salaries brought forward: $2,800
  • Sales revenue: Total sales revenue for the year: $92,500. The trade receivables at year-end and year beginning were given as $8,700 and $6,300, respectively.
  • Income taxes: Income tax expense for the year: $1,000. Income tax payable at year-end: $400. Income tax payable at the beginning of the year: $600

Required: Prepare the Cash flows from operating activities section of the statement of cash flows for Asempa Ltd for the year ended 31 December 2024, using the direct method.

Suggested solution:

Hint: Calculate the cash payments and receipts carefully. You can use the T-account or statement approach - whichever works best for you. Just make sure you compute the figures yourself.

  1. Compute the cash payments to suppliers
(spoiler)

Cash paid to suppliers = $4,500 + $45,800 − $6,200 = $44,100

  1. Compute cash paid for rent expenses
(spoiler)

Cash paid for rent = $18,000 + $1,200 − $2,000 = $17,200

  1. Compute cash payments for salaries
(spoiler)

Cash paid for salaries = $28,400 + $2,800 − $3,100 = $28,100

  1. Compute cash received from customers
(spoiler)

Cash received from customers = $6,300 + $92,500 − $8,700 = $90,100

  1. Compute income tax paid
(spoiler)

Income tax paid = $600 + $1,000 − $400 = $1,200

Now prepare the cash flows from operating activities.

Cash flows from operating activities (direct method)

$
Cash received from customers 90,100
Cash paid to suppliers (44,100)
Cash paid for rent (17,200)
Cash paid to employees (28,100)
Cash generated from operations 700
Income tax paid (1,200)
Net cash from operating activities (500)

Indirect method

The indirect method starts with operating profit (IFRS 18 amended IAS 7 to make it the starting point) and then adjusts it for:

  • non-cash items
  • changes in working capital

Format

$
Operating profit X
Adjustments for:
Depreciation and amortisation X
Loss on disposal of assets X
Gain on disposal of assets (X)
Changes in working capital:
Increase in inventory (X)
Decrease in inventory X
Increase in trade receivables (X)
Decrease in trade receivables X
Increase in trade payables X
Decrease in trade payables (X)
Cash generated from operations X
Income taxes paid (X)
Net cash from operating activities X

Key adjustments explained:

  1. Non-cash expenses (add back): Depreciation, amortisation, and impairment losses reduce profit without using cash. These items are not actual cash outflows, but they were deducted when calculating profit. To move from accounting profit to operating cash flow, we add them back.
  2. Non-cash income (deduct): A gain on disposal of a non-current asset increases profit, but the sale proceeds are an investing cash inflow, not an operating one, so the gain is deducted here. (A revaluation gain on a non-current asset is recognised in other comprehensive income under IAS 16, not in profit or loss, so it never needs this adjustment.)
  3. Finance costs and investment income: operating profit is before both, so neither is adjusted here. Interest paid is shown under financing activities, and interest and dividends received under investing activities. A question that gives only profit before income taxes reaches operating profit first, by adding back finance costs and deducting investment income, as the illustration below shows.
  4. Working capital changes: An increase in inventory or trade receivables ties up cash, so it’s deducted; a decrease frees up cash, so it’s added. An increase in trade payables means less cash was paid out, so it’s added; a decrease means more cash was paid out, so it’s deducted.

Illustration: indirect method

SBC Ltd statement of profit or loss extracts are given as:

$
Profit before income taxes 180,000
Income tax expense (38,000)
Profit for the year 142,000

You have been given the following additional information. The items below were considered in the determination of profit before income taxes.

  • Depreciation charge: $45,000
  • Loss on disposal of equipment: $8,000
  • Interest expense: $12,000
  • Investment income: $5,000
  • Income taxes paid during the year: $38,000

An analysis of the statement of financial position shows that:

  • Inventory increased by $22,000
  • Trade receivables increased by $31,000
  • Trade payables decreased by $14,000

Required: Prepare the cash flows from operating activities section of the statement of cash flows for the period, using the indirect method.

Suggested solution:

$
Profit before income taxes 180,000
Add: finance costs 12,000
Less: investment income (5,000)
Operating profit 187,000
Adjustments for:
Depreciation charge 45,000
Loss on disposal of assets 8,000
240,000
Changes in working capital:
Increase in inventory (22,000)
Increase in trade receivables (31,000)
Decrease in trade payables (14,000)
Cash generated from operations 173,000
Income taxes paid (38,000)
Net cash from operating activities 135,000

The next chapter, Investing and financing cashflows, covers cash flows from investing and financing activities, completing the statement of cash flows.

Key points

Direct method basics

  • Reports gross cash receipts and payments (customers, suppliers, employees, operating expenses)
  • Format: cash receipts/payments → Cash generated from operations → less income taxes paid → Net cash from operating activities
  • Rarely used in practice despite IAS 7 encouraging it; useful for forecasting future cash flows since it shows actual cash movements

Work back approach (T-accounts)

  • Figures usually aren’t given directly—must derive via T-accounts using opening/closing balances plus statement of profit or loss activity (e.g., sales, purchases, expense)
  • Cash amount is typically the balancing figure
  • Rule of thumb: balancing figure on debit side = cash outflow; on credit side = cash inflow
  • General formula pattern: opening balance + period expense/sales − closing balance = cash paid/received

Direct method illustration (Asempa Ltd)

  • Cash paid to suppliers = opening payables + purchases − closing payables
  • Cash paid for rent = rent expense + opening accrual − closing accrual
  • Cash paid for salaries = salaries expense + opening accrual − closing accrual
  • Cash received from customers = opening receivables + sales − closing receivables
  • Income tax paid = opening tax payable + tax expense − closing tax payable
  • All figures combine into the operating cash flow statement format

Indirect method basics

  • Starts with operating profit (per IFRS 18 amendment to IAS 7), not profit before tax directly
  • Adjusts for non-cash items and working capital changes to reach cash generated from operations
  • Key adjustments:
    • Add back non-cash expenses (depreciation, amortisation, impairment, loss on disposal)
    • Deduct non-cash income (gain on disposal) — proceeds are investing activity, not operating
    • Revaluation gains (IAS 16) never adjusted here since they bypass profit or loss (go to OCI)
    • Operating profit excludes finance costs/investment income: interest paid shown under financing, interest/dividends received under investing
    • If only profit before tax is given, add back finance costs and deduct investment income to reach operating profit first
  • Working capital rules:
    • Increase in inventory/receivables = cash outflow (deduct)
    • Decrease in inventory/receivables = cash inflow (add)
    • Increase in payables = cash inflow (add, less cash paid out)
    • Decrease in payables = cash outflow (deduct, more cash paid out)

Indirect method illustration (SBC Ltd)

  • Start with profit before tax → add back finance costs, deduct investment income → operating profit
  • Add back depreciation and loss on disposal to operating profit
  • Adjust for working capital changes (inventory, receivables, payables)
  • Subtract income taxes paid to reach Net cash from operating activities

More from Statement of cash flow

  • Introduction to cashflow statement
  • Investing and financing cashflows
  • Comprehensive question
  • Benefits and drawbacks