This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
Life
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
1. General Insurance Concepts
2. Producer Roles and Receipt Types
3. Principles of Life Insurance
4. Underwriting
5. Term Life Insurance
6. Whole Life Insurance
7. Variable Insurance Products
8. Group Life Insurance
9. Life Insurance Provisions
9.1 Ownership and Assignments
9.2 Beneficiaries
9.3 Critical Clauses and Provisions
9.4 Policy Riders
9.5 Non-Forfeiture, Dividend, and Settlement Options
10. Annuities
11. Taxation of Life Insurance Products
12. Qualified Retirement Plans
Wrapping up
Achievable logoAchievable logo
9.2 Beneficiaries
Achievable Life
9. Life Insurance Provisions

Beneficiaries

9 min read
Font
Discuss
Share
Feedback

Beneficiary designation

A beneficiary is the person or entity that receives the policy proceeds when the insured dies. A person who insures their own life may name anyone as beneficiary, and that beneficiary doesn’t need an insurable interest. When one person buys insurance on another person’s life, the policy owner needs an insurable interest in the insured when the policy is issued, and many states also require the proceeds to be payable to the insured’s estate or to someone who had an insurable interest in the insured at that time.

For example, a distant relative who buys a policy on their own life could name you as beneficiary even if you have no insurable interest in that person.

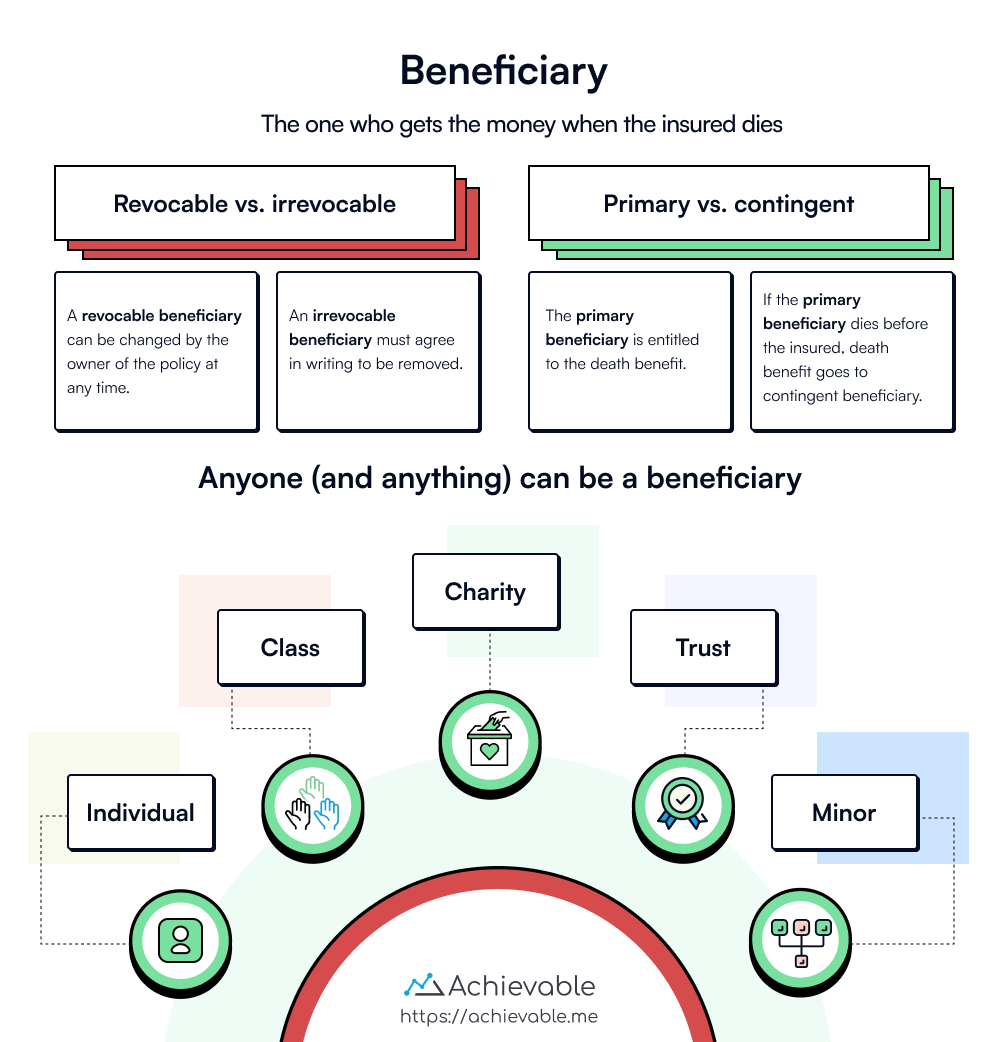
Revocable vs. irrevocable

If a beneficiary is named revocable, the owner can change the beneficiary without the beneficiary’s consent. Because this designation is flexible, it’s the most common.

With an irrevocable designation, the owner can’t change the beneficiary or assign the policy without the beneficiary’s permission. The beneficiary has a vested right to the policy benefits.

Primary vs. contingent

The primary beneficiary is the first person (or persons) entitled to receive benefits. If you name multiple primary beneficiaries, you can split the proceeds among them.

The contingent beneficiary receives benefits only if the primary beneficiary is deceased at the insured’s death. If both the primary and contingent beneficiaries predecease the insured, the final beneficiary is the insured’s estate.

Common beneficiary designations

Individuals:

  • The most common designation is to name one or more individuals.
  • If multiple people are named beneficiary, per capita and per stirpes are used.
    • Under a per capita beneficiary designation, if one of the named beneficiaries predeceases the insured, the remaining beneficiaries divide that person’s share in addition to receiving their own.
    • Under a per stirpes (Latin for “through the root”) designation, the proceeds that would have gone to the deceased beneficiary don’t go to the other beneficiaries. Instead, they go to the deceased beneficiary’s heirs.

Class designations:

  • Often used when several children are named beneficiary and the owner wants them to share the proceeds equally, such as “all my children,” rather than naming each child individually.

Estates:

  • If no beneficiary is named, or if all named beneficiaries have predeceased the insured, the final beneficiary is the insured’s estate.

Minors:

  • A minor may be named as beneficiary if a guardian or trustee is appointed to receive the funds on the minor’s behalf.

Charities:

  • It’s not uncommon for the owner of a life insurance policy to name a charity as beneficiary.

Trusts:

  • Trusts are often established to receive proceeds from a life insurance policy. When a trust is named as a beneficiary, the trustee may manage the assets according to the trust terms but may not personally benefit from them.
Sidenote
Know this...

An inter-vivos trust is established while the policy owner is still living. A testamentary trust is established to receive life insurance proceeds, but is not a taxable entity until the moment of death.

Beneficiary types

Spendthrift clause

A spendthrift clause lets the policy owner choose a settlement option where the beneficiary receives benefits over time rather than as a lump sum.

It also:

  • prevents the proceeds from being assigned, and
  • helps protect the proceeds from claims by the beneficiary’s creditors.

This clause is often used to protect beneficiaries from creditors or from poor money management.

Common disaster clause

Most states have enacted the Uniform Simultaneous Death Act. While details vary by state, the basic rule is that if the insured and the beneficiary die at the same time, the death benefit is paid as if the insured outlived the beneficiary.

This prevents the death benefit from passing into the estate of a beneficiary who is already deceased, only to be distributed immediately from that estate. That process can trigger additional legal proceedings, costs, and estate taxes.

A common disaster clause adds a survivorship requirement: the primary beneficiary must survive the insured by a stated number of days (usually 30-90 days). If the primary beneficiary doesn’t survive for that period, the death benefit is automatically paid to the contingent beneficiary.

Lesson summary

  • Beneficiary designation: The beneficiary receives the policy proceeds and may be named revocable or irrevocable. Beneficiaries may be primary or contingent, and may be individuals, estates, minors, charities, or trusts.

  • Spendthrift clause: Offers a settlement option where proceeds are received over time and helps protect beneficiaries from creditors or poor money management.

  • Common disaster clause: Ensures that if the primary beneficiary does not survive the insured, the benefit will pass to the contingent beneficiary.

Chapter vocabulary

Definitions
Beneficiary
(1) A person or entity designated to receive benefits under an insurance policy, other than as the insured. (2) In Medicare, any person enrolled in the program.

(2) Any person enrolled in Medicare.

Common Disaster Provision
A provision in a life insurance contract stating that the primary beneficiary must survive the insured for a specified period of time (commonly 30-90 days) in order to receive the proceeds. If the primary beneficiary does not survive the insured for this period, the proceeds are paid to the contingent beneficiary.

Example: Rob names his friend Matt as the primary beneficiary and his wife Yvonne as the contingent beneficiary. Their policy has a 60-day survivorship requirement. Rob dies in an accident, and Matt dies six months later from unrelated causes. Because Matt survived Rob by more than 60 days, he receives the proceeds. Upon Matt’s death, the proceeds become part of his estate.

Contingent Beneficiary
A secondary beneficiary designated to receive the proceeds of a policy if the primary beneficiary predeceases the insured, or dies in a common accident.
Irrevocable Beneficiary
A life insurance policy beneficiary who has a vested interest in the policy proceeds even during the insured’s lifetime because the policy owner has the right to change the beneficiary designation only after obtaining the beneficiary’s consent.
Per Capita (Latin: by heads)
Applied to beneficiaries, it refers to division of policy proceeds among the surviving beneficiaries.
Per Stirpes (Latin: by roots)
Applied to beneficiaries, it refers to division of policy proceeds among surviving beneficiaries with a full share to the heirs of any deceased beneficiary.
Primary Beneficiary
The beneficiary named first to receive proceeds or benefits of a policy that provides death benefits.
Revocable Beneficiary
The beneficiary in a life insurance policy in which the owner reserves the right to revoke or change the beneficiary.
Spendthrift Clause
A clause that may be written into a life policy providing that a beneficiary or creditor cannot subject the proceeds or payments received under the settlement option to transfer, commutation, or encumbrance, or to any legal action taken by the creditors against the beneficiary.

Beneficiary basics

  • Beneficiary = person/entity receiving policy proceeds at insured’s death
  • Self-insured policy: owner may name anyone, no insurable interest required for beneficiary
  • Third-party policy: policy owner must have insurable interest in insured at issue; many states require proceeds go to insured’s estate or someone with insurable interest

Revocable vs. irrevocable

  • Revocable: owner can change beneficiary without consent (most common, flexible)
  • Irrevocable: owner cannot change beneficiary or assign policy without beneficiary’s permission
    • Beneficiary holds vested right to benefits

Primary vs. contingent

  • Primary beneficiary: first in line for proceeds; multiple primaries can split proceeds
  • Contingent beneficiary: receives proceeds only if primary predeceases insured
  • If both predecease insured, proceeds go to insured’s estate

Types of beneficiary designations

  • Individuals: most common; multiple beneficiaries use per capita or per stirpes
    • Per capita: survivors divide deceased beneficiary’s share among themselves
    • Per stirpes (“through the root”): deceased beneficiary’s share passes to their heirs, not other beneficiaries
  • Class designations: group naming (e.g., “all my children”) for equal sharing
  • Estates: default beneficiary if none named or all predecease insured
  • Minors: allowed if guardian/trustee appointed to manage funds
  • Charities: common beneficiary choice
  • Trusts: trustee manages proceeds per trust terms, cannot personally benefit
    • Inter-vivos trust: created while owner is alive
    • Testamentary trust: created to receive proceeds at death; not taxable until death

Spendthrift clause

  • Allows settlement option paying benefits over time instead of lump sum
  • Prevents proceeds from being assigned
  • Protects proceeds from beneficiary’s creditors or poor money management

Common disaster clause

  • Based on Uniform Simultaneous Death Act: if insured and beneficiary die simultaneously, insured treated as having outlived beneficiary (avoids proceeds passing through beneficiary’s estate)
  • Adds survivorship requirement (typically 30-90 days) for primary beneficiary to receive proceeds
  • If primary doesn’t survive required period, proceeds pass to contingent beneficiary

Sign up for free to take 16 quiz questions on this topic

Previous
Next  | 9.3 Critical Clauses and Provisions
All rights reserved ©2016 - 2026 Achievable, Inc.

Beneficiaries

Beneficiary designation

A beneficiary is the person or entity that receives the policy proceeds when the insured dies. A person who insures their own life may name anyone as beneficiary, and that beneficiary doesn’t need an insurable interest. When one person buys insurance on another person’s life, the policy owner needs an insurable interest in the insured when the policy is issued, and many states also require the proceeds to be payable to the insured’s estate or to someone who had an insurable interest in the insured at that time.

For example, a distant relative who buys a policy on their own life could name you as beneficiary even if you have no insurable interest in that person.

Revocable vs. irrevocable

If a beneficiary is named revocable, the owner can change the beneficiary without the beneficiary’s consent. Because this designation is flexible, it’s the most common.

With an irrevocable designation, the owner can’t change the beneficiary or assign the policy without the beneficiary’s permission. The beneficiary has a vested right to the policy benefits.

Primary vs. contingent

The primary beneficiary is the first person (or persons) entitled to receive benefits. If you name multiple primary beneficiaries, you can split the proceeds among them.

The contingent beneficiary receives benefits only if the primary beneficiary is deceased at the insured’s death. If both the primary and contingent beneficiaries predecease the insured, the final beneficiary is the insured’s estate.

Common beneficiary designations

Individuals:

  • The most common designation is to name one or more individuals.
  • If multiple people are named beneficiary, per capita and per stirpes are used.
    • Under a per capita beneficiary designation, if one of the named beneficiaries predeceases the insured, the remaining beneficiaries divide that person’s share in addition to receiving their own.
    • Under a per stirpes (Latin for “through the root”) designation, the proceeds that would have gone to the deceased beneficiary don’t go to the other beneficiaries. Instead, they go to the deceased beneficiary’s heirs.

Class designations:

  • Often used when several children are named beneficiary and the owner wants them to share the proceeds equally, such as “all my children,” rather than naming each child individually.

Estates:

  • If no beneficiary is named, or if all named beneficiaries have predeceased the insured, the final beneficiary is the insured’s estate.

Minors:

  • A minor may be named as beneficiary if a guardian or trustee is appointed to receive the funds on the minor’s behalf.

Charities:

  • It’s not uncommon for the owner of a life insurance policy to name a charity as beneficiary.

Trusts:

  • Trusts are often established to receive proceeds from a life insurance policy. When a trust is named as a beneficiary, the trustee may manage the assets according to the trust terms but may not personally benefit from them.
Sidenote
Know this...

An inter-vivos trust is established while the policy owner is still living. A testamentary trust is established to receive life insurance proceeds, but is not a taxable entity until the moment of death.

Beneficiary types

Spendthrift clause

A spendthrift clause lets the policy owner choose a settlement option where the beneficiary receives benefits over time rather than as a lump sum.

It also:

  • prevents the proceeds from being assigned, and
  • helps protect the proceeds from claims by the beneficiary’s creditors.

This clause is often used to protect beneficiaries from creditors or from poor money management.

Common disaster clause

Most states have enacted the Uniform Simultaneous Death Act. While details vary by state, the basic rule is that if the insured and the beneficiary die at the same time, the death benefit is paid as if the insured outlived the beneficiary.

This prevents the death benefit from passing into the estate of a beneficiary who is already deceased, only to be distributed immediately from that estate. That process can trigger additional legal proceedings, costs, and estate taxes.

A common disaster clause adds a survivorship requirement: the primary beneficiary must survive the insured by a stated number of days (usually 30-90 days). If the primary beneficiary doesn’t survive for that period, the death benefit is automatically paid to the contingent beneficiary.

Lesson summary

  • Beneficiary designation: The beneficiary receives the policy proceeds and may be named revocable or irrevocable. Beneficiaries may be primary or contingent, and may be individuals, estates, minors, charities, or trusts.

  • Spendthrift clause: Offers a settlement option where proceeds are received over time and helps protect beneficiaries from creditors or poor money management.

  • Common disaster clause: Ensures that if the primary beneficiary does not survive the insured, the benefit will pass to the contingent beneficiary.

Chapter vocabulary

Definitions
Beneficiary
(1) A person or entity designated to receive benefits under an insurance policy, other than as the insured. (2) In Medicare, any person enrolled in the program.

(2) Any person enrolled in Medicare.

Common Disaster Provision
A provision in a life insurance contract stating that the primary beneficiary must survive the insured for a specified period of time (commonly 30-90 days) in order to receive the proceeds. If the primary beneficiary does not survive the insured for this period, the proceeds are paid to the contingent beneficiary.

Example: Rob names his friend Matt as the primary beneficiary and his wife Yvonne as the contingent beneficiary. Their policy has a 60-day survivorship requirement. Rob dies in an accident, and Matt dies six months later from unrelated causes. Because Matt survived Rob by more than 60 days, he receives the proceeds. Upon Matt’s death, the proceeds become part of his estate.

Contingent Beneficiary
A secondary beneficiary designated to receive the proceeds of a policy if the primary beneficiary predeceases the insured, or dies in a common accident.
Irrevocable Beneficiary
A life insurance policy beneficiary who has a vested interest in the policy proceeds even during the insured’s lifetime because the policy owner has the right to change the beneficiary designation only after obtaining the beneficiary’s consent.
Per Capita (Latin: by heads)
Applied to beneficiaries, it refers to division of policy proceeds among the surviving beneficiaries.
Per Stirpes (Latin: by roots)
Applied to beneficiaries, it refers to division of policy proceeds among surviving beneficiaries with a full share to the heirs of any deceased beneficiary.
Primary Beneficiary
The beneficiary named first to receive proceeds or benefits of a policy that provides death benefits.
Revocable Beneficiary
The beneficiary in a life insurance policy in which the owner reserves the right to revoke or change the beneficiary.
Spendthrift Clause
A clause that may be written into a life policy providing that a beneficiary or creditor cannot subject the proceeds or payments received under the settlement option to transfer, commutation, or encumbrance, or to any legal action taken by the creditors against the beneficiary.
Key points

Beneficiary basics

  • Beneficiary = person/entity receiving policy proceeds at insured’s death
  • Self-insured policy: owner may name anyone, no insurable interest required for beneficiary
  • Third-party policy: policy owner must have insurable interest in insured at issue; many states require proceeds go to insured’s estate or someone with insurable interest

Revocable vs. irrevocable

  • Revocable: owner can change beneficiary without consent (most common, flexible)
  • Irrevocable: owner cannot change beneficiary or assign policy without beneficiary’s permission
    • Beneficiary holds vested right to benefits

Primary vs. contingent

  • Primary beneficiary: first in line for proceeds; multiple primaries can split proceeds
  • Contingent beneficiary: receives proceeds only if primary predeceases insured
  • If both predecease insured, proceeds go to insured’s estate

Types of beneficiary designations

  • Individuals: most common; multiple beneficiaries use per capita or per stirpes
    • Per capita: survivors divide deceased beneficiary’s share among themselves
    • Per stirpes (“through the root”): deceased beneficiary’s share passes to their heirs, not other beneficiaries
  • Class designations: group naming (e.g., “all my children”) for equal sharing
  • Estates: default beneficiary if none named or all predecease insured
  • Minors: allowed if guardian/trustee appointed to manage funds
  • Charities: common beneficiary choice
  • Trusts: trustee manages proceeds per trust terms, cannot personally benefit
    • Inter-vivos trust: created while owner is alive
    • Testamentary trust: created to receive proceeds at death; not taxable until death

Spendthrift clause

  • Allows settlement option paying benefits over time instead of lump sum
  • Prevents proceeds from being assigned
  • Protects proceeds from beneficiary’s creditors or poor money management

Common disaster clause

  • Based on Uniform Simultaneous Death Act: if insured and beneficiary die simultaneously, insured treated as having outlived beneficiary (avoids proceeds passing through beneficiary’s estate)
  • Adds survivorship requirement (typically 30-90 days) for primary beneficiary to receive proceeds
  • If primary doesn’t survive required period, proceeds pass to contingent beneficiary

More from Life Insurance Provisions

  • Ownership and Assignments
  • Critical Clauses and Provisions
  • Policy Riders
  • Non-Forfeiture, Dividend, and Settlement Options