
Short calls
This chapter covers the fundamentals of short call options contracts. To get comfortable with the language used when discussing options, watch this video:
When an investor goes short a call, they’re bearish on the underlying security’s market price. Selling a call creates an obligation: if the option is assigned (exercised), the writer must sell the stock at the strike price.
- If the stock’s market price rises above the call’s strike price (“call up” - the call is “in the money”), the holder may exercise the option. That forces the writer to fulfill the obligation.
- If the market price falls below the strike price (the call is “out of the money”), the holder won’t exercise the option. In that case, the writer keeps the premium as a gain.
Let’s work through a few examples to understand short calls better:
Short 1 ABC Sep 75 call @ $6
This contract obligates the writer to sell ABC stock at $75 per share if assigned. The writer received $600 for selling the option ($6 premium x 100 shares). The contract expires on the third Friday in September.
The investor is betting ABC stock’s market price stays at or below $75 through expiration. If the market price rises above $75, the holder may exercise the option, which can create losses for the writer.
Math-based options questions should be expected on the exam. They typically ask about potential gains, losses, and breakeven values. Let’s go through each.
An investor goes short 1 ABC Sep 75 call @ $6. The market price rises to $100. What is the gain or loss?
Can you figure it out?
Answer = $1,900 loss
| Action | Result |
|---|---|
| Sell call | +$600 |
| Buy shares | -$10,000 |
| Assigned - sell shares | +$7,500 |
| Total | -$1,900 |
The market price rose to $100, so the option is “in the money” by $25 ($100 − $75). That’s bad for the seller.
We can safely assume the investor was assigned, which requires selling 100 ABC shares at $75. If the investor doesn’t already own the shares, they must buy 100 shares in the market for $100 and then sell them for $75.
- Loss from assignment: $25 per share x 100 shares = $2,500 loss
- Premium received: $600
- Net result: $2,500 − $600 = $1,900 loss
The further the underlying security’s market price rises, the more a call writer loses when assigned. Imagine if the market price went to $125, $200, $250, etc. While large swings in the market are relatively uncommon, they can (and do) occur. Because there’s no ceiling on how high a stock price can go, the maximum loss for a short call is unlimited.
When an option is sold with no hedge (protection), it’s considered naked. “Naked” simply means the short option position is exposed to significant risk. A short call is risky because assignment may force the investor to buy shares at the higher market price and then sell those shares at the lower strike price. Since the market has no ceiling, the investor can lose unlimited money.
In future sections, you’ll learn how investors protect themselves from risk on short options. For now, here is a quick list of investments that would cover a short call:
- Long shares
- Long call
- Rights or warrants
- Convertible securities
You may have noticed a pattern in the list above. If the writer already owns the shares - or can obtain them through something convertible (preferred stock or bonds) or exercisable (rights or warrants) into the shares - they avoid the need to buy shares at the higher market price.
While the maximum loss for a short naked call is unlimited, call writers don’t always lose significant amounts of money. Even if the option goes “in the money” (gains intrinsic value), the seller doesn’t have an overall loss until the assignment loss exceeds the premium received.
Let’s go through another example:
An investor goes short 1 ABC Sep 75 call @ $6. The market price rises to $81. What is the gain or loss?
Answer = $0 (breakeven)
| Action | Result |
|---|---|
| Sell call | +$600 |
| Buy shares | -$8,100 |
| Assigned - sell shares | +$7,500 |
| Total | $0 |
At $81, the option is $6 “in the money” ($81 − $75).
Assuming the option is exercised (a safe assumption), the investor buys ABC shares at $81 (the market price) and sells them at $75 (the strike price).
- Loss from assignment: $6 per share x 100 shares = $600 loss
- Premium received: $600
- Net result: $0 (breakeven)
The breakeven for call contracts can be found using this formula:
Did you notice the breakeven formula for long calls is the same? Since the two positions are opposite sides of the same contract, it makes sense they share the same breakeven point.
If ABC’s market price doesn’t rise too far past $75, the investor could still make a profit. For example:
An investor goes short 1 ABC Sep 75 call @ $6. The market price rises to $79. What is the gain or loss?
Answer = $200 gain
| Action | Result |
|---|---|
| Sell call | +$600 |
| Buy shares | -$7,900 |
| Assigned - sell shares | +$7,500 |
| Total | +$200 |
At $79, the option is $4 “in the money” ($79 − $75). Assignment forces the investor to buy ABC shares at $79 and sell them at $75.
- Loss from assignment: $4 per share x 100 shares = $400 loss
- Premium received: $600
- Net result: $600 − $400 = $200 gain
Expiration is the best-case scenario for investors writing (going short) options. When the option expires, the investor keeps the premium and the obligation is never triggered. The same applies to short call contracts.
An investor goes short 1 ABC Sep 75 call @ $6. The market price falls to $73. What is the gain or loss?
Answer = $600 gain
| Action | Result |
|---|---|
| Sell call | +$600 |
| Total | +$600 |
At $73, the option is $2 “out of the money” because the market price is below the $75 strike price. When the market price is at or below $75, the holder won’t exercise the call. There’s no reason to buy stock for $75 when it’s trading for $73.
An easy way to remember when a call will be assigned is the phrase “call up.” Calls are exercised only if the underlying security’s market price is above the strike price. That isn’t true here, so the option expires.
Investors with short options can only make the premium, nothing more. If exercise occurs, losses start reducing that premium and can eventually create an overall loss.
Writers can also perform closing transactions to exit their obligations before expiration.
An investor goes short 1 ABC Sep 75 call @ $6. After ABC’s market price rises to $79, the premium rises to $9, and the investor performs a closing purchase. What is the gain or loss?
Answer = $300 loss
| Action | Result |
|---|---|
| Sell call | +$600 |
| Close call | -$900 |
| Total | -$300 |
To find the profit or loss on a closing transaction, compare:
- the premium received when the option was sold, and
- the premium paid to buy it back.
Here, the investor sold the call for $6 and later bought it back for $9.
- Net loss per share: $9 − $6 = $3 loss
- Contract size: 100 shares
- Total loss: $3 x 100 = $300 loss
With option premiums representing 100 shares, the investor has a $300 overall loss.
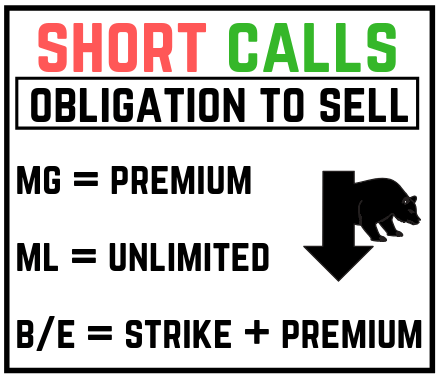
Here’s a visual summarizing the important aspects of short calls: