


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
CMA Part 1
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. External financial reporting decisions
2. Planning, budgeting, and forecasting
3. Performance management
4. Cost management
4.1 Measurement concepts
4.1.1 Cost behavior, cost objects, and cost pools
4.1.2 Product and period costs, cost drivers, and cost measurement methods
4.1.3 Inventory cost flow: trading vs. manufacturing
4.1.4 Absorption vs. variable costing: impact on inventory and income
4.1.5 Absorption vs. variable costing: illustrative problem
4.1.6 Joint and by-product costing: key concepts
4.1.7 Joint and by-product costing: cost allocation methods and by-product costing
4.2 Costing systems
4.3 Overhead costs
4.4 Supply chain management
4.5 Business process improvement
5. Internal control
6. Technology and analytics
Wrapping up
Achievable logoAchievable logo
4.1.2 Product and period costs, cost drivers, and cost measurement methods
Achievable CMA Part 1
4. Cost management
4.1. Measurement concepts
Our CMA Part 1 course is currently in development and is a work-in-progress.

Product and period costs, cost drivers, and cost measurement methods

9 min read
Font
Discuss
Share
Feedback

Product costs vs. period costs

In understanding cost classification, it’s important to distinguish between product costs and period costs, especially in the context of cost accumulation and inventory valuation.

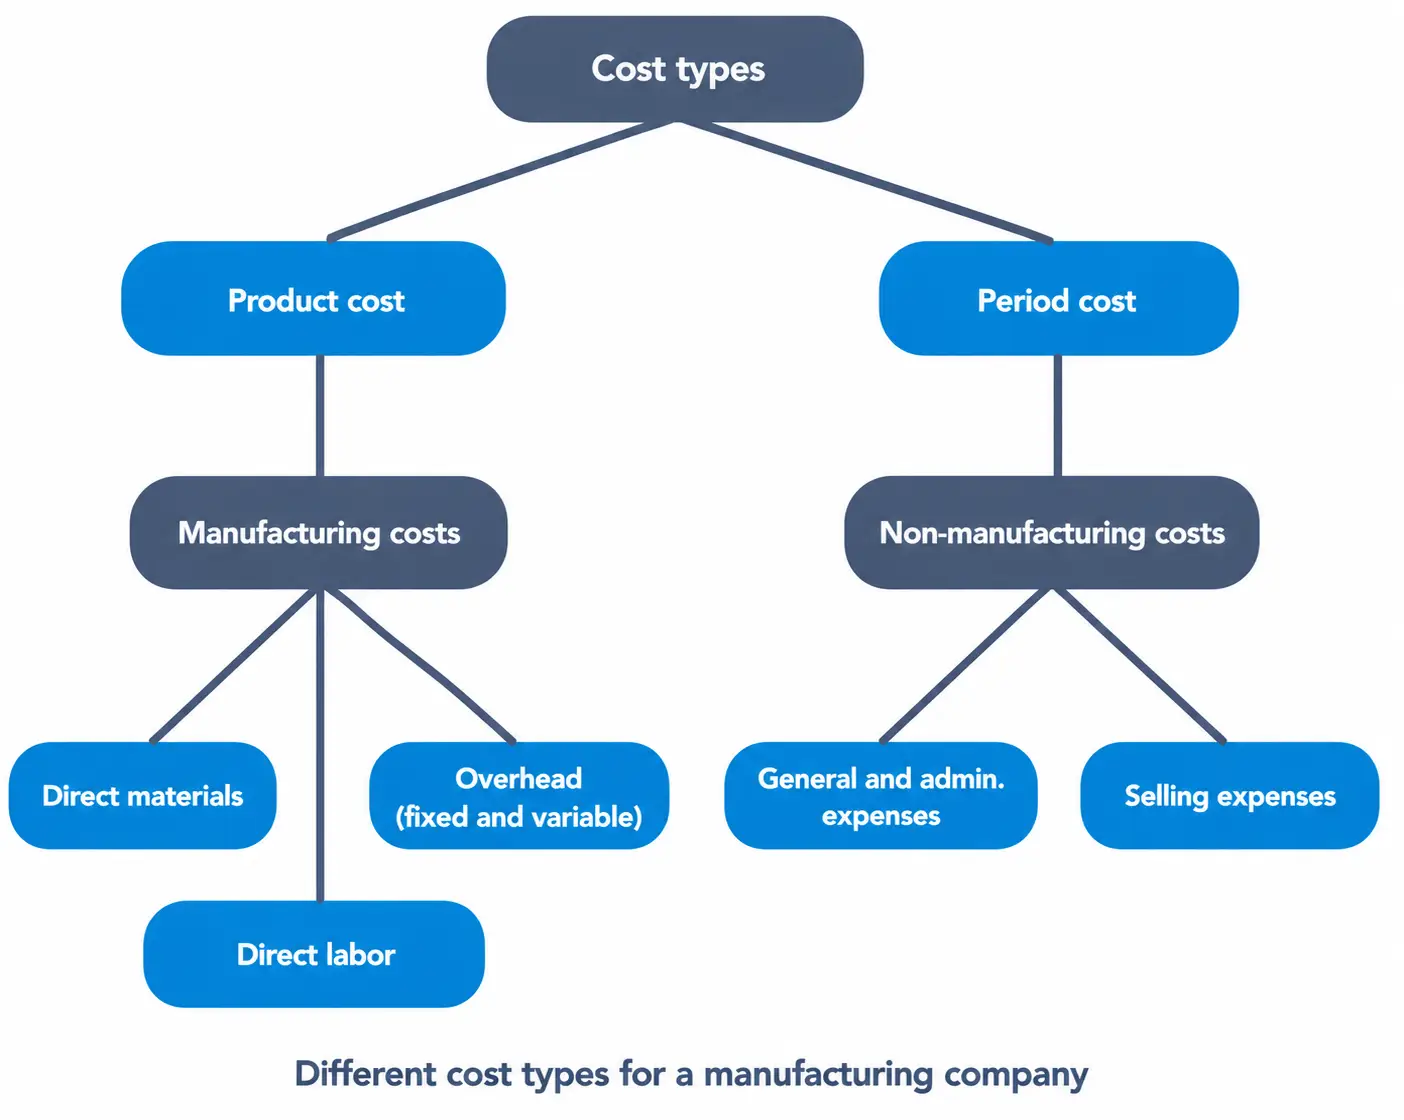
Splitting cost types into product costs and period costs with further subcategories.
Manufacturing Cost Types
Achievable

Product costs

These are costs that are incurred to create a product and are capitalized as inventory on the balance sheet until the product is sold. Once the product is sold, these costs move from inventory to cost of goods sold (COGS) on the income statement. Product costs include:

1. Direct materials

Direct materials are raw materials that can be directly and physically traced to the production of finished goods. They form a fundamental part of the product’s composition and can be measured and assigned to specific cost objects (such as jobs or units) without allocation. Examples include steel in car manufacturing, fabric in clothing production, and flour in bread making.

2. Direct labor

Direct labor refers to the wages, salaries, and related benefits of employees who are directly involved in the manufacturing or production of goods. These are the hands-on workers, such as machine operators, assembly line staff, and bakers, whose efforts can be physically and directly traced to specific units or batches of output.

3. Manufacturing overhead

Manufacturing overhead refers to indirect costs that are incurred in the production process but cannot be directly traced to a specific product, job, or service. These are essential costs that support manufacturing activities but do not become a physical part of the finished product and are not directly involved in the transformation of inputs to outputs. Manufacturing overhead is typically classified into two categories:

  • 3.1. Variable overhead: These costs fluctuate with production volume. Examples include indirect materials (e.g., lubricants, cleaning supplies) and utilities used in the factory. The more you produce, the more variable overhead is incurred.

  • 3.2. Fixed overhead: These costs remain constant within the relevant range of activity, regardless of production levels. Examples include factory rent, depreciation on manufacturing equipment, and salaries of production supervisors. (Fixed overhead is inventoried under absorption costing, which affects reported income differently than variable costing - covered in the absorption vs. variable costing chapter.)

Definitions
Indirect materials
Materials used in the production process that aren’t easily traceable to specific units of output, such as glue or nails.
Indirect labor
Wages paid to workers who support the production process but don’t directly work on manufacturing the product, such as maintenance staff, quality control personnel, or supervisors.

Since overhead cannot be traced directly to cost objects, it must be assigned using cost pools and cost drivers, making it a central focus in cost allocation systems. This distinguishes it from direct materials and direct labor, which are directly assigned without the need for allocation.

Watch out: costs are classified by function, not by type. The same kind of cost - rent, utilities, depreciation, salaries - is a product cost when it’s incurred in the factory and a period cost when it’s incurred in the office. Factory rent, factory utilities, and depreciation on manufacturing equipment are manufacturing overhead (a product cost); office rent, office utilities, and office equipment depreciation are period costs. A sales commission is always a period cost, since selling isn’t a production activity.

Period costs

Period costs are non-manufacturing costs that are expensed in the period incurred. These include:

  • Selling expenses (e.g., sales commissions)
  • Administrative expenses (e.g., office salaries, rent)

These costs are not tied to production and are reported directly in the income statement. Since period costs are expensed as incurred and not associated with production activities, the concepts of cost pools and cost allocation are generally not applied to them.

Cost drivers and causality

Definitions
Cost object
Anything for which cost is separately measured, such as a product, job, department, or customer.
Cost pool
A grouping of individual costs, typically organized by activity or department, that will be assigned to cost objects together.
Cost driver
A factor that causes or relates to a change in cost, such as machine hours, labor hours, or number of setups. Cost drivers link cost pools to cost objects by serving as the allocation basis.
Relevant range
The span of activity levels over which assumptions about cost behavior (such as a cost being fixed or variable) hold true.

A cost driver is used as the allocation basis so that costs are assigned roughly in proportion to resource consumption: if machine hours are the driver, products using more machine time absorb a higher share of the overhead pool. Costs aren’t always purely fixed or variable - a mixed cost has both a fixed and a variable component, like a utility bill with a flat base charge plus a usage-based charge. The overhead classification and cost behavior chapter covers cost behavior in more depth.

Volume-based drivers

Volume-based drivers (units produced, machine hours, direct labor hours) work well when overhead rises mainly with production volume.

For example, in a factory where overhead is driven primarily by machine time or the number of units produced, such as in food processing or bottling, using units produced or machine hours as the cost driver is appropriate and cost-effective.

Activity-based drivers

These are more accurate in complex environments. In service-oriented or multi-product manufacturing settings where costs are incurred by multiple activities that do not scale linearly with volume, activity-based drivers offer a more precise allocation. This concept will be discussed in greater depth in the subsection on Activity-Based Costing. Understanding the causal relationship between activities and costs allows for better cost management, particularly in activity-based costing systems where indirect costs are significant.

For example, in a custom furniture company where some products require design consultations, special tooling, and longer setup times, overhead should be allocated based on activities like number of design hours, setups, or inspections rather than just number of units produced.

Cost measurement techniques

The method an organization chooses to measure and assign costs can significantly impact how inventory is valued, how performance is assessed, and how strategic decisions are made. Each technique has implications for timeliness, accuracy, and the degree of variance analysis that management can perform.

There are three types of cost measurement techniques covered in the CMA Exam:

Technique Material and labor Overhead application
Actual costing Actual Actual
Normal costing Actual Predetermined rate
Standard costing Standard Standard

Example: Applying a predetermined overhead rate

Acme Co. budgets $240,000 of manufacturing overhead and 48,000 machine hours for the year. The predetermined overhead rate is budgeted overhead divided by the budgeted driver: $240,000 ÷ 48,000 machine hours = $5 per machine hour.

Job #12 uses 500 actual machine hours, with actual direct materials and labor of $8,000. Under normal costing, overhead applied to Job #12 is 500 × $5 = $2,500, so total job cost is $8,000 + $2,500 = $10,500.

At year-end, actual overhead comes in at $250,000 while only $235,000 was applied company-wide - overhead is underapplied by $15,000. The overapplied and underapplied overhead chapter covers how this gap gets closed out.

Answer: Overhead applied to Job #12 = $2,500; total job cost = $10,500.

Actual costing

Actual costing assigns actual direct materials, direct labor, and actual overhead to products. It’s precise but not timely, since it requires waiting for period-end cost data - making it best suited to highly customized, low-volume production, regulated industries with mandated cost tracking, or small organizations with simple products that can tolerate the reporting delay.

Benefits:

  • Provides the most accurate reflection of actual resource consumption
  • Generally aligns with financial accounting standards, since both rely on actual costs
  • Useful for post-period analysis and historical costing

Limitations:

  • Requires waiting for actual cost data, which delays reporting
  • Makes budgeting and performance evaluation difficult due to lack of timeliness
  • Inefficient for real-time decision-making or operational control

Normal costing

Normal costing uses actual direct materials and labor but applies overhead using a predetermined rate, balancing accuracy with timeliness. It’s widely used in ongoing manufacturing settings, such as automotive assembly or electronics production, where overhead costs are relatively stable. CMA problems are typically presented to compute using normal costing techniques, unless otherwise stated.

Benefits:

  • Offers a timely view of production costs, enabling faster internal decision-making
  • Simplifies overhead application through the use of a consistent rate
  • Reduces volatility in reported product costs compared to actual costing

Limitations:

  • May result in under- or overapplied overhead, requiring end-of-period adjustments
  • Less precise than actual costing for performance measurement
  • Relies on accurate budgeting and forecasting of overhead and activity bases

Standard costing

Standard costing uses predetermined amounts for all cost elements, and variances between standard and actual costs are analyzed for performance evaluation. It suits organizations with repetitive production processes and stable cost structures, such as assembly-line or mass-production manufacturing, where variance analysis supports budgeting and control.

Benefits:

  • Facilitates budgeting and planning through consistent cost benchmarks
  • Enables performance evaluation via variance analysis
  • Supports timely cost reporting and control

Limitations:

  • Requires regular updates to remain relevant and reflective of actual operations
  • May cause misleading decisions if variances are not properly interpreted
  • Less flexible in environments with frequent process or cost structure changes

Product costs

  • Incurred to make a product; capitalized as inventory, moved to COGS when sold
  • Three components: direct materials (directly traceable raw materials), direct labor (wages of hands-on production workers), manufacturing overhead (indirect production costs)
  • Overhead splits into variable (fluctuates with volume, e.g., indirect materials/utilities) and fixed (constant within relevant range, e.g., factory rent, depreciation, supervisor salaries)
  • Indirect materials/labor can’t be traced to specific units (glue, maintenance staff, QC)
  • Classification is by function, not cost type: same cost type (rent, utilities, depreciation) is product cost if factory-related, period cost if office-related; sales commissions always period costs

Period costs

  • Non-manufacturing costs expensed in period incurred (selling & admin expenses)
  • Not tied to production; reported directly on income statement
  • Cost pools/allocation generally not applied to these

Cost drivers and causality

  • Key terms: cost object (thing being costed), cost pool (grouped costs), cost driver (allocation basis linking pools to objects), relevant range (span where cost behavior assumptions hold)
  • Mixed costs have both fixed and variable components (e.g., utility bill)
  • Volume-based drivers (machine hours, units, labor hours) work when overhead scales with production volume (e.g., bottling)
  • Activity-based drivers more accurate in complex/multi-product settings where costs don’t scale linearly (e.g., custom furniture: design hours, setups, inspections)

Cost measurement techniques

  • Three techniques differ in how material/labor and overhead are measured:
    • Actual costing: actual materials, labor, and overhead — most accurate but slow; best for custom/low-volume or regulated production
    • Normal costing: actual materials/labor + predetermined overhead rate — balances timeliness and accuracy; default assumption on CMA exam unless stated otherwise
    • Standard costing: predetermined amounts for all cost elements — supports budgeting and variance analysis; best for repetitive, stable production
  • Predetermined overhead rate formula: rate=budgeted driver activitybudgeted overhead​
    • Example: $240,000÷48,000 MH=$5/MH; applied overhead = rate × actual driver usage
  • Under/overapplied overhead = difference between actual overhead incurred and overhead applied using predetermined rate (resolved at year-end, covered in later chapter)

Sign up for free to take 10 quiz questions on this topic

Previous
Next  | 4.1.3 Inventory cost flow: trading vs. manufacturing
All rights reserved ©2016 - 2026 Achievable, Inc.

Product and period costs, cost drivers, and cost measurement methods

Product costs vs. period costs

In understanding cost classification, it’s important to distinguish between product costs and period costs, especially in the context of cost accumulation and inventory valuation.

Product costs

These are costs that are incurred to create a product and are capitalized as inventory on the balance sheet until the product is sold. Once the product is sold, these costs move from inventory to cost of goods sold (COGS) on the income statement. Product costs include:

1. Direct materials

Direct materials are raw materials that can be directly and physically traced to the production of finished goods. They form a fundamental part of the product’s composition and can be measured and assigned to specific cost objects (such as jobs or units) without allocation. Examples include steel in car manufacturing, fabric in clothing production, and flour in bread making.

2. Direct labor

Direct labor refers to the wages, salaries, and related benefits of employees who are directly involved in the manufacturing or production of goods. These are the hands-on workers, such as machine operators, assembly line staff, and bakers, whose efforts can be physically and directly traced to specific units or batches of output.

3. Manufacturing overhead

Manufacturing overhead refers to indirect costs that are incurred in the production process but cannot be directly traced to a specific product, job, or service. These are essential costs that support manufacturing activities but do not become a physical part of the finished product and are not directly involved in the transformation of inputs to outputs. Manufacturing overhead is typically classified into two categories:

  • 3.1. Variable overhead: These costs fluctuate with production volume. Examples include indirect materials (e.g., lubricants, cleaning supplies) and utilities used in the factory. The more you produce, the more variable overhead is incurred.

  • 3.2. Fixed overhead: These costs remain constant within the relevant range of activity, regardless of production levels. Examples include factory rent, depreciation on manufacturing equipment, and salaries of production supervisors. (Fixed overhead is inventoried under absorption costing, which affects reported income differently than variable costing - covered in the absorption vs. variable costing chapter.)

Definitions
Indirect materials
Materials used in the production process that aren’t easily traceable to specific units of output, such as glue or nails.
Indirect labor
Wages paid to workers who support the production process but don’t directly work on manufacturing the product, such as maintenance staff, quality control personnel, or supervisors.

Since overhead cannot be traced directly to cost objects, it must be assigned using cost pools and cost drivers, making it a central focus in cost allocation systems. This distinguishes it from direct materials and direct labor, which are directly assigned without the need for allocation.

Watch out: costs are classified by function, not by type. The same kind of cost - rent, utilities, depreciation, salaries - is a product cost when it’s incurred in the factory and a period cost when it’s incurred in the office. Factory rent, factory utilities, and depreciation on manufacturing equipment are manufacturing overhead (a product cost); office rent, office utilities, and office equipment depreciation are period costs. A sales commission is always a period cost, since selling isn’t a production activity.

Period costs

Period costs are non-manufacturing costs that are expensed in the period incurred. These include:

  • Selling expenses (e.g., sales commissions)
  • Administrative expenses (e.g., office salaries, rent)

These costs are not tied to production and are reported directly in the income statement. Since period costs are expensed as incurred and not associated with production activities, the concepts of cost pools and cost allocation are generally not applied to them.

Cost drivers and causality

Definitions
Cost object
Anything for which cost is separately measured, such as a product, job, department, or customer.
Cost pool
A grouping of individual costs, typically organized by activity or department, that will be assigned to cost objects together.
Cost driver
A factor that causes or relates to a change in cost, such as machine hours, labor hours, or number of setups. Cost drivers link cost pools to cost objects by serving as the allocation basis.
Relevant range
The span of activity levels over which assumptions about cost behavior (such as a cost being fixed or variable) hold true.

A cost driver is used as the allocation basis so that costs are assigned roughly in proportion to resource consumption: if machine hours are the driver, products using more machine time absorb a higher share of the overhead pool. Costs aren’t always purely fixed or variable - a mixed cost has both a fixed and a variable component, like a utility bill with a flat base charge plus a usage-based charge. The overhead classification and cost behavior chapter covers cost behavior in more depth.

Volume-based drivers

Volume-based drivers (units produced, machine hours, direct labor hours) work well when overhead rises mainly with production volume.

For example, in a factory where overhead is driven primarily by machine time or the number of units produced, such as in food processing or bottling, using units produced or machine hours as the cost driver is appropriate and cost-effective.

Activity-based drivers

These are more accurate in complex environments. In service-oriented or multi-product manufacturing settings where costs are incurred by multiple activities that do not scale linearly with volume, activity-based drivers offer a more precise allocation. This concept will be discussed in greater depth in the subsection on Activity-Based Costing. Understanding the causal relationship between activities and costs allows for better cost management, particularly in activity-based costing systems where indirect costs are significant.

For example, in a custom furniture company where some products require design consultations, special tooling, and longer setup times, overhead should be allocated based on activities like number of design hours, setups, or inspections rather than just number of units produced.

Cost measurement techniques

The method an organization chooses to measure and assign costs can significantly impact how inventory is valued, how performance is assessed, and how strategic decisions are made. Each technique has implications for timeliness, accuracy, and the degree of variance analysis that management can perform.

There are three types of cost measurement techniques covered in the CMA Exam:

Technique Material and labor Overhead application
Actual costing Actual Actual
Normal costing Actual Predetermined rate
Standard costing Standard Standard

Example: Applying a predetermined overhead rate

Acme Co. budgets $240,000 of manufacturing overhead and 48,000 machine hours for the year. The predetermined overhead rate is budgeted overhead divided by the budgeted driver: $240,000 ÷ 48,000 machine hours = $5 per machine hour.

Job #12 uses 500 actual machine hours, with actual direct materials and labor of $8,000. Under normal costing, overhead applied to Job #12 is 500 × $5 = $2,500, so total job cost is $8,000 + $2,500 = $10,500.

At year-end, actual overhead comes in at $250,000 while only $235,000 was applied company-wide - overhead is underapplied by $15,000. The overapplied and underapplied overhead chapter covers how this gap gets closed out.

Answer: Overhead applied to Job #12 = $2,500; total job cost = $10,500.

Actual costing

Actual costing assigns actual direct materials, direct labor, and actual overhead to products. It’s precise but not timely, since it requires waiting for period-end cost data - making it best suited to highly customized, low-volume production, regulated industries with mandated cost tracking, or small organizations with simple products that can tolerate the reporting delay.

Benefits:

  • Provides the most accurate reflection of actual resource consumption
  • Generally aligns with financial accounting standards, since both rely on actual costs
  • Useful for post-period analysis and historical costing

Limitations:

  • Requires waiting for actual cost data, which delays reporting
  • Makes budgeting and performance evaluation difficult due to lack of timeliness
  • Inefficient for real-time decision-making or operational control

Normal costing

Normal costing uses actual direct materials and labor but applies overhead using a predetermined rate, balancing accuracy with timeliness. It’s widely used in ongoing manufacturing settings, such as automotive assembly or electronics production, where overhead costs are relatively stable. CMA problems are typically presented to compute using normal costing techniques, unless otherwise stated.

Benefits:

  • Offers a timely view of production costs, enabling faster internal decision-making
  • Simplifies overhead application through the use of a consistent rate
  • Reduces volatility in reported product costs compared to actual costing

Limitations:

  • May result in under- or overapplied overhead, requiring end-of-period adjustments
  • Less precise than actual costing for performance measurement
  • Relies on accurate budgeting and forecasting of overhead and activity bases

Standard costing

Standard costing uses predetermined amounts for all cost elements, and variances between standard and actual costs are analyzed for performance evaluation. It suits organizations with repetitive production processes and stable cost structures, such as assembly-line or mass-production manufacturing, where variance analysis supports budgeting and control.

Benefits:

  • Facilitates budgeting and planning through consistent cost benchmarks
  • Enables performance evaluation via variance analysis
  • Supports timely cost reporting and control

Limitations:

  • Requires regular updates to remain relevant and reflective of actual operations
  • May cause misleading decisions if variances are not properly interpreted
  • Less flexible in environments with frequent process or cost structure changes
Key points

Product costs

  • Incurred to make a product; capitalized as inventory, moved to COGS when sold
  • Three components: direct materials (directly traceable raw materials), direct labor (wages of hands-on production workers), manufacturing overhead (indirect production costs)
  • Overhead splits into variable (fluctuates with volume, e.g., indirect materials/utilities) and fixed (constant within relevant range, e.g., factory rent, depreciation, supervisor salaries)
  • Indirect materials/labor can’t be traced to specific units (glue, maintenance staff, QC)
  • Classification is by function, not cost type: same cost type (rent, utilities, depreciation) is product cost if factory-related, period cost if office-related; sales commissions always period costs

Period costs

  • Non-manufacturing costs expensed in period incurred (selling & admin expenses)
  • Not tied to production; reported directly on income statement
  • Cost pools/allocation generally not applied to these

Cost drivers and causality

  • Key terms: cost object (thing being costed), cost pool (grouped costs), cost driver (allocation basis linking pools to objects), relevant range (span where cost behavior assumptions hold)
  • Mixed costs have both fixed and variable components (e.g., utility bill)
  • Volume-based drivers (machine hours, units, labor hours) work when overhead scales with production volume (e.g., bottling)
  • Activity-based drivers more accurate in complex/multi-product settings where costs don’t scale linearly (e.g., custom furniture: design hours, setups, inspections)

Cost measurement techniques

  • Three techniques differ in how material/labor and overhead are measured:
    • Actual costing: actual materials, labor, and overhead — most accurate but slow; best for custom/low-volume or regulated production
    • Normal costing: actual materials/labor + predetermined overhead rate — balances timeliness and accuracy; default assumption on CMA exam unless stated otherwise
    • Standard costing: predetermined amounts for all cost elements — supports budgeting and variance analysis; best for repetitive, stable production
  • Predetermined overhead rate formula: rate=budgeted driver activitybudgeted overhead​
    • Example: $240,000÷48,000 MH=$5/MH; applied overhead = rate × actual driver usage
  • Under/overapplied overhead = difference between actual overhead incurred and overhead applied using predetermined rate (resolved at year-end, covered in later chapter)

More from Measurement concepts

  • Cost behavior, cost objects, and cost pools
  • Inventory cost flow: trading vs. manufacturing
  • Absorption vs. variable costing: impact on inventory and income
  • Absorption vs. variable costing: illustrative problem
  • Joint and by-product costing: key concepts