


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
CMA Part 1
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. External financial reporting decisions
2. Planning, budgeting, and forecasting
3. Performance management
4. Cost management
4.1 Measurement concepts
4.1.1 Cost behavior, cost objects, and cost pools
4.1.2 Product and period costs, cost drivers, and cost measurement methods
4.1.3 Inventory cost flow: trading vs. manufacturing
4.1.4 Absorption vs. variable costing: impact on inventory and income
4.1.5 Absorption vs. variable costing: illustrative problem
4.1.6 Joint and by-product costing: key concepts
4.1.7 Joint and by-product costing: cost allocation methods and by-product costing
4.2 Costing systems
4.3 Overhead costs
4.4 Supply chain management
4.5 Business process improvement
5. Internal control
6. Technology and analytics
Wrapping up
Achievable logoAchievable logo
4.1.1 Cost behavior, cost objects, and cost pools
Achievable CMA Part 1
4. Cost management
4.1. Measurement concepts
Our CMA Part 1 course is currently in development and is a work-in-progress.

Cost behavior, cost objects, and cost pools

8 min read
Font
Discuss
Share
Feedback

Learning outcome statements

The learning outcome statements relevant for this section are:

  1. calculate fixed, variable, and mixed costs, and demonstrate an understanding of the behavior of each in the long and short term and how a change in assumptions regarding cost type or relevant range affects these costs
  2. identify cost objects and cost pools, and assign costs to appropriate activities

Cost drivers, work-in-process and finished goods accumulation, and actual/normal/standard costing methods are covered in the next measurement concepts chapter, product and period costs, cost drivers, and cost measurement methods.

Cost classification and behavior

Cost behavior refers to how a cost changes in response to variations in activity levels. Understanding cost behavior is essential for managers to predict future costs and make informed decisions. Costs can be classified based on behavior, traceability, and function. The behavioral classification is especially useful for planning, budgeting, and decision-making.

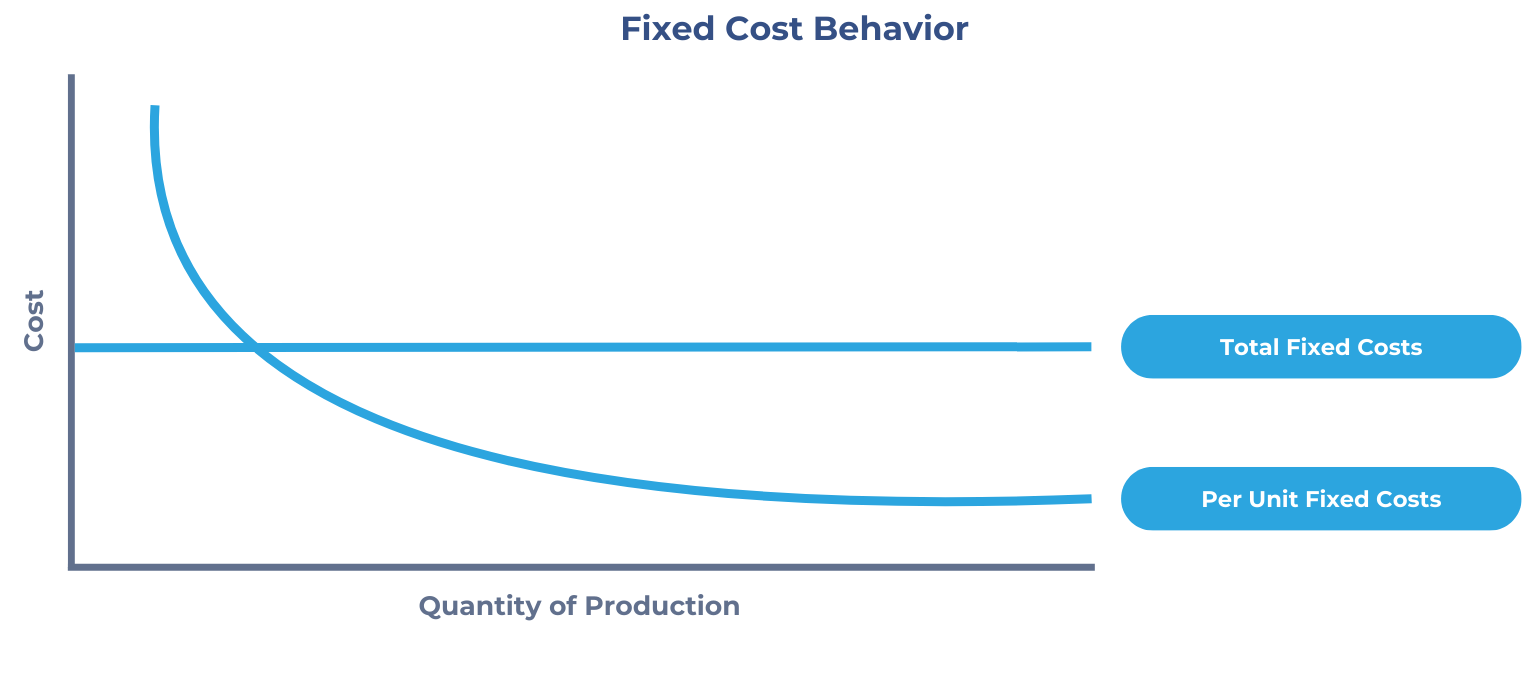
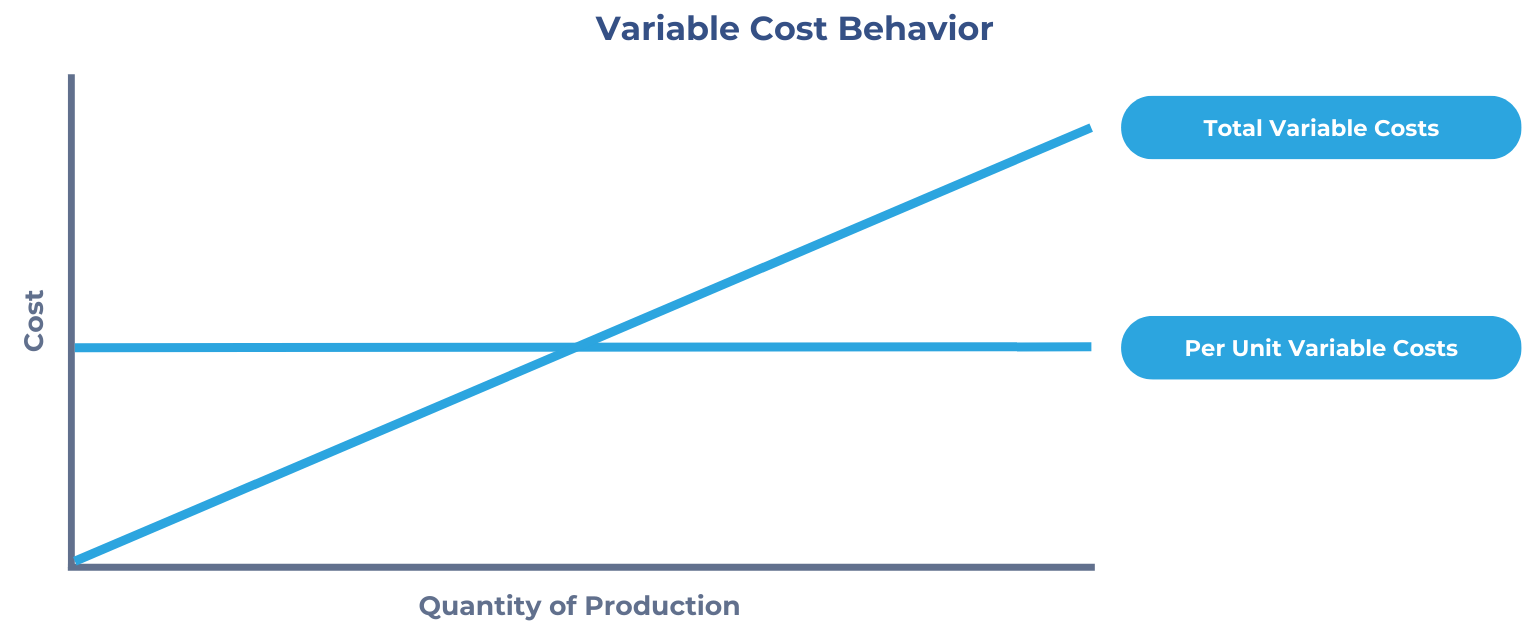
When analyzing cost behavior, it is important to distinguish between how costs behave in total versus how they behave on a per-unit basis.

Pitfall: fixed cost per unit falls as volume rises, even though total fixed cost doesn’t change. Treating a unitized fixed cost as if it stays constant can make per-unit costs look artificially low or high when activity shifts - a common source of error when comparing costs across activity levels, and a preview of the absorption-costing issues covered later.

Definitions
Fixed cost
A cost that remains unchanged in total regardless of the level of activity, within the relevant range. On a per-unit basis, fixed cost decreases as activity increases, because the same total is spread over more units.
Variable cost
A cost that varies directly and proportionately with activity level. Total variable cost rises as more units are produced, while variable cost per unit stays constant.
Mixed cost
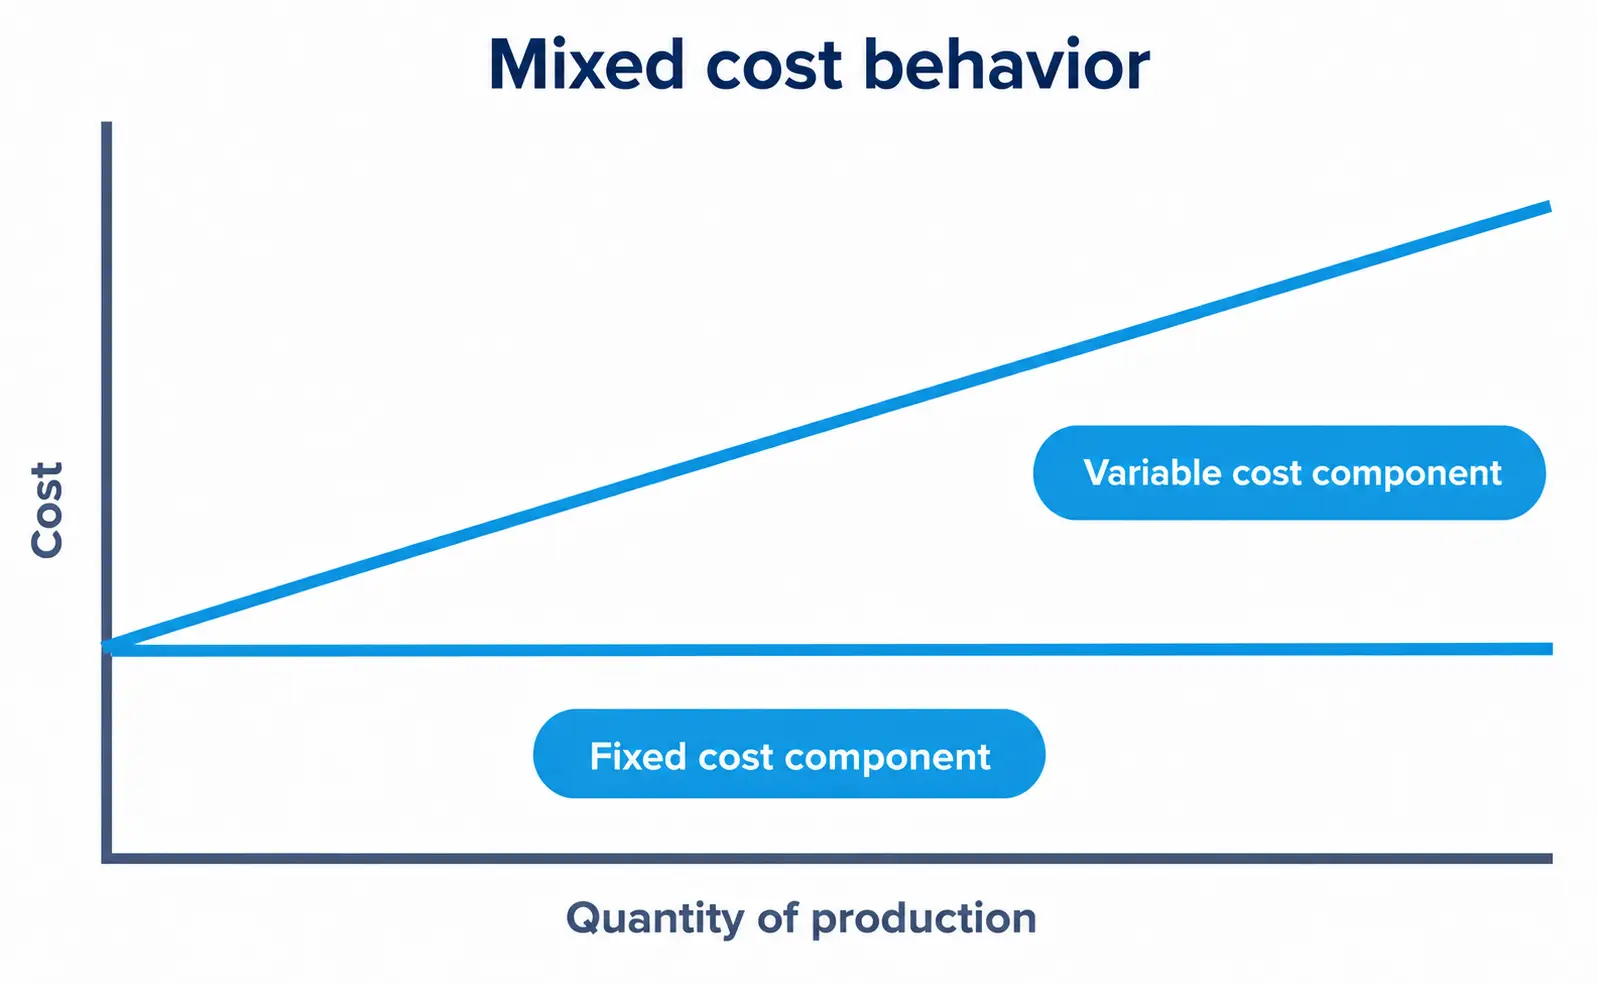
A cost that contains both fixed and variable components. Total mixed cost rises with activity but not proportionally, because the fixed component is incurred even at zero activity. Within the relevant range, it can be expressed as:

Total cost=Fixed cost+(Variable cost per unit×Activity)

A classic example is a utility bill: there is a base service fee (fixed) that must be paid regardless of usage, and a variable component that increases based on actual electricity or water consumption.

Mixed costs are also known as semi-variable or semi-fixed costs. To analyze them effectively, companies often separate the fixed and variable components using techniques such as the high-low method or regression analysis.

Fixed cost behavior illustration
Achievable
Variable cost behavior illustration
Achievable
Showing mixed cost as a rising variable component on top of a flat fixed cost component.
Mixed Cost Behavior
Achievable

Example: Separating a mixed cost (high-low method)

A company’s factory overhead was $26,000 at 4,000 machine hours (the low point) and $50,000 at 10,000 machine hours (the high point). Use the high-low method to split this mixed cost into its fixed and variable components, then estimate the cost at 7,000 hours.

  • Variable cost per hour: 10,000−4,000$50,000−$26,000​=6,000$24,000​=$4 per hour
  • Fixed cost: $26,000−($4×4,000)=$26,000−$16,000=$10,000
  • Estimated cost at 7,000 hours: $10,000+($4×7,000)=$10,000+$28,000=$38,000

Notice that the $10,000 fixed cost is the same at both activity levels, but its per-unit amount falls from $2.50 per hour at 4,000 hours ($10,000÷4,000) to $1.00 per hour at 10,000 hours ($10,000÷10,000) - fixed cost per unit shrinks as volume rises, even though total fixed cost doesn’t change.

Answer: Variable cost = $4 per hour; fixed cost = $10,000; estimated cost at 7,000 hours = $38,000

Cost behavior can vary between the short term and long term, which significantly impacts decision-making. In the short term, some costs are often fixed due to contractual obligations or capacity limitations. For example, rental payments or salaried labor may not change even if production increases or decreases within a short period.

In the long term, however, most costs become more variable. Contracts may be renegotiated, operations can be scaled, and labor structures can be altered. This flexibility allows managers to adjust costs in response to strategic goals or changes in market demand.

For example, a factory lease is considered fixed over a one-year period because the terms are locked in, but in the long term, the lease can be renegotiated, terminated, or replaced by a different facility, making the cost variable from a strategic perspective.

Definitions
Relevant range
The level of activity within which cost assumptions remain valid. Outside this range, cost behavior may shift, leading to step costs or changes in fixed or variable classifications.

An example of relevant range is when a factory may operate efficiently between 10,000 to 20,000 units of production. Within this range, fixed costs like rent remain unchanged, and variable costs per unit stay constant. However, if production exceeds 20,000 units, the company might need to rent additional space or hire another supervisor, increasing fixed costs. Alternatively, if production drops below 10,000 units, equipment may be underutilized, leading to inefficiencies and altered cost behavior.

A step cost stays constant over a band of activity, then jumps to a new level once activity crosses a threshold - unlike a mixed cost, which rises continuously with activity. Hiring a second supervisor once production exceeds 20,000 units is an example of a step cost.

Cost objects and cost pools

Understanding the distinction between cost objects and cost pools is foundational to effective cost allocation and managerial decision-making. In any organization, it is important to know where costs are incurred and how they should be assigned. This allows managers to better control costs, assess departmental performance, price products appropriately, and allocate overhead costs fairly across different segments of the business.

Definitions
Cost object
Any item for which a separate cost measurement is desired. Common examples include a product, department, service line, customer, or project. For example, in a furniture company, each type of furniture (chairs, tables, or desks) may be treated as a separate cost object.
Cost pool
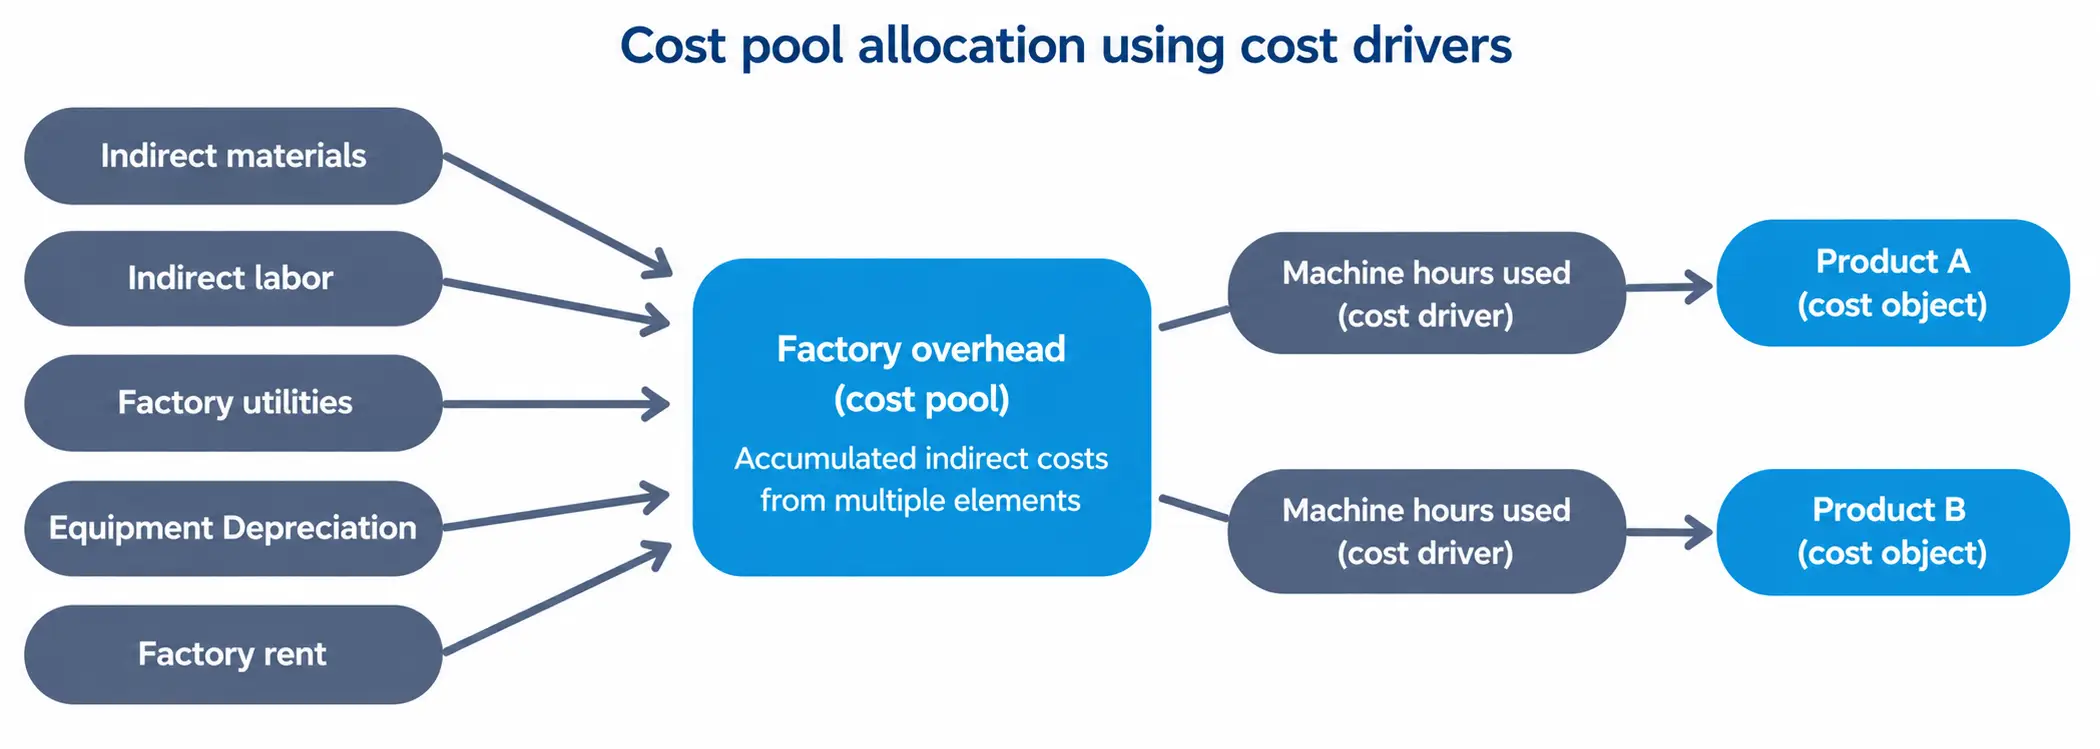
A collection or grouping of individual cost elements that relate to a specific activity, department, or function. For example, all electricity, maintenance, and depreciation costs of a manufacturing facility might be grouped into a single “factory overhead” cost pool.
Showing indirect costs flowing into a factory overhead cost pool then allocated to two products by machine hours.
Cost Pool Allocation
Achievable

Accurate assignment of costs to cost objects via cost pools supports effective costing systems and internal control. This process enables better budgeting, pricing decisions, and profitability analysis. For instance, utility and supervisory labor costs from the factory cost pool might be allocated to individual products based on machine hours or labor hours used.

This concept becomes especially relevant when dealing with indirect costs, such as overhead, that cannot be traced directly to a single item. While direct materials and direct labor can be directly traced to a product or job, overhead costs must be distributed using cost pools and allocated to cost objects based on appropriate drivers. This is why identifying cost objects and establishing cost pools is critical for accurate product costing, especially in complex or multi-product environments.

Cost behavior basics

  • Fixed cost: total constant within relevant range; per-unit falls as volume rises
  • Variable cost: total changes proportionally with activity; per-unit constant
  • Mixed (semi-variable) cost: has fixed + variable parts; formula: Total cost=Fixed cost+(Variable cost per unit×Activity)
  • Pitfall: don’t treat per-unit fixed cost as constant across activity levels — it shrinks as volume rises

Separating mixed costs (high-low method)

  • Variable rate = Activityhigh​−Activitylow​Costhigh​−Costlow​​
  • Fixed cost = Total cost at one point − (Variable rate × Activity at that point)
  • Use formula to estimate cost at any activity level within relevant range
  • Other separation technique: regression analysis

Short-term vs. long-term cost behavior

  • Short term: costs often fixed (contracts, capacity limits) — e.g., rent, salaries
  • Long term: most costs become variable/adjustable — contracts renegotiated, operations scaled
  • Same cost (e.g., lease) can be fixed short-term but variable long-term strategically

Relevant range and step costs

  • Relevant range: activity band where cost behavior assumptions (fixed/variable) hold true
  • Outside relevant range, costs may shift (new fixed costs, different variable rates)
  • Step cost: stays flat over a range, then jumps at a threshold (unlike mixed cost’s continuous rise) — e.g., hiring added supervisor past a production threshold

Cost objects and cost pools

  • Cost object: anything needing separate cost measurement (product, department, customer, project)
  • Cost pool: grouping of related indirect costs (e.g., factory overhead: utilities, maintenance, depreciation)
  • Indirect/overhead costs can’t be traced directly — must be grouped into pools and allocated to cost objects using drivers (e.g., machine hours, labor hours)
  • Direct materials/labor trace directly; overhead requires pooling and allocation — key for accurate product costing

Sign up for free to take 10 quiz questions on this topic

Previous
Next  | 4.1.2 Product and period costs, cost drivers, and cost measurement methods
All rights reserved ©2016 - 2026 Achievable, Inc.

Cost behavior, cost objects, and cost pools

Learning outcome statements

The learning outcome statements relevant for this section are:

  1. calculate fixed, variable, and mixed costs, and demonstrate an understanding of the behavior of each in the long and short term and how a change in assumptions regarding cost type or relevant range affects these costs
  2. identify cost objects and cost pools, and assign costs to appropriate activities

Cost drivers, work-in-process and finished goods accumulation, and actual/normal/standard costing methods are covered in the next measurement concepts chapter, product and period costs, cost drivers, and cost measurement methods.

Cost classification and behavior

Cost behavior refers to how a cost changes in response to variations in activity levels. Understanding cost behavior is essential for managers to predict future costs and make informed decisions. Costs can be classified based on behavior, traceability, and function. The behavioral classification is especially useful for planning, budgeting, and decision-making.

When analyzing cost behavior, it is important to distinguish between how costs behave in total versus how they behave on a per-unit basis.

Pitfall: fixed cost per unit falls as volume rises, even though total fixed cost doesn’t change. Treating a unitized fixed cost as if it stays constant can make per-unit costs look artificially low or high when activity shifts - a common source of error when comparing costs across activity levels, and a preview of the absorption-costing issues covered later.

Definitions
Fixed cost
A cost that remains unchanged in total regardless of the level of activity, within the relevant range. On a per-unit basis, fixed cost decreases as activity increases, because the same total is spread over more units.
Variable cost
A cost that varies directly and proportionately with activity level. Total variable cost rises as more units are produced, while variable cost per unit stays constant.
Mixed cost
A cost that contains both fixed and variable components. Total mixed cost rises with activity but not proportionally, because the fixed component is incurred even at zero activity. Within the relevant range, it can be expressed as:

Total cost=Fixed cost+(Variable cost per unit×Activity)

A classic example is a utility bill: there is a base service fee (fixed) that must be paid regardless of usage, and a variable component that increases based on actual electricity or water consumption.

Mixed costs are also known as semi-variable or semi-fixed costs. To analyze them effectively, companies often separate the fixed and variable components using techniques such as the high-low method or regression analysis.

Example: Separating a mixed cost (high-low method)

A company’s factory overhead was $26,000 at 4,000 machine hours (the low point) and $50,000 at 10,000 machine hours (the high point). Use the high-low method to split this mixed cost into its fixed and variable components, then estimate the cost at 7,000 hours.

  • Variable cost per hour: 10,000−4,000$50,000−$26,000​=6,000$24,000​=$4 per hour
  • Fixed cost: $26,000−($4×4,000)=$26,000−$16,000=$10,000
  • Estimated cost at 7,000 hours: $10,000+($4×7,000)=$10,000+$28,000=$38,000

Notice that the $10,000 fixed cost is the same at both activity levels, but its per-unit amount falls from $2.50 per hour at 4,000 hours ($10,000÷4,000) to $1.00 per hour at 10,000 hours ($10,000÷10,000) - fixed cost per unit shrinks as volume rises, even though total fixed cost doesn’t change.

Answer: Variable cost = $4 per hour; fixed cost = $10,000; estimated cost at 7,000 hours = $38,000

Cost behavior can vary between the short term and long term, which significantly impacts decision-making. In the short term, some costs are often fixed due to contractual obligations or capacity limitations. For example, rental payments or salaried labor may not change even if production increases or decreases within a short period.

In the long term, however, most costs become more variable. Contracts may be renegotiated, operations can be scaled, and labor structures can be altered. This flexibility allows managers to adjust costs in response to strategic goals or changes in market demand.

For example, a factory lease is considered fixed over a one-year period because the terms are locked in, but in the long term, the lease can be renegotiated, terminated, or replaced by a different facility, making the cost variable from a strategic perspective.

Definitions
Relevant range
The level of activity within which cost assumptions remain valid. Outside this range, cost behavior may shift, leading to step costs or changes in fixed or variable classifications.

An example of relevant range is when a factory may operate efficiently between 10,000 to 20,000 units of production. Within this range, fixed costs like rent remain unchanged, and variable costs per unit stay constant. However, if production exceeds 20,000 units, the company might need to rent additional space or hire another supervisor, increasing fixed costs. Alternatively, if production drops below 10,000 units, equipment may be underutilized, leading to inefficiencies and altered cost behavior.

A step cost stays constant over a band of activity, then jumps to a new level once activity crosses a threshold - unlike a mixed cost, which rises continuously with activity. Hiring a second supervisor once production exceeds 20,000 units is an example of a step cost.

Cost objects and cost pools

Understanding the distinction between cost objects and cost pools is foundational to effective cost allocation and managerial decision-making. In any organization, it is important to know where costs are incurred and how they should be assigned. This allows managers to better control costs, assess departmental performance, price products appropriately, and allocate overhead costs fairly across different segments of the business.

Definitions
Cost object
Any item for which a separate cost measurement is desired. Common examples include a product, department, service line, customer, or project. For example, in a furniture company, each type of furniture (chairs, tables, or desks) may be treated as a separate cost object.
Cost pool
A collection or grouping of individual cost elements that relate to a specific activity, department, or function. For example, all electricity, maintenance, and depreciation costs of a manufacturing facility might be grouped into a single “factory overhead” cost pool.

Accurate assignment of costs to cost objects via cost pools supports effective costing systems and internal control. This process enables better budgeting, pricing decisions, and profitability analysis. For instance, utility and supervisory labor costs from the factory cost pool might be allocated to individual products based on machine hours or labor hours used.

This concept becomes especially relevant when dealing with indirect costs, such as overhead, that cannot be traced directly to a single item. While direct materials and direct labor can be directly traced to a product or job, overhead costs must be distributed using cost pools and allocated to cost objects based on appropriate drivers. This is why identifying cost objects and establishing cost pools is critical for accurate product costing, especially in complex or multi-product environments.

Key points

Cost behavior basics

  • Fixed cost: total constant within relevant range; per-unit falls as volume rises
  • Variable cost: total changes proportionally with activity; per-unit constant
  • Mixed (semi-variable) cost: has fixed + variable parts; formula: Total cost=Fixed cost+(Variable cost per unit×Activity)
  • Pitfall: don’t treat per-unit fixed cost as constant across activity levels — it shrinks as volume rises

Separating mixed costs (high-low method)

  • Variable rate = Activityhigh​−Activitylow​Costhigh​−Costlow​​
  • Fixed cost = Total cost at one point − (Variable rate × Activity at that point)
  • Use formula to estimate cost at any activity level within relevant range
  • Other separation technique: regression analysis

Short-term vs. long-term cost behavior

  • Short term: costs often fixed (contracts, capacity limits) — e.g., rent, salaries
  • Long term: most costs become variable/adjustable — contracts renegotiated, operations scaled
  • Same cost (e.g., lease) can be fixed short-term but variable long-term strategically

Relevant range and step costs

  • Relevant range: activity band where cost behavior assumptions (fixed/variable) hold true
  • Outside relevant range, costs may shift (new fixed costs, different variable rates)
  • Step cost: stays flat over a range, then jumps at a threshold (unlike mixed cost’s continuous rise) — e.g., hiring added supervisor past a production threshold

Cost objects and cost pools

  • Cost object: anything needing separate cost measurement (product, department, customer, project)
  • Cost pool: grouping of related indirect costs (e.g., factory overhead: utilities, maintenance, depreciation)
  • Indirect/overhead costs can’t be traced directly — must be grouped into pools and allocated to cost objects using drivers (e.g., machine hours, labor hours)
  • Direct materials/labor trace directly; overhead requires pooling and allocation — key for accurate product costing

More from Measurement concepts

  • Product and period costs, cost drivers, and cost measurement methods
  • Inventory cost flow: trading vs. manufacturing
  • Absorption vs. variable costing: impact on inventory and income
  • Absorption vs. variable costing: illustrative problem
  • Joint and by-product costing: key concepts