



Inventory cost flow: trading vs. manufacturing
Flow of inventory
There are two types of companies typically presented in the CMA examinations, trading and manufacturing, although in practice there are now different types of organizations and even hybrid ones.
Trading companies
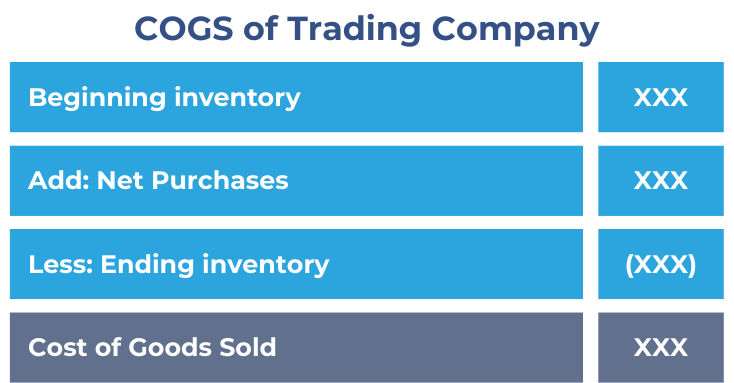
For trading companies, the focus of cost accumulation is simpler than in manufacturing because there is no production process involved. Instead, inventory typically consists of purchased finished goods that are held for resale without any additional processing.
Inventory consists of merchandise held for resale, and cost flow is primarily affected by the inventory system used: either perpetual or periodic. As discussed in previous chapters, these systems determine when and how inventory and COGS are recorded.
While cost accumulation systems like job order or process costing are not applicable, trading companies still use inventory valuation methods such as FIFO, LIFO, or weighted average to determine the cost assigned to COGS. (LIFO is permitted under U.S. GAAP but prohibited under IFRS.)
The main objective is to track the cost of inventory purchases and determine the cost of goods sold (COGS) when sales occur. The inventory flow for trading businesses usually involves just two key accounts:
Manufacturing companies
For manufacturing companies, we focus on the systematic accumulation of costs to accurately value inventory and determine the cost of goods sold (COGS) and the various inventory items.
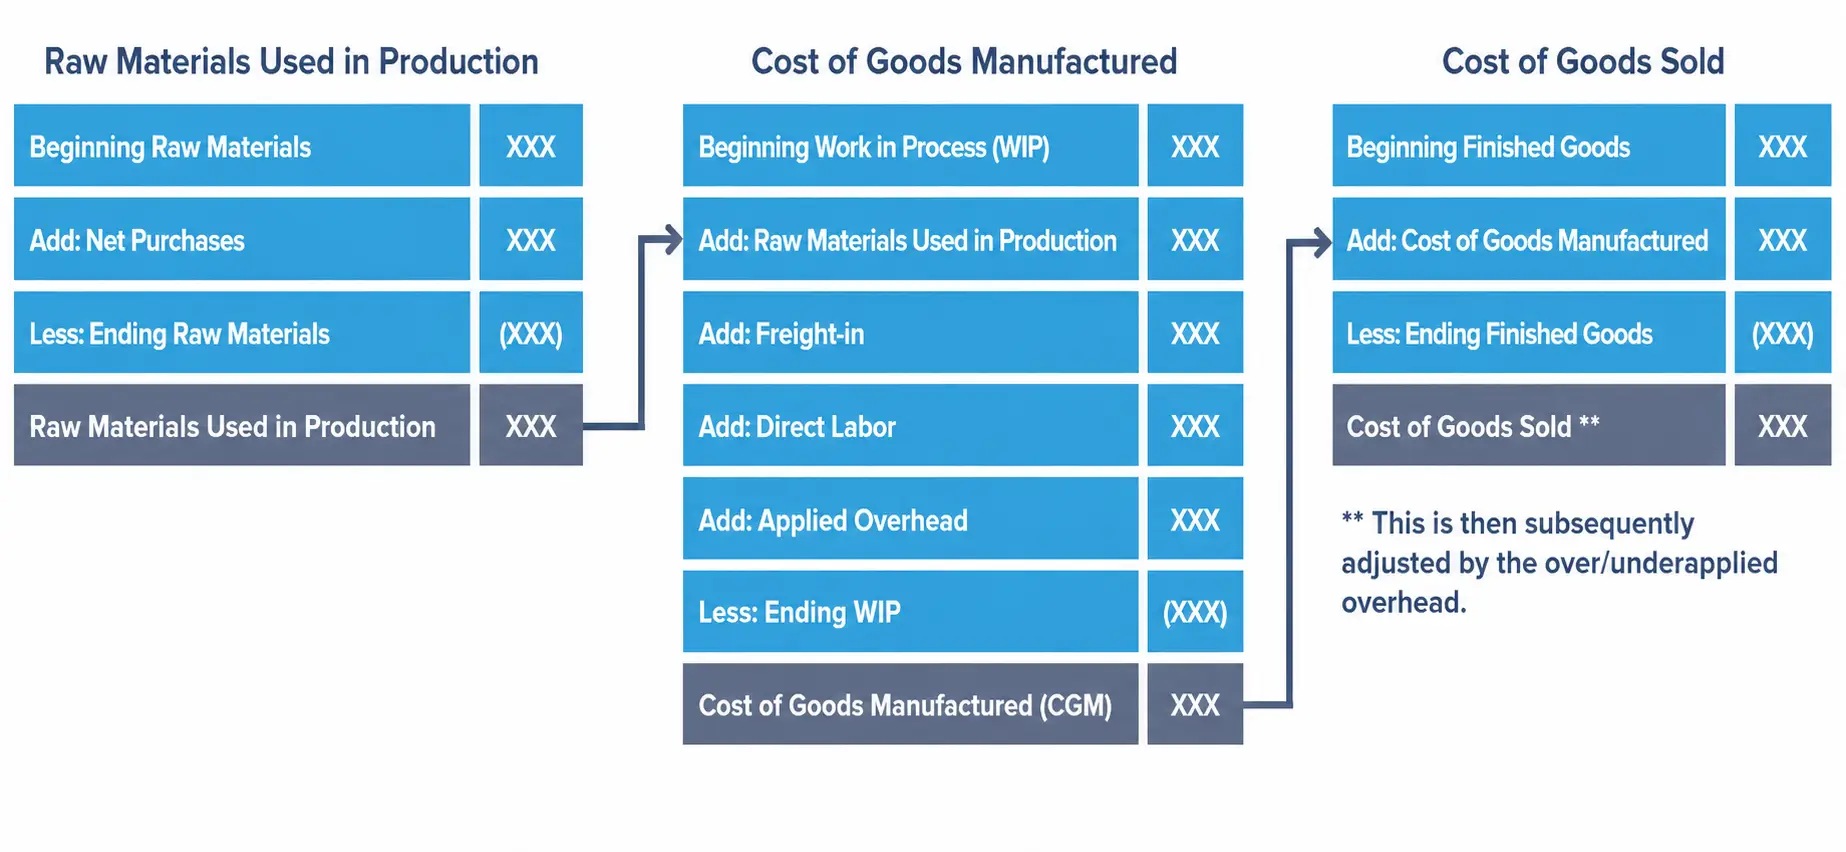
Manufacturing companies carry three inventory accounts: raw materials (materials purchased but not yet put into production), work-in-process (WIP), and finished goods. Costs flow from one account to the next as production proceeds - raw materials move into WIP once they enter production, WIP becomes finished goods once production is complete, and finished goods become COGS once the goods are sold. Along the way, cost of goods manufactured (COGM) equals beginning WIP plus total manufacturing costs (direct materials used, direct labor, and manufacturing overhead applied) minus ending WIP, and COGS equals beginning finished goods plus COGM minus ending finished goods. Costs are accumulated using a job order costing or process costing system, with overhead - a product cost inventoried right along with direct materials and direct labor - assigned using traditional rates or activity-based costing; these topics are covered in later chapters.
Example: Manufacturing cost flow with beginning and ending inventories
Achievable Manufacturing starts the month with $2,000 of raw materials, $4,000 of WIP, and $6,000 of finished goods. It purchases $10,000 of raw materials, incurs $5,000 of direct labor, and applies $3,000 of overhead, ending the month with $1,500 of raw materials, $2,500 of WIP, and $3,000 of finished goods.
Raw materials used is $2,000 + $10,000 − $1,500 = $10,500, so total manufacturing costs are $10,500 + $5,000 + $3,000 = $18,500. Cost of goods manufactured is $4,000 + $18,500 − $2,500 = $20,000, and COGS is $6,000 + $20,000 − $3,000 = $23,000.
Answer: COGS for the month is $23,000.