





Purchases, payables and cash
This chapter extends your understanding of double-entry bookkeeping by focusing on how to record transactions related to purchases, payables, and cash.
Learning objectives
By the end of this chapter, you should be able to:
- Record purchase transactions and purchase returns in the general ledger accounts.
- Identify and explain examples of payables.
- Account for discounts received.
- Record cash transactions in the bank ledger account.
- Describe the need for petty cash records.
Purchases
Purchases are goods or services a business acquires from suppliers as part of its normal operations. Purchases may be:
- paid for immediately, known as cash purchases, or
- settled later, known as credit purchases.
Payables
Credit purchases create payables. Credit purchases are first recorded in the purchases daybook, based on invoices received from suppliers.
In double-entry bookkeeping:
- A credit purchase affects both the purchases ledger account and the payables ledger account.
- A cash purchase affects the purchases ledger account and the cash (or bank) ledger account.
When you later pay a supplier for an earlier credit purchase, the payables balance decreases to show the remaining amount owed.
Contra entries
When a business both buys from and sells to the same party, the two balances may be offset instead of settled separately. The entry is: debit payables, credit receivables, for the lower of the two balances. For example, if a business owes a supplier $500 but that same supplier also owes the business $300 as a customer, the contra entry is: debit payables $300, credit receivables $300.
Purchases returns
When goods are returned, the supplier issues a credit note to confirm the reduction in the amount owed; the buyer may also raise a debit note. These returns are recorded in the purchase returns daybook. Purchase returns reduce the original payable, and in double-entry bookkeeping, they affect both the purchase returns ledger account and the payables ledger account.
Summary of double-entry bookkeeping accounting
Below is a summary of the journal entries on the basis of the double-entry bookkeeping for purchases and payables.
When a credit purchase includes sales tax, the purchase is recorded net of the recoverable tax, with the tax recorded in its own account. For example, a credit purchase of $1,000 plus 20% sales tax is recorded as: debit purchases $1,000, debit sales tax $200, credit payables $1,200. This input tax reduces the amount the business owes to the tax authority.
Illustration: walkthrough
Below is a list of transactions undertaken by Jonko Ltd.
- Credit purchases from ABC Suppliers - $15,000
- Paid ABC Suppliers $10,000
- Credit purchases from XYZ Ltd - $8,500
- Returned defective goods to XYZ Ltd - $1,200
The opening balance of the payables at the start of the period was $6,000.
Required:
- Prepare journal entries (without description) to recognise each transaction.
- Prepare the purchases and purchase return ledger accounts.
- Prepare the trade payables ledger account and determine the closing balance.
Suggested solution:
Do you know the journal entry for transaction 1?
| Account | Debit ($) | Credit ($) |
|---|---|---|
| Purchases | 15,000 | |
| Payables | 15,000 |
Do you know the journal entry for transaction 2?
| Account | Debit ($) | Credit ($) |
|---|---|---|
| Payables | 10,000 | |
| Cash and bank | 10,000 |
Do you know the journal entry for transaction 3?
| Account | Debit ($) | Credit ($) |
|---|---|---|
| Purchases | 8,500 | |
| Payables | 8,500 |
Do you know the journal entry for transaction 4?
| Account | Debit ($) | Credit ($) |
|---|---|---|
| Payables | 1,200 | |
| Purchase returns | 1,200 |
The ledger accounts
- Prepare and balance the purchases ledger account
Total purchases for the period: $15,000 + $8,500 = $23,500.
- Prepare and balance the purchase return ledger account
Total purchase returns for the period: $1,200.
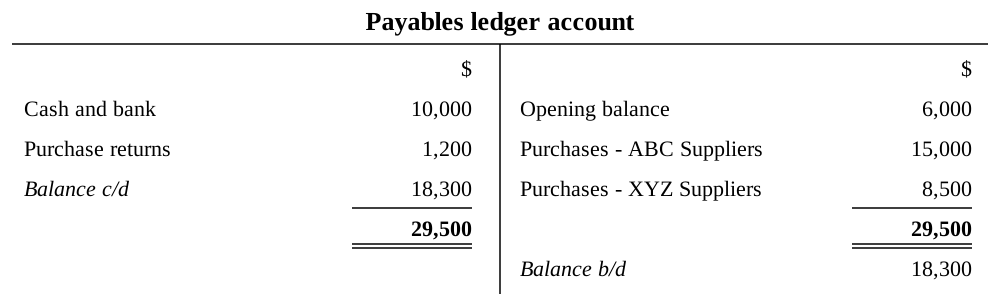
- Prepare and balance the payables ledger account
Closing payables balance (balance c/d): $6,000 + $15,000 + $8,500 − $10,000 − $1,200 = $18,300.
Discounts received
Unlike discount allowed (where the amount recognised for sales may depend on expected customer payment timing), credit purchases are recorded at the gross amount.
If payment is made within the settlement period, the accounting records are adjusted to recognise the discount received. This reduces:
- the cash paid, and
- the payable balance.
The discount received is mainly the cash settlement discount received from suppliers. A trade discount from a supplier is deducted on the invoice before recording, so purchases and payables are recorded net of it, and no discount received is recognised.
Discount received is presented as other income in the statement of profit or loss, so it increases profit.
Illustration
On 1 Jan. 2023, Jentro Company Ltd acquired an item worth $1,000 on credit from a supplier and was offered payment terms of 2% discount if paid within 30 days. Before the end of the month, Jentro makes a payment for the item acquired.
Upon purchase of the item:
| Debit ($) | Credit ($) | |
|---|---|---|
| Purchases | 1,000 | |
| Payables | 1,000 | |
| Being credit purchases |
Upon payment before the month end:
Since Jentro Company paid within the 30-day discount period, the actual payment will be $980 instead of the full $1,000. The difference of $20 represents a discount received by the company.
| Debit ($) | Credit ($) | |
|---|---|---|
| Payables ledger account | 1,000 | |
| Cash/bank ledger account | 980 | |
| Discount received | 20 | |
| Being payment made to credit supplier |
Accounting for cash
Business transactions involve money inflows (receipts) and outflows (payments). These may occur as physical cash or through banks and other financial institutions.
In accounting, these movements are recorded in the cash book, which serves as both:
- a book of prime entry, and
- a ledger account.
When treated as a ledger, it is called the bank or cash account. In this chapter, we will use “bank” to describe receipts and payments of money. Receipts are debited, while payments are credited.
Example: Bank ledger account
During the period, Jonko Ltd received a $20,000 cash receipt from a customer, paid ABC Suppliers $10,000 (transaction 2 above), and paid a supplier $980 after a settlement discount. The bank ledger account for the period is:
Debit ($) Credit ($) Receipt from customer 20,000 Payment to ABC Suppliers 10,000 Payment to supplier (net of discount) 980 Balance c/d 9,020 Answer: closing bank balance (balance c/d) = $9,020, carried down as the opening balance for the next period.
Petty cash
Petty cash is a small amount of cash kept to pay minor expenses such as office supplies. Even though each payment is small, the total can still affect overall cash balances, so petty cash needs to be recorded and controlled. Petty cash is usually managed under the imprest system.
The imprest system
The imprest system manages petty cash by setting aside a fixed amount, called the “float,” for a petty cashier. This float is used to pay small expenses, and a receipt or voucher is kept for every payment. Each transaction is recorded in a petty cash book, including details such as the date, purpose, amount, and recipient.
At the end of each period (or when the fund runs low), the petty cashier submits a summary of expenses with supporting documents for reimbursement. The business then reimburses the exact amount spent, restoring the fund to its original level.
At all times:
- remaining cash + receipts (vouchers) = imprest amount.
This system promotes accountability, helps prevent misuse, and provides a clear audit trail for small expenditures.
Reasons for keeping petty cash records
- To provide accountability for money spent, ensuring funds are used appropriately and reducing the risk of theft or fraud.
- To establish when and how the petty cash fund needs to be replenished, and support budgeting for future petty cash needs.