



Sales tax
This chapter explains sales tax as a consumption tax that businesses collect from customers and then remit to the tax authorities. You’ll learn how input tax and output tax work, and how to record sales and purchases that include sales tax.
Learning objectives
By the end of this chapter, you should be able to:
- Describe the principles of the operation of a sales tax
- Calculate sales tax on transactions and record it in the sales tax general ledger account.
Introduction
Sales tax is referred to as value-added tax (VAT) in some jurisdictions. In general, businesses buy items as inputs, add value, and resell the output to customers.
Businesses registered for sales tax collect this tax from customers and remit it periodically (often monthly to quarterly, depending on the jurisdiction) to the relevant tax authorities. The tax rate varies by jurisdiction and may differ across product categories. Some essential items may be exempt or taxed at lower rates.
There are two types of sales tax, namely:
- Input tax
- Output tax
At the end of each period:
- If output tax exceeds input tax, the excess is remitted to the tax authorities.
- If input tax exceeds output tax, the excess is due back to the business. In practice, the excess is often offset against future tax obligations rather than refunded in cash.
Computation of sales tax
Sales tax is calculated by multiplying the tax rate by the sales amount (exclusive of tax). In examination questions, sales figures may be given either exclusive or inclusive (gross) of tax.
If an amount is inclusive of sales tax, tax has already been added to the selling price. In that case, you need to separate the tax portion from the gross amount.
See the illustrations below.
Illustration 1: Exclusive of sales tax
KDK Ltd makes a sale of $ 1,000.00 exclusive of sales tax. Given a sales tax rate of 15%:
- What is the sales tax?
- What are the gross sales?
Compute the sales tax.
Sales tax = net sales (exclusive of sales tax) x tax rate
Sales tax = $1,000 x 15%
Sales tax = $150
Compute the gross sales.
Gross sales (inclusive of tax) = net sales (exclusive of sales tax) + sales tax
Gross sales (inclusive of tax) = $1,000 + $150
Gross sales (inclusive of tax) = $1,150
Illustration 2: Inclusive of sales tax
KDK Ltd makes a sale of $ 1,000 inclusive of tax. Given a sales tax rate of 15%:
- What is the sales tax?
- What are the net sales (exclusive of tax)?
Compute the sales tax.
Compute the net sales.
Net sales (exclusive of tax) = gross sales (inclusive of sales tax) - sales tax
Net sales (exclusive of tax) = $1,000 - $130.43
Net sales (exclusive of tax) = $869.57
Accounting treatment for sales tax
Output tax is not revenue: the business collects it on behalf of the government. Input tax is not part of purchases: it is recoverable from (or offset against) the tax authorities. So sales and purchases are both recorded net of tax.
Sale with sales tax
| Debit | Credit | |
|---|---|---|
| Cash (receivable) | X | |
| Sales (net of tax) | X | |
| Sales tax (output tax) | X |
Purchase with sales tax
| Debit | Credit | |
|---|---|---|
| Purchases (net of tax) | X | |
| Sales tax (input tax) | X | |
| Cash (payables) | X |
Returns and discounts
- A sales return reverses the original sale, including its tax: debit sales returns (net) and debit sales tax (the tax portion), credit receivables (gross). A purchase return reverses the input tax the same way.
- Sales tax is calculated on the price after deducting a trade discount, not on the original list price. A trade discount itself isn’t posted to the accounts - only the discounted (net) amount is recorded, with sales tax calculated on that net amount.
Sales tax control account
Businesses use a sales tax control account to record both output and input taxes.
- If input tax exceeds output tax, the excess is an asset (a balance due back from the tax authorities).
- If output tax exceeds input tax, the excess is a liability (a balance to be remitted to the tax authorities).
- When the business pays the balance owed to the tax authorities: debit sales tax, credit cash.
- When the business receives a refund: debit cash, credit sales tax.
- The closing balance on the account equals the opening balance, plus output tax, minus input tax, minus payments made, plus refunds received (for a liability balance).
Illustration: Sales tax control account
KDK Ltd purchased goods amounting to $1,000 tax exclusive and sold them at $1,100 inclusive of sales tax. The sales tax rate is 15%.
- What is the input tax?
- What is the output tax?
- Will KDK Ltd remit to the tax authorities or otherwise, and how much?
- Show all the journal entries to be posted that affect the sales tax ledger accounts.
Compute the input tax.
Input tax = tax rate x purchase value (exclusive)
Input tax = 15% x $1,000
Input tax = $150
Compute the output tax.
Alternatively, we could use this approach.
But,
Thus,
Should KDK Ltd remit to the tax authorities or otherwise?
- Input tax was $150
- Output tax was $143.48
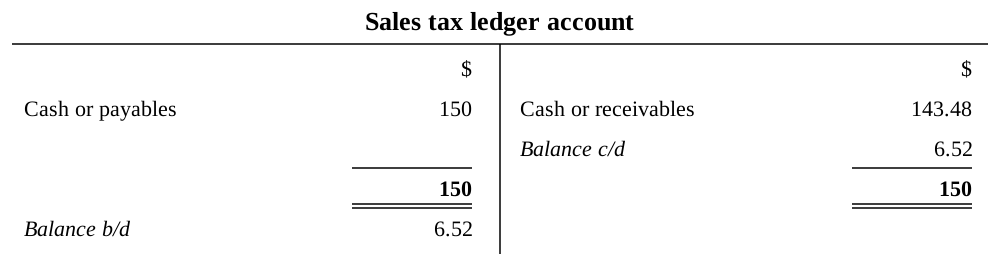
The difference of $6.52 excess of input tax over output tax, will be refunded by the tax authorities. KDK Ltd is entitled to a refund of approximately $6.52 (or it will carry it forward as a tax credit)
The journal entries to be posted
(a) Upon purchase of the goods
| Debit | Credit | |
|---|---|---|
| Purchases (net of tax) | $1,000 | |
| Sales tax (input tax) | $150 | |
| Cash (Payables) | $1,150 | |
| Being purchase of goods plus input VAT |
(b) Upon sale of the goods
| Debit | Credit | |
|---|---|---|
| Cash or receivable | $1,100 | |
| Sales (net of tax) | $956.52 | |
| Sales tax (output tax) | $143.48 | |
| Being sale of goods inclusive of VAT |
Note: in the sales tax T-account, input tax ($150) is debited and output tax ($143.48) is credited, leaving a debit balance of $6.52. This is an asset: an amount receivable from the tax authorities (a tax credit against future liabilities). See below.