



Project budgeting
Definition, purpose, and time frame
Unlike a master budget, which covers an organization’s entire operations over a fiscal period, the project budget is focused solely on a single project, often with a defined beginning and end. Project budgets are commonly used in industries like construction, technology, research and development, and consulting, where specific projects require separate financial oversight and tracking.
The primary purpose of a project budget is to provide a clear financial framework for project-related expenses, ensuring that resources are allocated efficiently to meet the project’s objectives. By outlining the necessary funding and resources, a project budget helps to keep the project on track, within scope, and aligned with the organization’s strategic goals.
Components and interrelationships
The project budget generally includes several core components:
- Labor costs: Direct costs associated with employees or contractors dedicated to the project.
- Material and equipment costs: Expenditures for materials, supplies, and equipment necessary for project tasks.
- Overhead costs: Indirect costs related to the project, including utilities, facility expenses, and administrative support.
- Contingency funds: A reserved portion of the budget for unexpected costs or changes to the project scope.
Each component is interrelated and impacts the overall project budget. For example, labor costs can vary based on the project timeline, while material costs may fluctuate depending on market prices and availability. Contingency funds are crucial for managing unforeseen expenses, allowing for greater flexibility and risk mitigation as the project progresses.
Developing the project budget
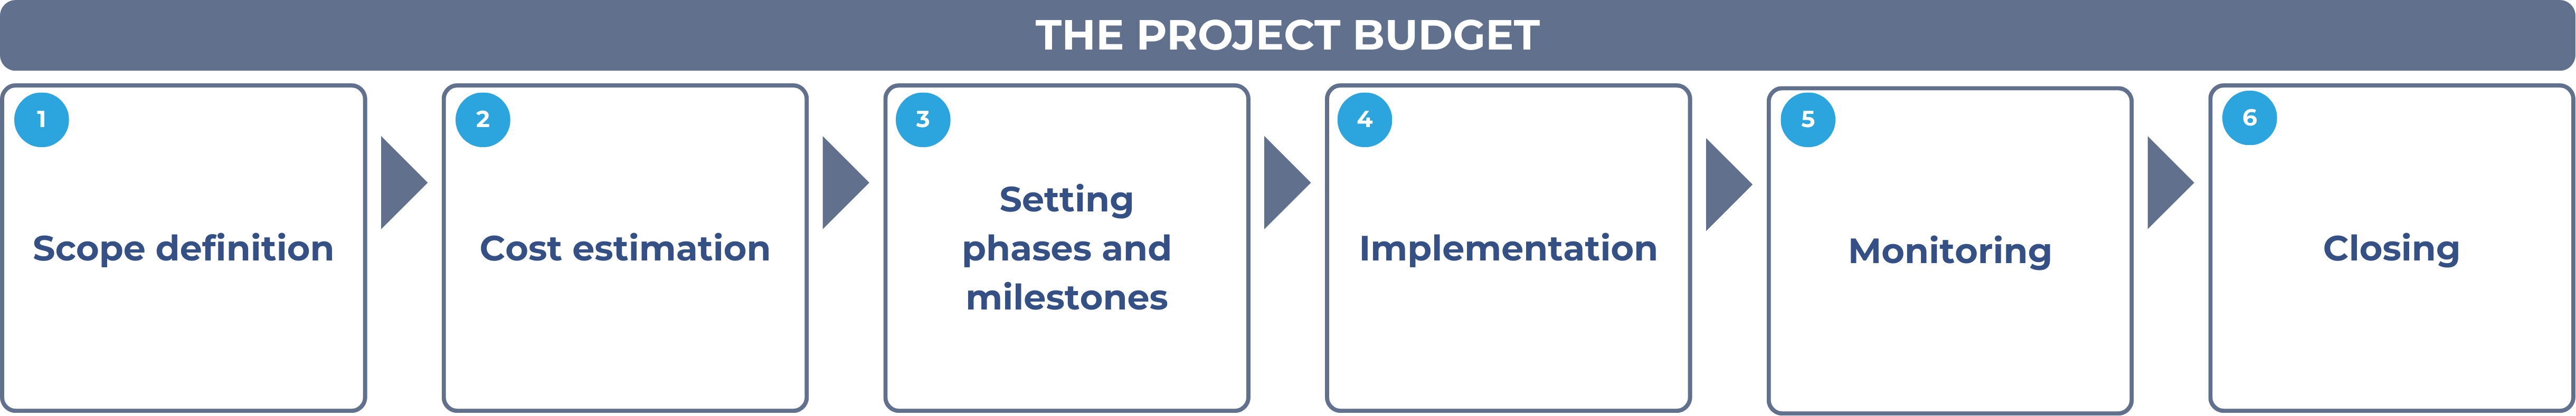
The development of a project budget typically involves a series of key steps to ensure accuracy and alignment with project objectives:
- Scope definition: Project managers begin by defining the project scope, outlining the tasks, milestones, and deliverables needed to achieve the project’s goals.
- Cost estimation: With a clear scope, costs associated with labor, materials, and other resources are estimated. This may involve historical data analysis, supplier quotes, or expert judgment based on similar past projects.
- Phases and milestones: The budget is then organized by project phases or key milestones, aligning specific costs with project deliverables and timelines.
- Implementation: Funds are allocated, and resources are mobilized according to the project schedule. Each department involved is given the necessary budget and timeline for their tasks.
- Monitoring: During implementation, ongoing monitoring ensures that project spending aligns with budgeted expectations, and any variances are noted for corrective action.
- Closing: At project completion, the final costs are compared with the budgeted amounts, allowing managers to analyze variances and assess the budget’s accuracy.
Project budgets are often baselined as static budgets, meaning the original plan stays fixed unless formally revised. In practice, though, individual phases are commonly re-forecast or flexed as work progresses, updated to reflect actual costs, scope changes, or new estimates for upcoming phases. Contingency funds may be allocated to account for unexpected costs or minor changes to project scope, providing some flexibility without requiring a full budget revision.
Example: Building and revising a project budget
A construction company is budgeting a three-phase renovation, with a 10% contingency applied to the combined subtotal of all three phases: phase 1 totals $40,000 (labor $20,000 + materials $15,000 + overhead $5,000), phase 2 totals $51,000 (labor $25,000 + materials $20,000 + overhead $6,000), and phase 3 totals $34,000 (labor $18,000 + materials $12,000 + overhead $4,000).
Subtotal: $40,000 + $51,000 + $34,000 = $125,000. Contingency: $125,000 × 0.10 = $12,500. Total budget: $137,500.
If phase 2 material costs then rise 15% ($20,000 to $23,000), the phase 2 subtotal becomes $54,000, the overall subtotal becomes $128,000, the contingency becomes $12,800, and the revised total budget is $140,800 - $3,300 higher, even though only one phase changed.
Benefits and limitations
Benefits
- Focused resource allocation: The project budget directs resources specifically to project objectives, ensuring efficient use of funds for a defined purpose.
- Enhanced cost control: By setting clear cost targets and benchmarks, the project budget allows for continuous monitoring and control of expenses.
- Risk mitigation: The inclusion of contingency funds helps in managing unexpected costs, providing flexibility to handle project challenges without derailing overall budgets.
Limitations
- Limited flexibility: As a static budget, the project budget can be rigid if significant changes occur in project scope or cost assumptions, making it challenging to adapt.
- Reliance on accurate estimates: Developing a realistic project budget requires precise estimates; inaccurate cost projections can lead to budget overruns or funding shortfalls.
- Complexity in large projects: For large-scale projects, developing and managing a detailed project budget can be complex, requiring advanced cost estimation and tracking systems.
When deciding which budgeting approach fits a situation, a project budget is the right tool for funding and tracking a standalone initiative with its own start and end date, something the annual master budget doesn’t isolate, since it covers the whole organization’s operations for a fiscal period. Later chapters cover zero-based budgeting (building each budget from scratch and justifying every cost) and flexible budgeting (adjusting a budget for actual volume), which solve different problems than isolating one project’s costs.