


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
CMA Part 1
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. External financial reporting decisions
2. Planning, budgeting, and forecasting
2.1 Strategic planning
2.2 Budgeting concepts
2.3 Forecasting techniques
2.4 Budgeting methodologies
2.4.1 Learning outcomes
2.4.2 Annual business plans (master budgets)
2.4.3 Project budgeting
2.4.4 Activity-based budgeting
2.4.5 Zero-based budgeting
2.4.6 Continuous (rolling) budgets
2.4.7 Flexible budgeting
2.5 Annual profit plan and supporting schedules
2.6 Top-level planning and analysis
3. Performance management
4. Cost management
5. Internal control
6. Technology and analytics
Wrapping up
Achievable logoAchievable logo
2.4.4 Activity-based budgeting
Achievable CMA Part 1
2. Planning, budgeting, and forecasting
2.4. Budgeting methodologies
Our CMA Part 1 course is currently in development and is a work-in-progress.

Activity-based budgeting

6 min read
Font
Discuss
Share
Feedback

Definition, purpose, and time frame

Definitions
Activity-based budgeting (ABB)
A budgeting approach that allocates costs based on specific activities required to produce goods or provide services. Closely related to activity-based costing (ABC), ABB applies similar principles, using activity cost drivers to assign costs accurately.

While ABC is primarily used as a tool for overhead allocation by linking costs to activities, ABB extends this approach to forecast future resource needs - essentially running ABC’s logic forward: instead of tracing costs backward from finished products to the activities that caused them, ABB starts from budgeted output and activity levels and works forward to the resources those activities will require. This aligns budgets more closely with activity levels and improves cost precision. Because the budget is built up from projected activity levels rather than adjusted from a prior period’s totals, ABB’s output can differ noticeably from a traditional budget whenever expected activity volume changes from year to year. If the company is using ABC, then ABB is the most logical way of preparing relevant budgets.

ABB typically operates within an annual time frame, though it is flexible enough to apply to project-specific or departmental budgets. It is most effective in industries where overhead costs fluctuate based on activity levels, such as manufacturing, project-driven organizations, and service industries.

Components and interrelationships

ABB involves key components:

  • Activities: All necessary actions that drive the production or service process, such as machine setups, quality checks, and customer service.
  • Cost drivers: Elements that drive costs for each activity, such as machine hours, labor hours, or units produced.
  • Resource costs: Total costs associated with each activity, calculated based on the level of resources each activity requires.

In ABB, activities and cost drivers are closely analyzed to allocate resources to activities that drive costs. For example, machine hours may drive maintenance costs, while labor hours are key for assembly processes. Cost drivers link resource consumption directly to each activity, clarifying where resources will be consumed in the budget.

Developing the activity-based budget

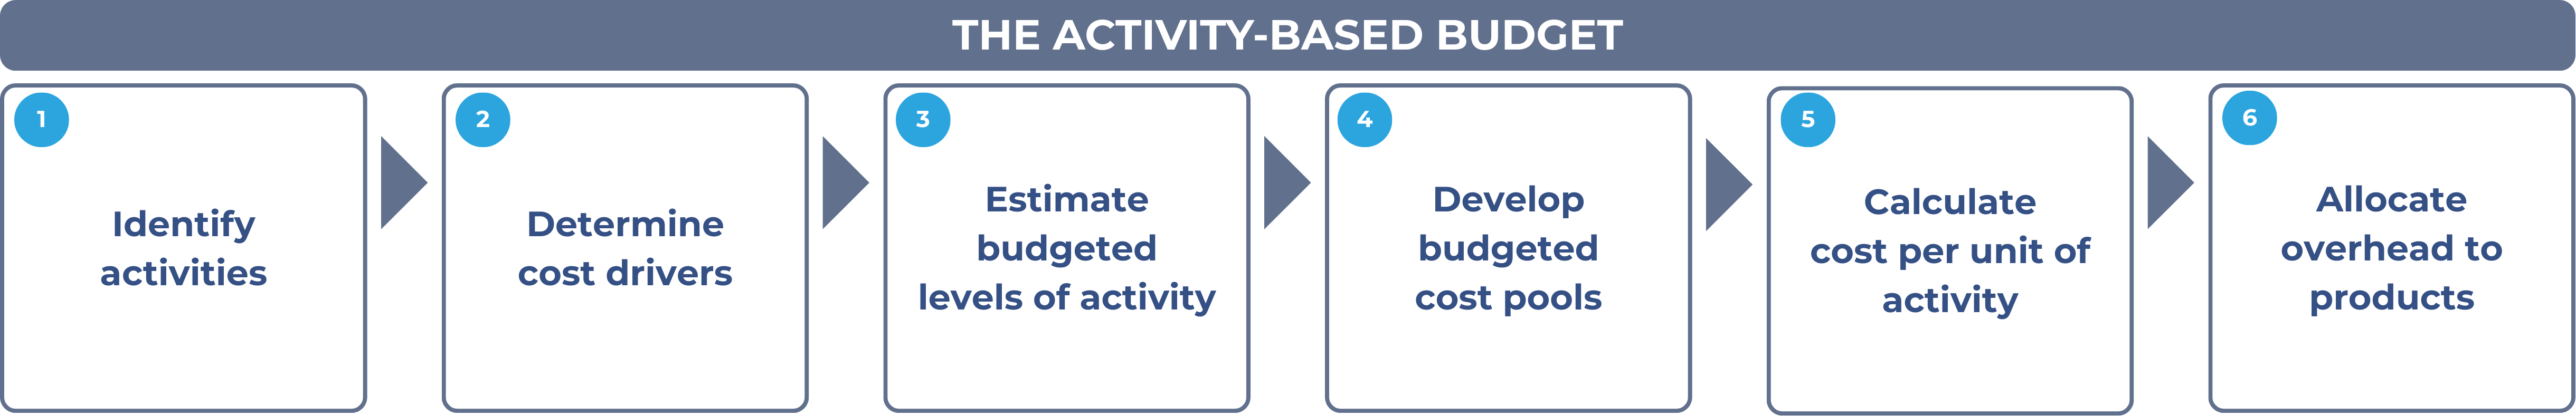
The development of an activity-based budget involves several structured steps to ensure that budget allocations are both accurate and activity-based:

The activity-based budget
Achievable
  1. Identify activities: Begin by identifying all necessary activities required to achieve production or service goals.
  2. Determine activity cost drivers: Identify the primary drivers that create costs in each activity, such as machine hours, labor hours, or setup frequency, which will influence resource needs.
  3. Estimate budgeted levels of activity: Forecast the expected level of each cost-driving activity, considering the budgeted production level. This step links production output to the activities needed, establishing a foundation for allocating overhead costs.
  4. Develop budgeted cost pools: Create budgeted cost pools for each activity based on projected overhead costs. Cost pools represent the total budgeted overhead for each activity, allowing for focused resource allocation.
  5. Calculate budgeted costs per unit of activity: Determine the budgeted overhead cost per unit of activity by dividing the total budgeted overhead cost for each activity by the total budgeted activity units. For example, if total budgeted maintenance costs are $50,000 and the activity level is 5,000 machine hours, the budgeted cost per machine hour would be $10.
  6. Allocate overhead to products: Using the budgeted cost per activity unit, allocate overhead costs to each product based on its level of each activity. For instance, if a product requires 100 machine hours, it would receive $1,000 in maintenance costs (100 hours × $10 per machine hour). Different overhead costs, each with its own cost driver, are allocated based on the activity usage for each product.

Example: Activity-based budget

Anchor Manufacturing budgets two cost-driving activities for the coming year: machine setups and quality inspections.

  • Setups: 200 setups budgeted at $400 per setup
  • Inspections: 500 inspections budgeted at $20 per inspection

The budgeted overhead for each activity is:

SetupsInspectionsTotal budgeted overhead​=200×$400=$80,000=500×$20=$10,000=$80,000+$10,000=$90,000​

Now suppose Anchor shifts to smaller batch sizes for the same total output, which raises the number of setups from 200 to 260 while inspections stay at 500. The setup budget increases by:

(260−200)×$400=60×$400=$24,000

Even though total units produced haven’t changed, the overhead budget rises to $80,000 + $24,000 + $10,000 = $114,000. A traditional budget built from last year’s total or from units produced wouldn’t capture this increase, because it isn’t driven by the activity that actually changed - the number of setups.

Answer: Total budgeted overhead is $90,000 initially, rising to $114,000 after the increase in setups.

When a company uses ABC to allocate overhead costs, integrating ABB into the budgeting process enhances accuracy and responsiveness to changes in activity levels, ensuring budgets are more closely aligned with real production demands.

Benefits and limitations

Benefits

  • Improved cost precision: ABB enhances accuracy by focusing on projected activity levels, reducing the likelihood of over- or underestimating resource requirements.
  • Better resource allocation: By directing resources to specific activities, ABB promotes cost-efficient operations, especially in areas with high resource demands.
  • Alignment with cost drivers: ABB links budgets to activity cost drivers, enabling managers to control activities that drive costs, which can lead to targeted cost reductions.
  • Identification of budgetary slack: ABB’s detailed approach highlights areas where budgets may be overstated, helping to identify and reduce budgetary slack for more realistic budget targets.

Limitations

  • Complexity and time demands: ABB requires detailed identification of activities and cost drivers, which is more time-consuming than traditional budgeting methods.
  • Data dependency: Accurate data on activity levels and resource usage is essential for ABB, as data inconsistencies can impact budget accuracy.
  • Dependence on ABC: ABB relies on the organization using an activity-based costing system, since it allocates costs based on ABC principles; it’s easiest to implement well when a company already has an ABC system in place.

Pitfall: Don’t confuse ABB with a flexible budget. A flexible budget adjusts the budget for a single volume measure, such as units produced, while ABB adjusts resource needs separately for each activity’s own driver (setups, inspections, machine hours, and so on). Flexible budgeting is covered in a later chapter.

Definition & purpose

  • Activity-based budgeting (ABB): allocates costs based on activities needed to produce goods/services
  • Extends activity-based costing (ABC) logic forward — starts from budgeted output/activity levels, works toward resource needs (vs. ABC’s backward tracing from costs to activities)
  • Most logical budgeting method when company already uses ABC; typically annual but adaptable to projects/departments
  • Best suited to industries with fluctuating overhead (manufacturing, project-driven, service)

Key components

  • Activities: actions driving production/service (setups, inspections, customer service)
  • Cost drivers: factors causing costs per activity (machine hours, labor hours, units)
  • Resource costs: total cost tied to each activity’s resource consumption
  • Cost drivers link resource use directly to specific activities

Building the budget (steps)

  • Identify activities → determine cost drivers → estimate budgeted activity levels → build budgeted cost pools → calculate cost per activity unit → allocate overhead to products
  • Formula: Cost per activity unit=Total budgeted activity unitsTotal budgeted overhead for activity​
  • Example: $50,000 maintenance ÷ 5,000 machine hours = $10/hour; 100 hours used → $1,000 allocated
  • Key insight: changes in activity levels (e.g., more setups from smaller batch sizes) shift the budget even if total units stay constant — traditional budgets miss this since they’re not driven by the specific changed activity

Benefits vs. limitations

  • Benefits: improved cost precision, better resource allocation, alignment with cost drivers for targeted cost control, helps expose budgetary slack
  • Limitations: time-consuming/complex, depends heavily on accurate activity data, works best when ABC system already exists
  • Pitfall: ABB ≠ flexible budget — flexible budgets adjust to one volume measure (e.g., units), while ABB adjusts each activity’s budget based on its own unique driver

Sign up for free to take 10 quiz questions on this topic

Previous
Next  | 2.4.5 Zero-based budgeting
All rights reserved ©2016 - 2026 Achievable, Inc.

Activity-based budgeting

Definition, purpose, and time frame

Definitions
Activity-based budgeting (ABB)
A budgeting approach that allocates costs based on specific activities required to produce goods or provide services. Closely related to activity-based costing (ABC), ABB applies similar principles, using activity cost drivers to assign costs accurately.

While ABC is primarily used as a tool for overhead allocation by linking costs to activities, ABB extends this approach to forecast future resource needs - essentially running ABC’s logic forward: instead of tracing costs backward from finished products to the activities that caused them, ABB starts from budgeted output and activity levels and works forward to the resources those activities will require. This aligns budgets more closely with activity levels and improves cost precision. Because the budget is built up from projected activity levels rather than adjusted from a prior period’s totals, ABB’s output can differ noticeably from a traditional budget whenever expected activity volume changes from year to year. If the company is using ABC, then ABB is the most logical way of preparing relevant budgets.

ABB typically operates within an annual time frame, though it is flexible enough to apply to project-specific or departmental budgets. It is most effective in industries where overhead costs fluctuate based on activity levels, such as manufacturing, project-driven organizations, and service industries.

Components and interrelationships

ABB involves key components:

  • Activities: All necessary actions that drive the production or service process, such as machine setups, quality checks, and customer service.
  • Cost drivers: Elements that drive costs for each activity, such as machine hours, labor hours, or units produced.
  • Resource costs: Total costs associated with each activity, calculated based on the level of resources each activity requires.

In ABB, activities and cost drivers are closely analyzed to allocate resources to activities that drive costs. For example, machine hours may drive maintenance costs, while labor hours are key for assembly processes. Cost drivers link resource consumption directly to each activity, clarifying where resources will be consumed in the budget.

Developing the activity-based budget

The development of an activity-based budget involves several structured steps to ensure that budget allocations are both accurate and activity-based:

  1. Identify activities: Begin by identifying all necessary activities required to achieve production or service goals.
  2. Determine activity cost drivers: Identify the primary drivers that create costs in each activity, such as machine hours, labor hours, or setup frequency, which will influence resource needs.
  3. Estimate budgeted levels of activity: Forecast the expected level of each cost-driving activity, considering the budgeted production level. This step links production output to the activities needed, establishing a foundation for allocating overhead costs.
  4. Develop budgeted cost pools: Create budgeted cost pools for each activity based on projected overhead costs. Cost pools represent the total budgeted overhead for each activity, allowing for focused resource allocation.
  5. Calculate budgeted costs per unit of activity: Determine the budgeted overhead cost per unit of activity by dividing the total budgeted overhead cost for each activity by the total budgeted activity units. For example, if total budgeted maintenance costs are $50,000 and the activity level is 5,000 machine hours, the budgeted cost per machine hour would be $10.
  6. Allocate overhead to products: Using the budgeted cost per activity unit, allocate overhead costs to each product based on its level of each activity. For instance, if a product requires 100 machine hours, it would receive $1,000 in maintenance costs (100 hours × $10 per machine hour). Different overhead costs, each with its own cost driver, are allocated based on the activity usage for each product.

Example: Activity-based budget

Anchor Manufacturing budgets two cost-driving activities for the coming year: machine setups and quality inspections.

  • Setups: 200 setups budgeted at $400 per setup
  • Inspections: 500 inspections budgeted at $20 per inspection

The budgeted overhead for each activity is:

SetupsInspectionsTotal budgeted overhead​=200×$400=$80,000=500×$20=$10,000=$80,000+$10,000=$90,000​

Now suppose Anchor shifts to smaller batch sizes for the same total output, which raises the number of setups from 200 to 260 while inspections stay at 500. The setup budget increases by:

(260−200)×$400=60×$400=$24,000

Even though total units produced haven’t changed, the overhead budget rises to $80,000 + $24,000 + $10,000 = $114,000. A traditional budget built from last year’s total or from units produced wouldn’t capture this increase, because it isn’t driven by the activity that actually changed - the number of setups.

Answer: Total budgeted overhead is $90,000 initially, rising to $114,000 after the increase in setups.

When a company uses ABC to allocate overhead costs, integrating ABB into the budgeting process enhances accuracy and responsiveness to changes in activity levels, ensuring budgets are more closely aligned with real production demands.

Benefits and limitations

Benefits

  • Improved cost precision: ABB enhances accuracy by focusing on projected activity levels, reducing the likelihood of over- or underestimating resource requirements.
  • Better resource allocation: By directing resources to specific activities, ABB promotes cost-efficient operations, especially in areas with high resource demands.
  • Alignment with cost drivers: ABB links budgets to activity cost drivers, enabling managers to control activities that drive costs, which can lead to targeted cost reductions.
  • Identification of budgetary slack: ABB’s detailed approach highlights areas where budgets may be overstated, helping to identify and reduce budgetary slack for more realistic budget targets.

Limitations

  • Complexity and time demands: ABB requires detailed identification of activities and cost drivers, which is more time-consuming than traditional budgeting methods.
  • Data dependency: Accurate data on activity levels and resource usage is essential for ABB, as data inconsistencies can impact budget accuracy.
  • Dependence on ABC: ABB relies on the organization using an activity-based costing system, since it allocates costs based on ABC principles; it’s easiest to implement well when a company already has an ABC system in place.

Pitfall: Don’t confuse ABB with a flexible budget. A flexible budget adjusts the budget for a single volume measure, such as units produced, while ABB adjusts resource needs separately for each activity’s own driver (setups, inspections, machine hours, and so on). Flexible budgeting is covered in a later chapter.

Key points

Definition & purpose

  • Activity-based budgeting (ABB): allocates costs based on activities needed to produce goods/services
  • Extends activity-based costing (ABC) logic forward — starts from budgeted output/activity levels, works toward resource needs (vs. ABC’s backward tracing from costs to activities)
  • Most logical budgeting method when company already uses ABC; typically annual but adaptable to projects/departments
  • Best suited to industries with fluctuating overhead (manufacturing, project-driven, service)

Key components

  • Activities: actions driving production/service (setups, inspections, customer service)
  • Cost drivers: factors causing costs per activity (machine hours, labor hours, units)
  • Resource costs: total cost tied to each activity’s resource consumption
  • Cost drivers link resource use directly to specific activities

Building the budget (steps)

  • Identify activities → determine cost drivers → estimate budgeted activity levels → build budgeted cost pools → calculate cost per activity unit → allocate overhead to products
  • Formula: Cost per activity unit=Total budgeted activity unitsTotal budgeted overhead for activity​
  • Example: $50,000 maintenance ÷ 5,000 machine hours = $10/hour; 100 hours used → $1,000 allocated
  • Key insight: changes in activity levels (e.g., more setups from smaller batch sizes) shift the budget even if total units stay constant — traditional budgets miss this since they’re not driven by the specific changed activity

Benefits vs. limitations

  • Benefits: improved cost precision, better resource allocation, alignment with cost drivers for targeted cost control, helps expose budgetary slack
  • Limitations: time-consuming/complex, depends heavily on accurate activity data, works best when ABC system already exists
  • Pitfall: ABB ≠ flexible budget — flexible budgets adjust to one volume measure (e.g., units), while ABB adjusts each activity’s budget based on its own unique driver

More from Budgeting methodologies

  • Learning outcomes
  • Annual business plans (master budgets)
  • Project budgeting
  • Zero-based budgeting
  • Continuous (rolling) budgets