



Overview of labor cost variance formula
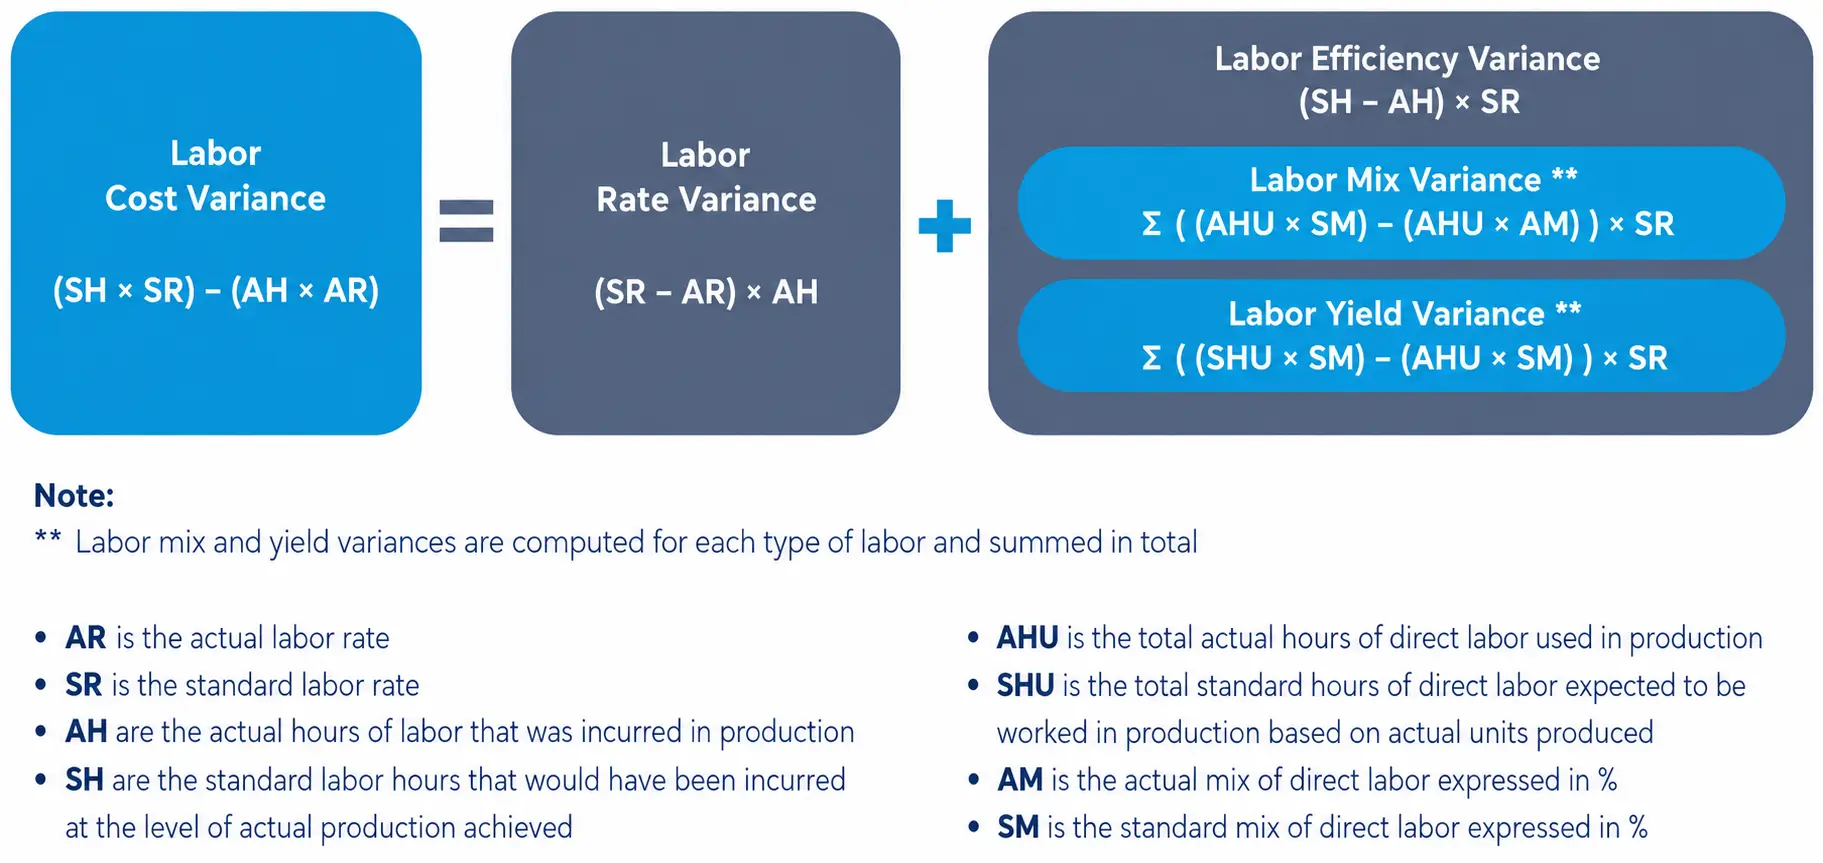
The labor cost variance is the difference between the actual labor cost and the standard labor cost for the production achieved. The labor cost is commonly expressed in terms of the hourly rate of the employees. The general formula for this is expressed below:
Example: Labor cost variance
1,000 units at 2 hours/unit and $20/hour standard gives SH = 2,000 hours; actual was 2,100 hours at $19/hour.
- Standard cost = 2,000 × $20 = $40,000
- Actual cost = 2,100 × $19 = $39,900
- Variance = $100 F
That nets a $2,100 F rate variance against a $2,000 U efficiency variance (covered next) - a small favorable total can hide offsetting variances.
Answer: $100 F
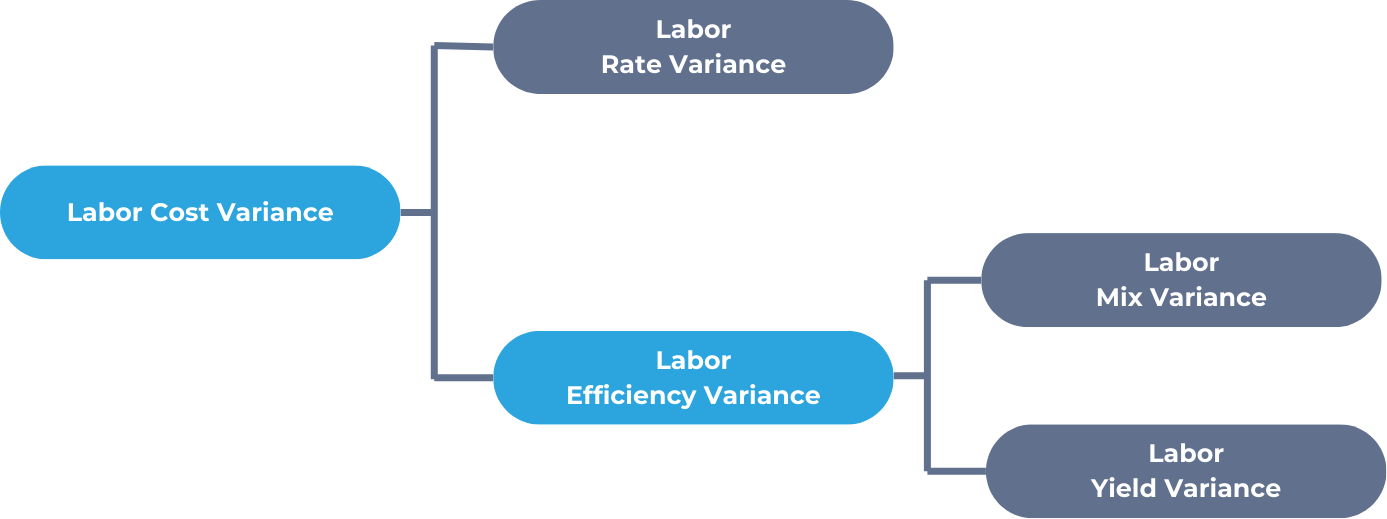
The labor cost variance is broken down into different components to isolate the sources of deviations of actual labor costs from standard labor costs. The variance primarily arises from two sources:
- differences between the standard rate and the actual rate paid for labor (labor rate variance); and
- differences between the standard hours allowed and the actual hours worked (labor efficiency variance). Similar to materials, the labor efficiency variance can be further subdivided into labor mix variance and labor yield variance when multiple types of labor are used in production, as these factors also impact total labor costs. Typical causes include wage changes, skill mix, and equipment issues; pinpointing the cause is the focus of management by exception, covered in an upcoming chapter.
Overview of variance formula
The labor rate variance plus the labor efficiency variance equals the overall labor cost variance, and when the efficiency variance is split, the labor mix variance plus the labor yield variance equals the efficiency variance. Use mix and yield in place of efficiency, never on top of it, or the efficiency effect is counted twice. This provides a useful way to verify the accuracy of your calculations by comparing the sum of the individual variances to the total labor cost variance.
In symbols: .