


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
CMA Part 1
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. External financial reporting decisions
2. Planning, budgeting, and forecasting
3. Performance management
4. Cost management
5. Internal control
6. Technology and analytics
Wrapping up
Achievable logoAchievable logo
1.2.11.1.6 Over time recognition method
Achievable CMA Part 1
1. Financial transactions
1.2. Income statement
1.2.11. Revenue recognition
Our CMA Part 1 course is currently in development and is a work-in-progress.

Over time recognition method

14 min read
Font
Discuss
Share
Feedback
Showing long-term contract revenue recognized at a point in time or over time.
Long-Term Contract Recognition
Achievable

Over time recognition method

When the contract requires some time to perform, and the performance obligations meet the criteria of being satisfied over time, the company records revenues, cost of sales and gross profit as the company fulfills its obligations in the contract.

This means that unlike the previous case of point in time recognition, the income statement is affected every year-end that the contract is not concluded.

For revenue to be recognized over time, any one of the criteria below must be met:

  1. There is simultaneous receipt and consumption of the benefits provided by the company’s performance of the obligations from the contract
  2. The company’s performance of the obligations from the contract enhances or creates an asset controlled by the customer
  3. The company’s performance of the obligations from the contract does not create an asset with an alternative use to the company, and the company has an enforceable right to payment for performance completed to date.

Recognition of the revenues can be straight-forward for some contracts in which the revenue is recognized on a straight-line basis. However, accounting for a construction contract can be more complex due to the application of the percentage of completion method. The following are the steps to follow in applying the method:

  1. Calculate the percentage of completion
  2. Calculate the total gross profit from the contract
  3. Calculate the revenue and gross profit to be recognized to date
  4. Record the relevant year-end journal entries
  5. Understand the financial statement presentation

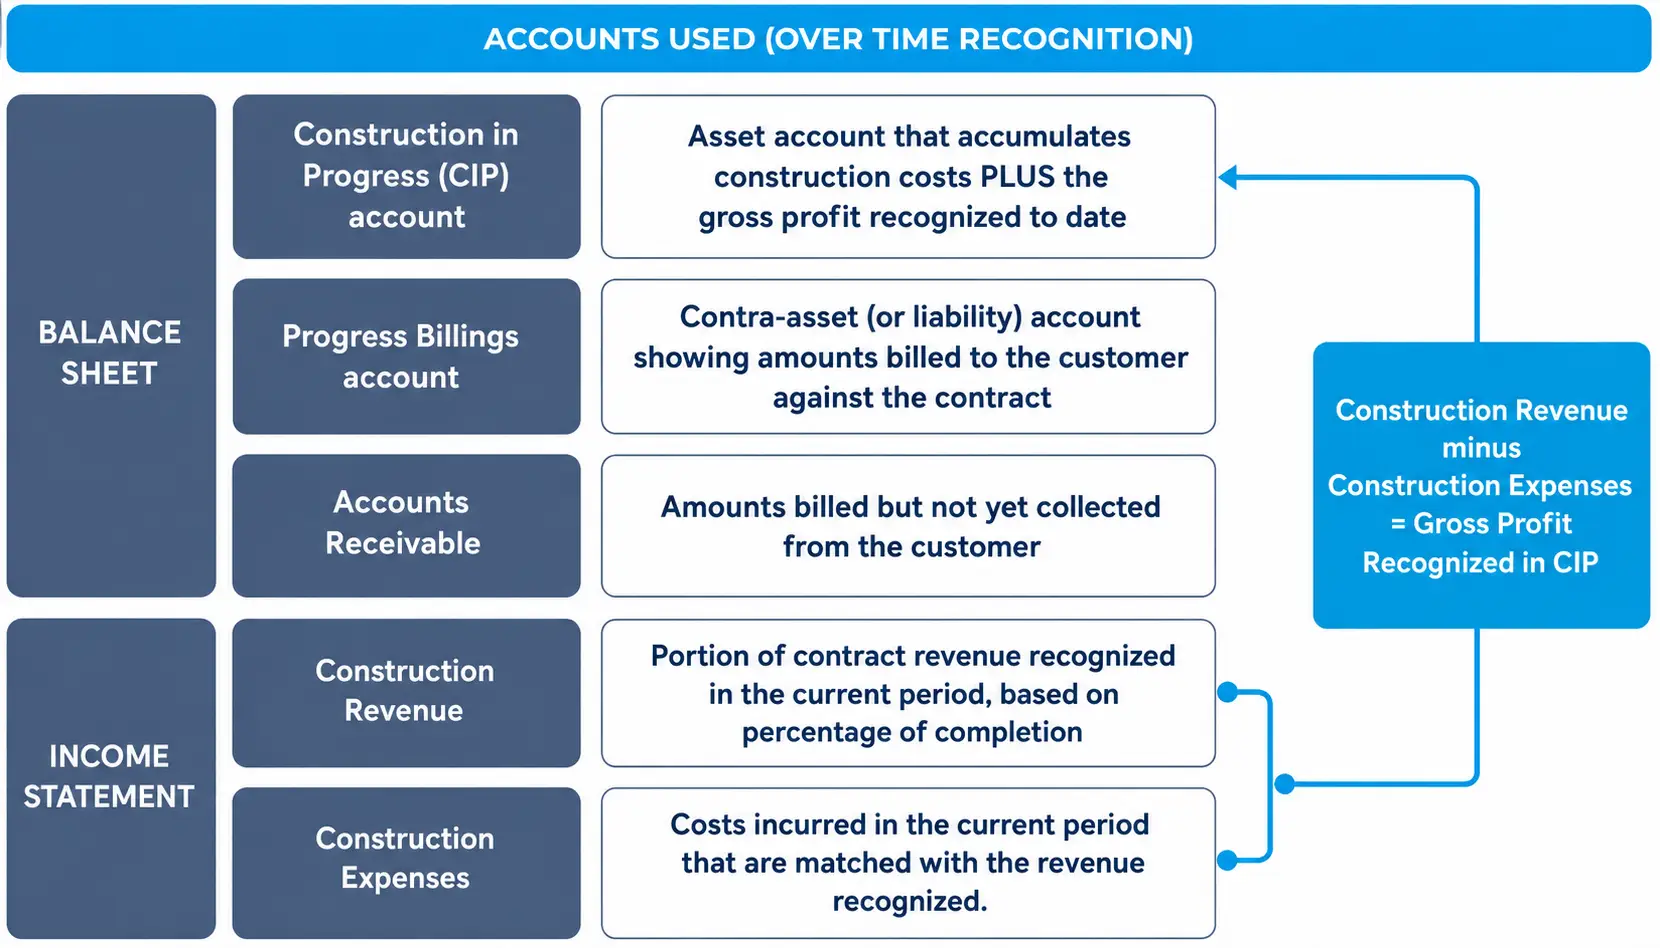
Long-term contracts recognized over time use specific accounts that aren’t common in other types of transactions:

Listing accounts used in over-time revenue recognition, showing construction in progress plus recognized gross profit.
Over-Time Recognition Accounts
Achievable

The accounts are used the same way as in point-in-time recognition, with one key difference: the CIP account accumulates both the actual costs incurred to date and the gross profit recognized to date, not just the costs.

Step 1: Calculate the percentage of completion

The percentage of completion is calculated every end of the year to track the progress of the project.

There are two possible methods that companies can use depending on the specific circumstances of the project:

  • Output method which calculates the progress based on the value the customer has obtained from the contract such as number of units produced.
  • Input method which calculates the progress of the project using the inputs used in the construction such as consumed resources, labor hours, etc.

Exams most often use the input method, also called the cost-to-cost method.

Percentage of completion=Actual costs incurred to date+Estimated costs to completeActual costs incurred to date​

The denominator is also called total estimated contract costs. In the exams, candidates should be careful in determining the type of costs provided by the problem because it can provide directly the total estimated costs or a breakdown of it.

The examples moving forward pertain to the input method.

Step 2: Calculate the total gross profit from the contract

The total gross profit from the contract should also be calculated every year-end.

This is the estimated total profit that the company is expecting to obtain at the conclusion of the contract. The inputs used in the computation are similar to a normal gross profit computation as follows:

Contract price XX
Less: costs incurred to date (XX)
Less: estimated costs to incur (XX)
Estimated gross profit (loss) on the contract XX (XX)

This portion is important because, just like in point in time recognition method, estimated losses on a contract are also recognized immediately in full despite the percentage of completion while gross profits are recognized on a piecemeal basis using the percentage of completion computed from the previous step.

Reversal of previously recognized gross profit when a contract becomes loss-making

If revised estimates show that a contract will produce an overall loss, U.S. GAAP requires recognizing the entire expected loss immediately, even though the contract isn’t finished. Because prior periods may already have recognized gross profit, the current-period loss must be large enough to both reverse that prior profit and report the full expected loss as of this date:

Current-period loss=Total expected contract loss+gross profit previously recognized

Step 3: Calculate the revenue and gross profit to be recognized to date

For over time recognition of revenues, the following items are needed for the journal entries:

The revenues to be recognized in the current period is calculated as follows:

Contract price XX
Multiply: percentage of completion %
Total revenues to be recognized to date XX
Less: revenues recognized in prior periods (XX)
Total revenues to be recognized in the current period XX

The gross profit to be recognized follow the same logic as above except that the main input is the gross profit computed from the previous step:

Total estimated gross profit from the contract XX
Multiply: percentage of completion %
Total estimated gross profit to be recognized to date XX
Less: gross profits recognized in prior periods (XX)
Gross profit to be recognized in the current period XX

The costs to be recognized in a profitable period are simply the actual costs incurred in the current period - no special computation is needed. In a loss period, though, construction expense is no longer just the actual costs incurred: it equals the current-period revenue recognized plus the current-period loss, since the full loss must be recognized immediately (see the callout above).

In a profitable period, revenue minus actual costs incurred for the period equals the gross profit computed above; that consistency is the basis for the year-end journal entries in step 4.2 below.

Step 4: Record the relevant year-end journal entries

The accounts to be used for this method are the same as the point in time recognition method but the journal entries are different because of the recognition of the gross profit in each year-end.

Step 4.1: Contract costs are accumulated in the CIP account similar to the previous method.

Debit construction in progress (CIP) and credit cash and/or accounts payable for the actual costs incurred during the period - the same entry used in the point-in-time method. Because CIP is a balance sheet account, these costs accumulate there and become an input to the total estimated contract costs formula from step 1.

Step 4.2: Contract revenues are recorded along with the gross profit.

This journal entry is specific to the over time recognition method. In this journal entry, we use the inputs determined in the preceding steps.

Account Debit Credit Financial statement element
Construction expense XXX Expense
Construction in progress (CIP) XXX Asset
Construction revenues XXX Revenue
To record the gross profit for the period

The sections of the journal entry are:

  • The debit in construction expense should be the same amount as the debit in CIP in the previous journal entry to record the actual construction costs - this holds in a profitable period. In a loss period, construction expense instead equals the current-period revenue recognized plus the current-period loss (see step 3).
  • The debit in CIP account is the gross profit computed in Step 3. In a loss period, this line is a credit instead of a debit, since CIP is reduced by the loss rather than increased by a profit.
  • The credit in construction revenues should be the same as the “revenue to be recognized in the current period” computed in Step 3

After the above journal entry, the CIP account in the balance sheet accumulates two items:

  1. actual costs incurred to date; and
  2. gross profit recognized to date.

This total makes it the same as the total revenues recognized to date. It is important to know this fact in relation to the nature of the Progress Billing account which will be discussed in the next journal entry.

The example below walks through steps 1-3 and this step 4.2 entry for two profitable years, then a third year in which revised estimates turn the contract into a loss.

Example: applying the percentage-of-completion method

Ace Builders signs a contract to construct a warehouse for a contract price of $1,000,000. Total estimated contract costs are $600,000, so the total estimated gross profit on the contract is $400,000.

Year 1: Actual costs incurred to date are $180,000, and estimated costs to complete are $420,000.

  • Percentage of completion: $180,000+$420,000$180,000​=30%
  • Revenue to recognize in Year 1: 30%×$1,000,000=$300,000
  • Gross profit to recognize in Year 1: 30%×$400,000=$120,000
  • Costs incurred in Year 1: $180,000
  • Year 1 journal entry (Step 4.2): debit construction expense $180,000, debit CIP $120,000, credit construction revenues $300,000

Year 2: By year-end, actual costs incurred to date total $420,000 (an additional $240,000 spent during the year), and estimated costs to complete have dropped to $180,000.

  • Percentage of completion: $420,000+$180,000$420,000​=70%
  • Revenue recognized to date: 70%×$1,000,000=$700,000; less the $300,000 recognized in Year 1 leaves $400,000 to recognize in Year 2
  • Gross profit recognized to date: 70%×$400,000=$280,000; less the $120,000 recognized in Year 1 leaves $160,000 to recognize in Year 2
  • Year 2 journal entry (Step 4.2): debit construction expense $240,000, debit CIP $160,000, credit construction revenues $400,000

Year 3: Unexpected delays push total estimated contract costs up to $1,050,000, turning the contract into a $50,000 loss ($1,000,000 contract price − $1,050,000 total estimated costs). The project is completed by year-end, so actual costs incurred to date reach the full $1,050,000 and revenue recognized to date reaches the full $1,000,000.

  • Revenue to recognize in Year 3: $1,000,000 total − $700,000 recognized in Years 1 and 2 = $300,000
  • Current-period loss: the $50,000 total expected loss plus the $280,000 of gross profit already recognized = $330,000 (this reverses the prior profit and brings cumulative income down to the full $50,000 loss)
  • Year 3 journal entry (Step 4.2): debit construction expense $630,000 (the $300,000 revenue recognized plus the $330,000 loss), credit CIP $330,000 (the loss - CIP is credited, not debited, in a loss period), credit construction revenues $300,000

Answer: Cumulative gross profit (loss) after Year 3 is $120,000 + $160,000 − $330,000 = −$50,000, matching the $50,000 total loss now expected on the contract.

Step 4.3: Progress billings are recorded the same way as the point in time recognition method.

Debit accounts receivable and credit progress billings for the amount billed to the customer - the same entry as in the point-in-time method. Progress billings is a contra-asset account that offsets CIP, not a liability in its own right; only the net balance of the two accounts appears on the balance sheet, as a contract asset or a contract liability.

The progress billings account is a contra-asset account (to CIP) with a normal credit balance representing the portion of the contract price that has already been billed to the client. This is separate from the revenues recognized using the percentage of completion because the billings may be calculated using a different approach.

As mentioned previously, the revenues recognized on the contract are actually accumulated in the Construction in progress (CIP) account in the balance sheet with a normal balance in the debit side.

Both accounts (CIP and progress billings) are presented at net in the balance sheet at year-end with the following implications:

  • If CIP>progress billings: means there is a net contract asset. This can also be understood as an unbilled revenue since the revenues recognized to date are greater than the revenues billed from the customer.
  • If CIP<progress billings: means there is a net contract liability. This can also be understood as an unearned revenue since the company billed more than what was actually earned.

Step 4.4: Collections of accounts are recorded against the accounts receivable previously set-up, just like in a point in time recognition method.

Debit cash and credit accounts receivable for the amount collected - the same entry as in the point-in-time method. The progress billings account is not affected by collections.

Step 4.5: The conclusion of the contract is recorded by closing the CIP and progress billings accounts with each other.

Unlike the point in time recognition method where the CIP is closed to construction expenses and the progress billings are closed to construction revenues, the journal entry upon the conclusion of the contract for an over time recognition of revenue is to simply close the CIP against the progress billings account. This is possible because at the end of the contract, the total revenues recognized to date (i.e., CIP) should be equal to the progress billings since we will bill the contract price in full.

Account Debit Credit Financial statement element
Progress billings XXX Contra-asset (offsets CIP)
Construction in progress (CIP) XXX Asset
To record the conclusion of the construction contract

Step 5: Understand the financial statement presentation

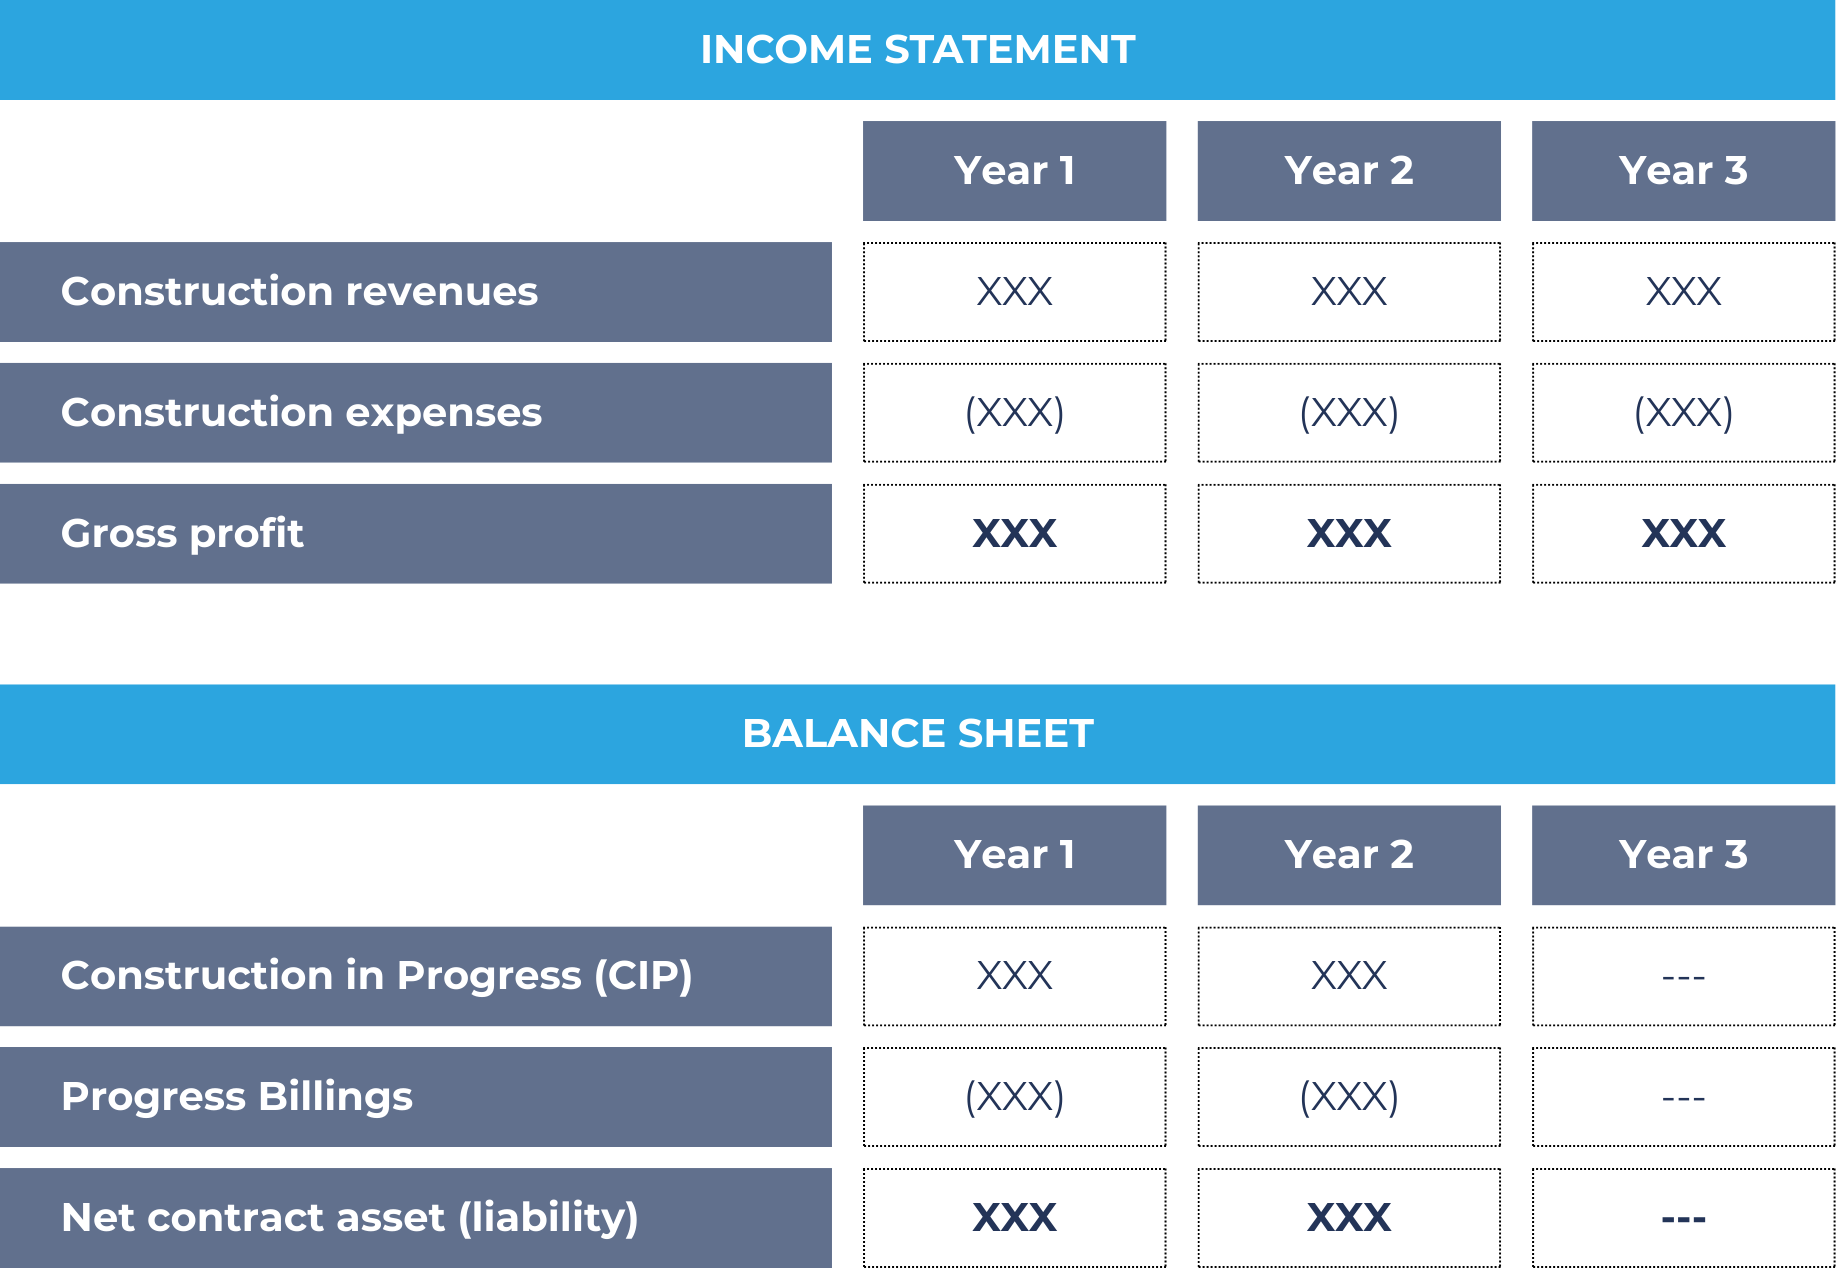
The pro forma presentation for the income statement and balance sheet is presented below. Notice that the main difference of this method when compared to the point in time recognition method is the presence of income statement items in Years 1 and 2, despite the contract not yet concluded.

Financial statements impact of over time recognition
Achievable

Over time recognition overview

  • Used when performance obligation is satisfied over time (one of three criteria: simultaneous receipt/consumption, creates/enhances customer-controlled asset, or no alternative use + enforceable right to payment)
  • Unlike point-in-time method, income statement affected every year-end until contract concludes
  • Construction contracts use percentage of completion method; CIP account accumulates both actual costs AND recognized gross profit (not just costs)

Step 1-2: Percentage of completion & total gross profit

  • Cost-to-cost (input) method formula: % complete=Actual costs incurred to date+Estimated costs to completeActual costs incurred to date​
  • Total estimated gross profit = Contract price − costs incurred to date − estimated costs to incur
  • Estimated losses recognized immediately in full; gross profits recognized piecemeal via % of completion
  • If contract turns loss-making after prior profit recognized: Current-period loss=Total expected contract loss+gross profit previously recognized

Step 3: Revenue and gross profit to recognize

  • Revenue to date = Contract price × % completion; current period revenue = revenue to date − prior periods’ recognized revenue
  • Gross profit to date = Total estimated GP × % completion; current period GP = GP to date − prior periods’ recognized GP
  • In profitable periods, construction expense = actual costs incurred; in loss periods, construction expense = current-period revenue + current-period loss

Step 4: Journal entries

  • Costs incurred: debit CIP, credit cash/AP (same as point-in-time)
  • Revenue/profit recognition (key entry): debit construction expense (actual costs, or revenue+loss if loss period), debit CIP for gross profit (credit CIP if loss period), credit construction revenues for period’s revenue
  • Progress billings: debit A/R, credit progress billings (contra-asset to CIP, not a liability)
  • Collections: debit cash, credit A/R (progress billings unaffected)
  • Contract conclusion: close CIP against progress billings directly (not to expense/revenue accounts as in point-in-time method)

Balance sheet presentation (CIP vs. Progress Billings)

  • CIP and progress billings are netted on balance sheet
  • CIP>progress billings → net contract asset (unbilled revenue)
  • CIP<progress billings → net contract liability (unearned revenue)

Worked example takeaway

  • Shows mechanics across 3 years: Years 1-2 profitable (30%, then 70% completion), Year 3 cost overrun creates overall $50,000 loss
  • Demonstrates loss reversal: current-period loss must offset previously recognized profit plus record full expected loss, so cumulative GP equals total contract loss

Sign up for free to take 11 quiz questions on this topic

Previous
Next  | 1.2.12.1 Learning outcomes
All rights reserved ©2016 - 2026 Achievable, Inc.

Over time recognition method

Over time recognition method

When the contract requires some time to perform, and the performance obligations meet the criteria of being satisfied over time, the company records revenues, cost of sales and gross profit as the company fulfills its obligations in the contract.

This means that unlike the previous case of point in time recognition, the income statement is affected every year-end that the contract is not concluded.

For revenue to be recognized over time, any one of the criteria below must be met:

  1. There is simultaneous receipt and consumption of the benefits provided by the company’s performance of the obligations from the contract
  2. The company’s performance of the obligations from the contract enhances or creates an asset controlled by the customer
  3. The company’s performance of the obligations from the contract does not create an asset with an alternative use to the company, and the company has an enforceable right to payment for performance completed to date.

Recognition of the revenues can be straight-forward for some contracts in which the revenue is recognized on a straight-line basis. However, accounting for a construction contract can be more complex due to the application of the percentage of completion method. The following are the steps to follow in applying the method:

  1. Calculate the percentage of completion
  2. Calculate the total gross profit from the contract
  3. Calculate the revenue and gross profit to be recognized to date
  4. Record the relevant year-end journal entries
  5. Understand the financial statement presentation

Long-term contracts recognized over time use specific accounts that aren’t common in other types of transactions:

The accounts are used the same way as in point-in-time recognition, with one key difference: the CIP account accumulates both the actual costs incurred to date and the gross profit recognized to date, not just the costs.

Step 1: Calculate the percentage of completion

The percentage of completion is calculated every end of the year to track the progress of the project.

There are two possible methods that companies can use depending on the specific circumstances of the project:

  • Output method which calculates the progress based on the value the customer has obtained from the contract such as number of units produced.
  • Input method which calculates the progress of the project using the inputs used in the construction such as consumed resources, labor hours, etc.

Exams most often use the input method, also called the cost-to-cost method.

Percentage of completion=Actual costs incurred to date+Estimated costs to completeActual costs incurred to date​

The denominator is also called total estimated contract costs. In the exams, candidates should be careful in determining the type of costs provided by the problem because it can provide directly the total estimated costs or a breakdown of it.

The examples moving forward pertain to the input method.

Step 2: Calculate the total gross profit from the contract

The total gross profit from the contract should also be calculated every year-end.

This is the estimated total profit that the company is expecting to obtain at the conclusion of the contract. The inputs used in the computation are similar to a normal gross profit computation as follows:

Contract price XX
Less: costs incurred to date (XX)
Less: estimated costs to incur (XX)
Estimated gross profit (loss) on the contract XX (XX)

This portion is important because, just like in point in time recognition method, estimated losses on a contract are also recognized immediately in full despite the percentage of completion while gross profits are recognized on a piecemeal basis using the percentage of completion computed from the previous step.

Reversal of previously recognized gross profit when a contract becomes loss-making

If revised estimates show that a contract will produce an overall loss, U.S. GAAP requires recognizing the entire expected loss immediately, even though the contract isn’t finished. Because prior periods may already have recognized gross profit, the current-period loss must be large enough to both reverse that prior profit and report the full expected loss as of this date:

Current-period loss=Total expected contract loss+gross profit previously recognized

Step 3: Calculate the revenue and gross profit to be recognized to date

For over time recognition of revenues, the following items are needed for the journal entries:

The revenues to be recognized in the current period is calculated as follows:

Contract price XX
Multiply: percentage of completion %
Total revenues to be recognized to date XX
Less: revenues recognized in prior periods (XX)
Total revenues to be recognized in the current period XX

The gross profit to be recognized follow the same logic as above except that the main input is the gross profit computed from the previous step:

Total estimated gross profit from the contract XX
Multiply: percentage of completion %
Total estimated gross profit to be recognized to date XX
Less: gross profits recognized in prior periods (XX)
Gross profit to be recognized in the current period XX

The costs to be recognized in a profitable period are simply the actual costs incurred in the current period - no special computation is needed. In a loss period, though, construction expense is no longer just the actual costs incurred: it equals the current-period revenue recognized plus the current-period loss, since the full loss must be recognized immediately (see the callout above).

In a profitable period, revenue minus actual costs incurred for the period equals the gross profit computed above; that consistency is the basis for the year-end journal entries in step 4.2 below.

Step 4: Record the relevant year-end journal entries

The accounts to be used for this method are the same as the point in time recognition method but the journal entries are different because of the recognition of the gross profit in each year-end.

Step 4.1: Contract costs are accumulated in the CIP account similar to the previous method.

Debit construction in progress (CIP) and credit cash and/or accounts payable for the actual costs incurred during the period - the same entry used in the point-in-time method. Because CIP is a balance sheet account, these costs accumulate there and become an input to the total estimated contract costs formula from step 1.

Step 4.2: Contract revenues are recorded along with the gross profit.

This journal entry is specific to the over time recognition method. In this journal entry, we use the inputs determined in the preceding steps.

Account Debit Credit Financial statement element
Construction expense XXX Expense
Construction in progress (CIP) XXX Asset
Construction revenues XXX Revenue
To record the gross profit for the period

The sections of the journal entry are:

  • The debit in construction expense should be the same amount as the debit in CIP in the previous journal entry to record the actual construction costs - this holds in a profitable period. In a loss period, construction expense instead equals the current-period revenue recognized plus the current-period loss (see step 3).
  • The debit in CIP account is the gross profit computed in Step 3. In a loss period, this line is a credit instead of a debit, since CIP is reduced by the loss rather than increased by a profit.
  • The credit in construction revenues should be the same as the “revenue to be recognized in the current period” computed in Step 3

After the above journal entry, the CIP account in the balance sheet accumulates two items:

  1. actual costs incurred to date; and
  2. gross profit recognized to date.

This total makes it the same as the total revenues recognized to date. It is important to know this fact in relation to the nature of the Progress Billing account which will be discussed in the next journal entry.

The example below walks through steps 1-3 and this step 4.2 entry for two profitable years, then a third year in which revised estimates turn the contract into a loss.

Example: applying the percentage-of-completion method

Ace Builders signs a contract to construct a warehouse for a contract price of $1,000,000. Total estimated contract costs are $600,000, so the total estimated gross profit on the contract is $400,000.

Year 1: Actual costs incurred to date are $180,000, and estimated costs to complete are $420,000.

  • Percentage of completion: $180,000+$420,000$180,000​=30%
  • Revenue to recognize in Year 1: 30%×$1,000,000=$300,000
  • Gross profit to recognize in Year 1: 30%×$400,000=$120,000
  • Costs incurred in Year 1: $180,000
  • Year 1 journal entry (Step 4.2): debit construction expense $180,000, debit CIP $120,000, credit construction revenues $300,000

Year 2: By year-end, actual costs incurred to date total $420,000 (an additional $240,000 spent during the year), and estimated costs to complete have dropped to $180,000.

  • Percentage of completion: $420,000+$180,000$420,000​=70%
  • Revenue recognized to date: 70%×$1,000,000=$700,000; less the $300,000 recognized in Year 1 leaves $400,000 to recognize in Year 2
  • Gross profit recognized to date: 70%×$400,000=$280,000; less the $120,000 recognized in Year 1 leaves $160,000 to recognize in Year 2
  • Year 2 journal entry (Step 4.2): debit construction expense $240,000, debit CIP $160,000, credit construction revenues $400,000

Year 3: Unexpected delays push total estimated contract costs up to $1,050,000, turning the contract into a $50,000 loss ($1,000,000 contract price − $1,050,000 total estimated costs). The project is completed by year-end, so actual costs incurred to date reach the full $1,050,000 and revenue recognized to date reaches the full $1,000,000.

  • Revenue to recognize in Year 3: $1,000,000 total − $700,000 recognized in Years 1 and 2 = $300,000
  • Current-period loss: the $50,000 total expected loss plus the $280,000 of gross profit already recognized = $330,000 (this reverses the prior profit and brings cumulative income down to the full $50,000 loss)
  • Year 3 journal entry (Step 4.2): debit construction expense $630,000 (the $300,000 revenue recognized plus the $330,000 loss), credit CIP $330,000 (the loss - CIP is credited, not debited, in a loss period), credit construction revenues $300,000

Answer: Cumulative gross profit (loss) after Year 3 is $120,000 + $160,000 − $330,000 = −$50,000, matching the $50,000 total loss now expected on the contract.

Step 4.3: Progress billings are recorded the same way as the point in time recognition method.

Debit accounts receivable and credit progress billings for the amount billed to the customer - the same entry as in the point-in-time method. Progress billings is a contra-asset account that offsets CIP, not a liability in its own right; only the net balance of the two accounts appears on the balance sheet, as a contract asset or a contract liability.

The progress billings account is a contra-asset account (to CIP) with a normal credit balance representing the portion of the contract price that has already been billed to the client. This is separate from the revenues recognized using the percentage of completion because the billings may be calculated using a different approach.

As mentioned previously, the revenues recognized on the contract are actually accumulated in the Construction in progress (CIP) account in the balance sheet with a normal balance in the debit side.

Both accounts (CIP and progress billings) are presented at net in the balance sheet at year-end with the following implications:

  • If CIP>progress billings: means there is a net contract asset. This can also be understood as an unbilled revenue since the revenues recognized to date are greater than the revenues billed from the customer.
  • If CIP<progress billings: means there is a net contract liability. This can also be understood as an unearned revenue since the company billed more than what was actually earned.

Step 4.4: Collections of accounts are recorded against the accounts receivable previously set-up, just like in a point in time recognition method.

Debit cash and credit accounts receivable for the amount collected - the same entry as in the point-in-time method. The progress billings account is not affected by collections.

Step 4.5: The conclusion of the contract is recorded by closing the CIP and progress billings accounts with each other.

Unlike the point in time recognition method where the CIP is closed to construction expenses and the progress billings are closed to construction revenues, the journal entry upon the conclusion of the contract for an over time recognition of revenue is to simply close the CIP against the progress billings account. This is possible because at the end of the contract, the total revenues recognized to date (i.e., CIP) should be equal to the progress billings since we will bill the contract price in full.

Account Debit Credit Financial statement element
Progress billings XXX Contra-asset (offsets CIP)
Construction in progress (CIP) XXX Asset
To record the conclusion of the construction contract

Step 5: Understand the financial statement presentation

The pro forma presentation for the income statement and balance sheet is presented below. Notice that the main difference of this method when compared to the point in time recognition method is the presence of income statement items in Years 1 and 2, despite the contract not yet concluded.

Key points

Over time recognition overview

  • Used when performance obligation is satisfied over time (one of three criteria: simultaneous receipt/consumption, creates/enhances customer-controlled asset, or no alternative use + enforceable right to payment)
  • Unlike point-in-time method, income statement affected every year-end until contract concludes
  • Construction contracts use percentage of completion method; CIP account accumulates both actual costs AND recognized gross profit (not just costs)

Step 1-2: Percentage of completion & total gross profit

  • Cost-to-cost (input) method formula: % complete=Actual costs incurred to date+Estimated costs to completeActual costs incurred to date​
  • Total estimated gross profit = Contract price − costs incurred to date − estimated costs to incur
  • Estimated losses recognized immediately in full; gross profits recognized piecemeal via % of completion
  • If contract turns loss-making after prior profit recognized: Current-period loss=Total expected contract loss+gross profit previously recognized

Step 3: Revenue and gross profit to recognize

  • Revenue to date = Contract price × % completion; current period revenue = revenue to date − prior periods’ recognized revenue
  • Gross profit to date = Total estimated GP × % completion; current period GP = GP to date − prior periods’ recognized GP
  • In profitable periods, construction expense = actual costs incurred; in loss periods, construction expense = current-period revenue + current-period loss

Step 4: Journal entries

  • Costs incurred: debit CIP, credit cash/AP (same as point-in-time)
  • Revenue/profit recognition (key entry): debit construction expense (actual costs, or revenue+loss if loss period), debit CIP for gross profit (credit CIP if loss period), credit construction revenues for period’s revenue
  • Progress billings: debit A/R, credit progress billings (contra-asset to CIP, not a liability)
  • Collections: debit cash, credit A/R (progress billings unaffected)
  • Contract conclusion: close CIP against progress billings directly (not to expense/revenue accounts as in point-in-time method)

Balance sheet presentation (CIP vs. Progress Billings)

  • CIP and progress billings are netted on balance sheet
  • CIP>progress billings → net contract asset (unbilled revenue)
  • CIP<progress billings → net contract liability (unearned revenue)

Worked example takeaway

  • Shows mechanics across 3 years: Years 1-2 profitable (30%, then 70% completion), Year 3 cost overrun creates overall $50,000 loss
  • Demonstrates loss reversal: current-period loss must offset previously recognized profit plus record full expected loss, so cumulative GP equals total contract loss

More from Revenue recognition

  • Learning outcomes
  • Revenue recognition steps
  • Contract assets and contract liabilities
  • Revenue transactions
  • Point in time recognition method