



Point in time recognition method
For long-term contracts, CMA candidates need to understand the impacts of performance obligations that are satisfied:
- at a point in time; or
- over time
This chapter covers the point-in-time method, which applies under step 5 of the five-step revenue recognition model when a performance obligation doesn’t meet the over-time criteria; the next chapter, Over time recognition method, covers those criteria and the over-time method.
Point in time recognition method
When a contract requires some time to perform, but the performance obligations do not meet the criteria of being satisfied over time, the transactions the company enters into during the contract to fulfill its obligations are recorded only in the balance sheet as the contract progresses. The impact on net income (i.e., revenues, expenses) is recognized at a point in time - only when all performance obligations are satisfied.
However, as an application of the principle of conservatism, if there is already an estimated total loss on the contract, such losses should be recognized in the current period in full.
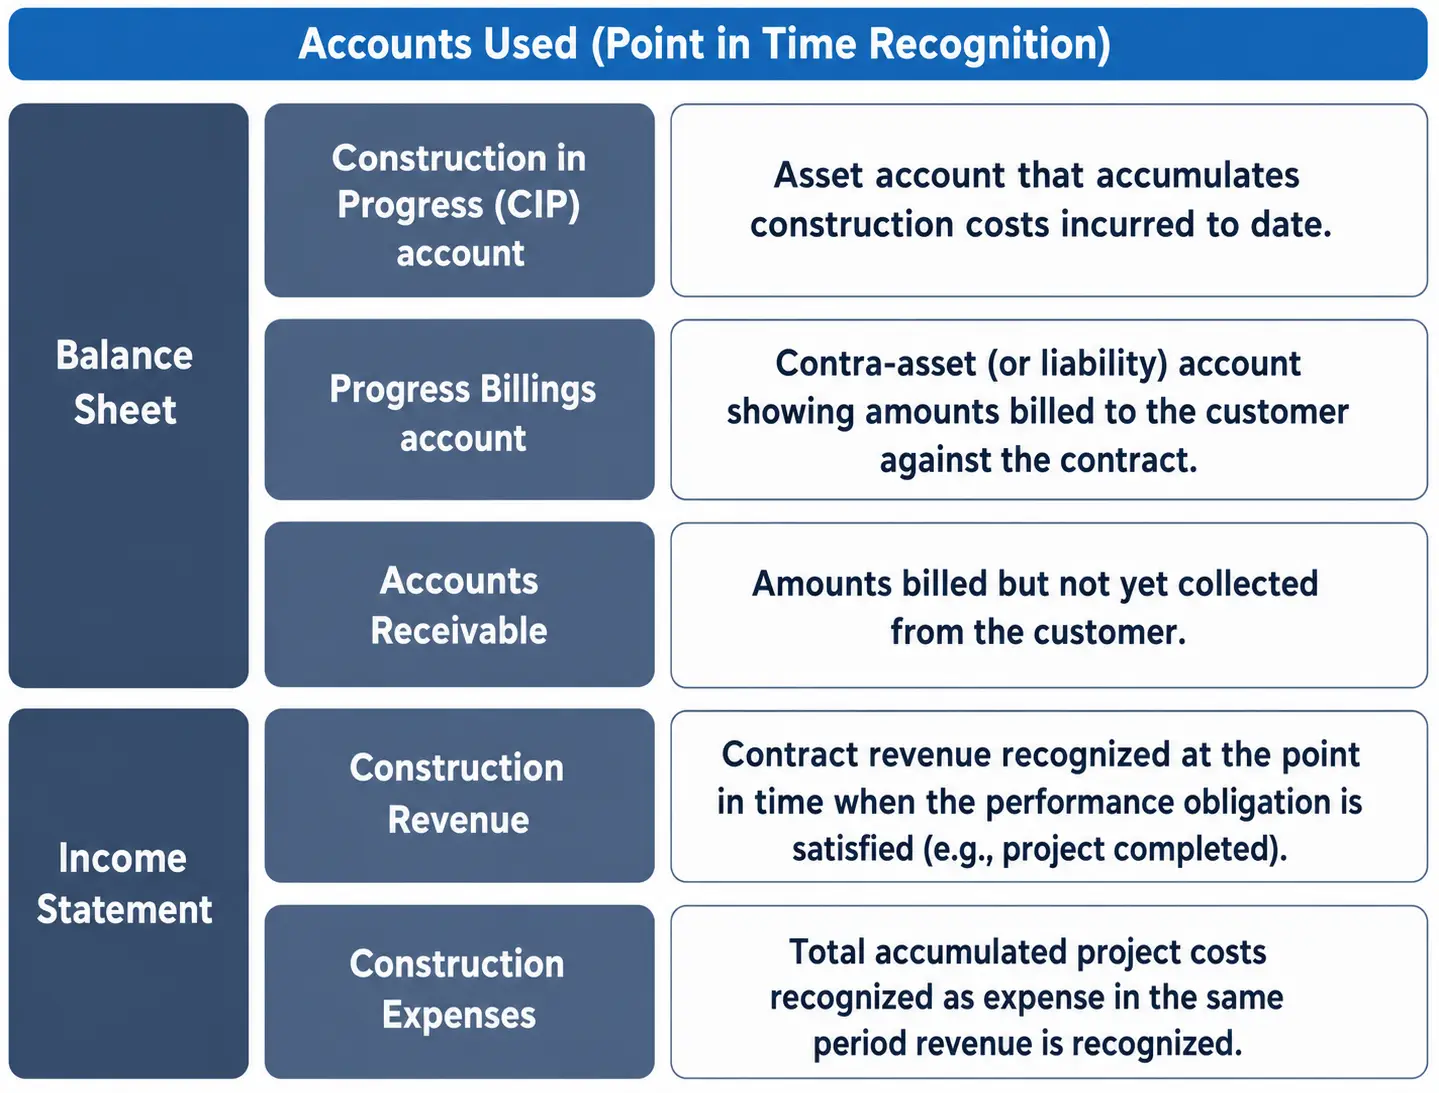
Accounting for long-term contracts in which revenues are recognized at a point in time use specific accounts that students need to be familiar with because they are not typically used in other types of transactions:
Recognition of contract costs
When the company incurs costs to satisfy the obligations under the contract such as payments of wages or other services to suppliers, they are not recorded in expenses but in a temporary account called the construction in progress (CIP). The CIP is typically an asset account but there are specific presentation guidelines discussed in the later subsection.
| Account | Debit | Credit | Financial statement element |
| Construction in progress (CIP) | XXX | Asset | |
| Cash | XXX | Asset | |
| Accounts payable | XXX | Liability | |
| To record the construction costs incurred | |||
Recognition of progress billings
Typically, when the company reaches a milestone as defined in the contract terms, a progress billing can be issued in the form of an invoice to the customer.
Although we already have the right to collect from the customer, the credit side of the journal entry is recorded against a liability account called progress billings because the performance obligations are not yet satisfied and no revenues should be recorded yet.
The progress billings is typically a liability account but there are specific presentation guidelines discussed in the later subsection.
| Account | Debit | Credit | Financial statement element |
| Accounts receivable | XXX | Asset | |
| Progress billings | XXX | Liability | |
| To record the progress billings | |||
Recognition of collections from customer
Collections from the customer are recorded against the previously established accounts receivables. The progress billings are not affected by collections.
| Account | Debit | Credit | Financial statement element |
| Cash | XXX | Asset | |
| Accounts receivable | XXX | Asset | |
| To record the collections of accounts receivables | |||
Notice that up to this point of the accounting, only assets and liabilities are impacted by the journal entries.
Recognition of revenues and expenses (profit making contract)
At the end of the contract when the performance obligations have been satisfied and control of the asset has been turned over to the customer, the company can finally recognize the revenues and expenses related to the contract.
Such revenues and expenses are simply taken from the cumulative balance of the construction in progress and progress billings accounts for the expenses and revenues, respectively.
| Account | Debit | Credit | Financial statement element |
| Construction expenses | XXX | Expense | |
| Construction in progress | XXX | Asset | |
| To close the CIP account at the end of the contract | |||
| Account | Debit | Credit | Financial statement element |
| Progress billings | XXX | Liability | |
| Construction revenues | XXX | Revenue | |
| To close the progress billings account at the end of the contract | |||
After the two journal entries above, you will notice that the gross profit from the contract can already be computed as the difference between the construction revenues and the construction expenses.
Recognition of estimated contract losses
The estimated total loss on the contract is calculated at the end of every period using the following formula:
| Contract price | XX |
| Less: costs incurred to date | (XX) |
| Less: estimated costs to incur | (XX) |
| Estimated profit (loss) on the contract | XX (XX) |
If the above calculation results in an estimated total profit from the contract, the amount is ignored and the profit continues to go unrecognized in the income statement until the contract is complete.
However, in the case of a loss, the following entry should be booked in addition:
| Account | Debit | Credit | Financial statement element |
| Loss on construction contract | XXX | Loss | |
| Construction in progress | XXX | Asset | |
| To recognize estimated losses on the construction contract | |||
The estimated loss is re-measured at the end of every period. Any revision, up or down, is treated as a change in estimate and recognized in the period of the revision, so the total income recognized over the contract’s life equals its actual profit or loss (ASC 605-35).
Financial statement presentation
In the balance sheet, every end of the period when the contract is not concluded, the company should determine the cumulative balance of the CIP and progress billings accounts:
Example: Point-in-time contract accounting
Achievable Construction Co. signs a contract to build a facility for a total contract price of $500,000. By the end of Year 1, the company has incurred $180,000 in construction costs and has billed the customer $150,000, of which $120,000 has been collected in cash. At year-end, management estimates that an additional $270,000 in costs remains to complete the contract.
Step 1: Record the year’s activity
- Debit CIP $180,000 / credit cash and accounts payable $180,000 for costs incurred.
- Debit accounts receivable $150,000 / credit progress billings $150,000 for the billing issued.
- Debit cash $120,000 / credit accounts receivable $120,000 for the collection - progress billings stays at $150,000, since collections don’t affect it.
Step 2: Test for an estimated loss
The contract still shows an estimated profit, so no loss entry is needed and no revenue or expense is recognized yet - the profit stays unrecognized in the CIP and progress billings accounts until completion.
Step 3: Determine the balance sheet presentation CIP ($180,000) is greater than progress billings ($150,000), so the $30,000 difference is a net contract asset, reported on the balance sheet as an asset.
Step 4: Year 2 - a revised estimate turns the contract into a loss During Year 2, the company incurs another $100,000 of costs (cumulative costs to date: $280,000) and issues additional progress billings of $200,000 (cumulative billings: $350,000). Rising material costs push the revised estimate of costs to complete up to $250,000.
Because this calculation now shows a loss, the full $30,000 must be recognized immediately: debit loss on construction contract $30,000 / credit CIP $30,000. This lowers the CIP balance to $250,000 ($280,000 - $30,000).
Comparing the updated balances, progress billings ($350,000) now exceeds CIP ($250,000), so the contract has flipped from a net asset to a $100,000 net contract liability.
Answer: Year 1 shows an unrecognized estimated profit of $50,000 and a $30,000 net contract asset. By the end of Year 2, the revised estimate produces a $30,000 loss (recognized in full that period) and the balance sheet position flips to a $100,000 net contract liability.
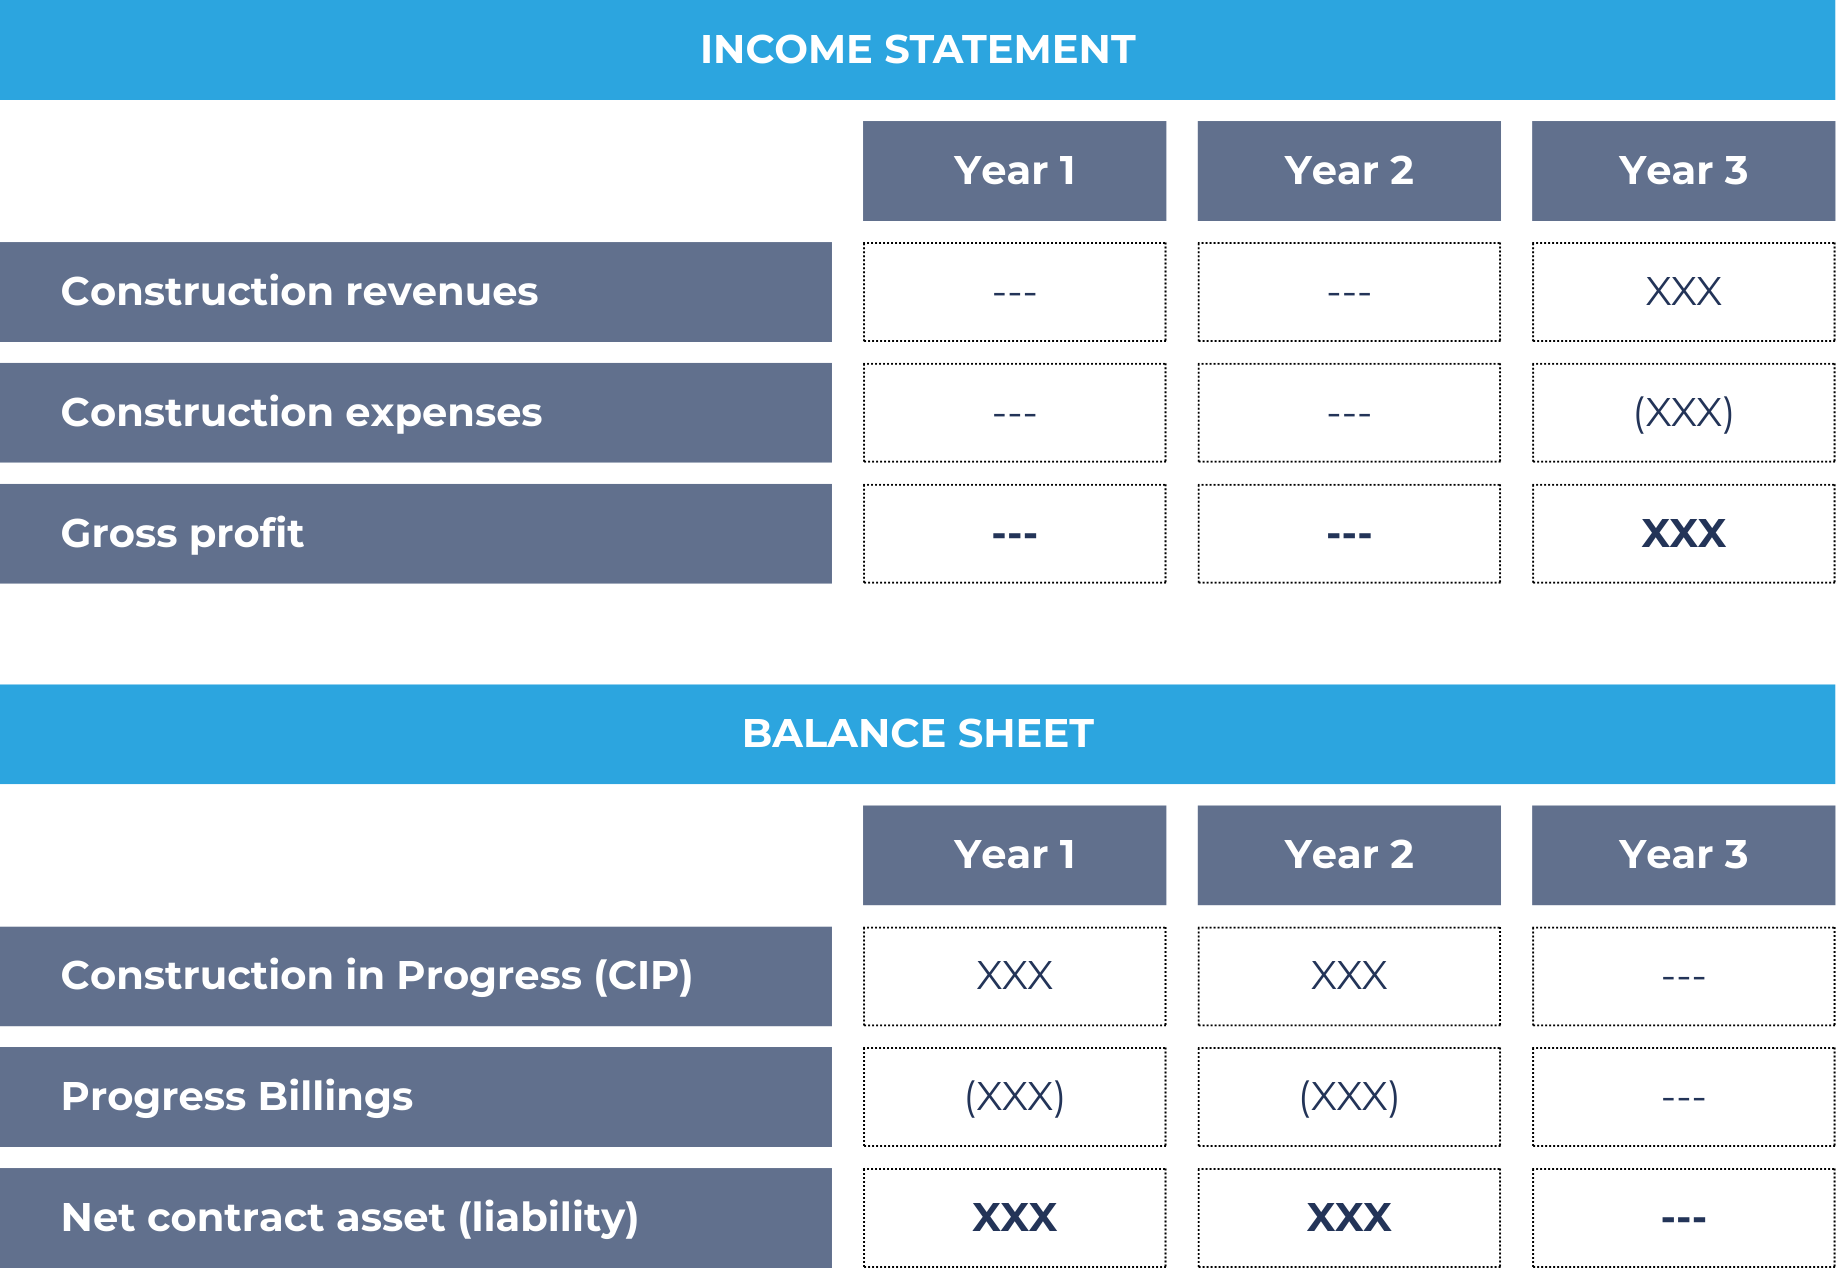
In the income statement, the revenues and expenses are only recognized during the conclusion of the contract when the revenues are recognized at a point in time. This means that no revenues or expenses are recognized at any year-end before the contract is complete, except when the contract has an estimated total loss. For example, see below sample presentation of a profit-producing contract that spanned three (3) years:
The CIP and progress billings accounts accumulate through Years 1 and 2, then close to the income statement in Year 3.