



Dwelling Policies (DP)
Purpose and eligibility
Dwelling policy forms are monoline policies used to insure residential property. You’ll typically use a dwelling property form to insure most dwelling property, including dwellings under construction. The dwelling may be owner-occupied or non-owner-occupied (rental property).
Most dwellings used for residential purposes are eligible for coverage under a dwelling form, except:
- farms
- structures with more than four units
- structures used principally for commercial or business purposes
Mobile homes may also be eligible if they’re permanently affixed to a foundation and endorsed.
Currently, the Dwelling '02 program is used in almost every state. This program incorporated language and policy provisions from the Standard Fire Policy into a dwelling policy to cover residential property.
The Dwelling '02 program consists of three policy forms, including the:
- Dwelling Property Basic Form (DP1 form)
- Dwelling Property Broad Form (DP2 form)
- Dwelling Property Special Form (DP3 form)
Perils insured against
The main difference between these forms is the causes of loss (perils) each policy covers.
Extended coverages
The extended coverage perils are:
- Windstorm
- Hail
- Aircraft damage
- Riot or civil commotion
- Vehicle damage
- Volcanic eruption (other than loss caused by earthquake, land shock waves or tremors)
- Explosion (does not have to be internal)
- Smoke damage
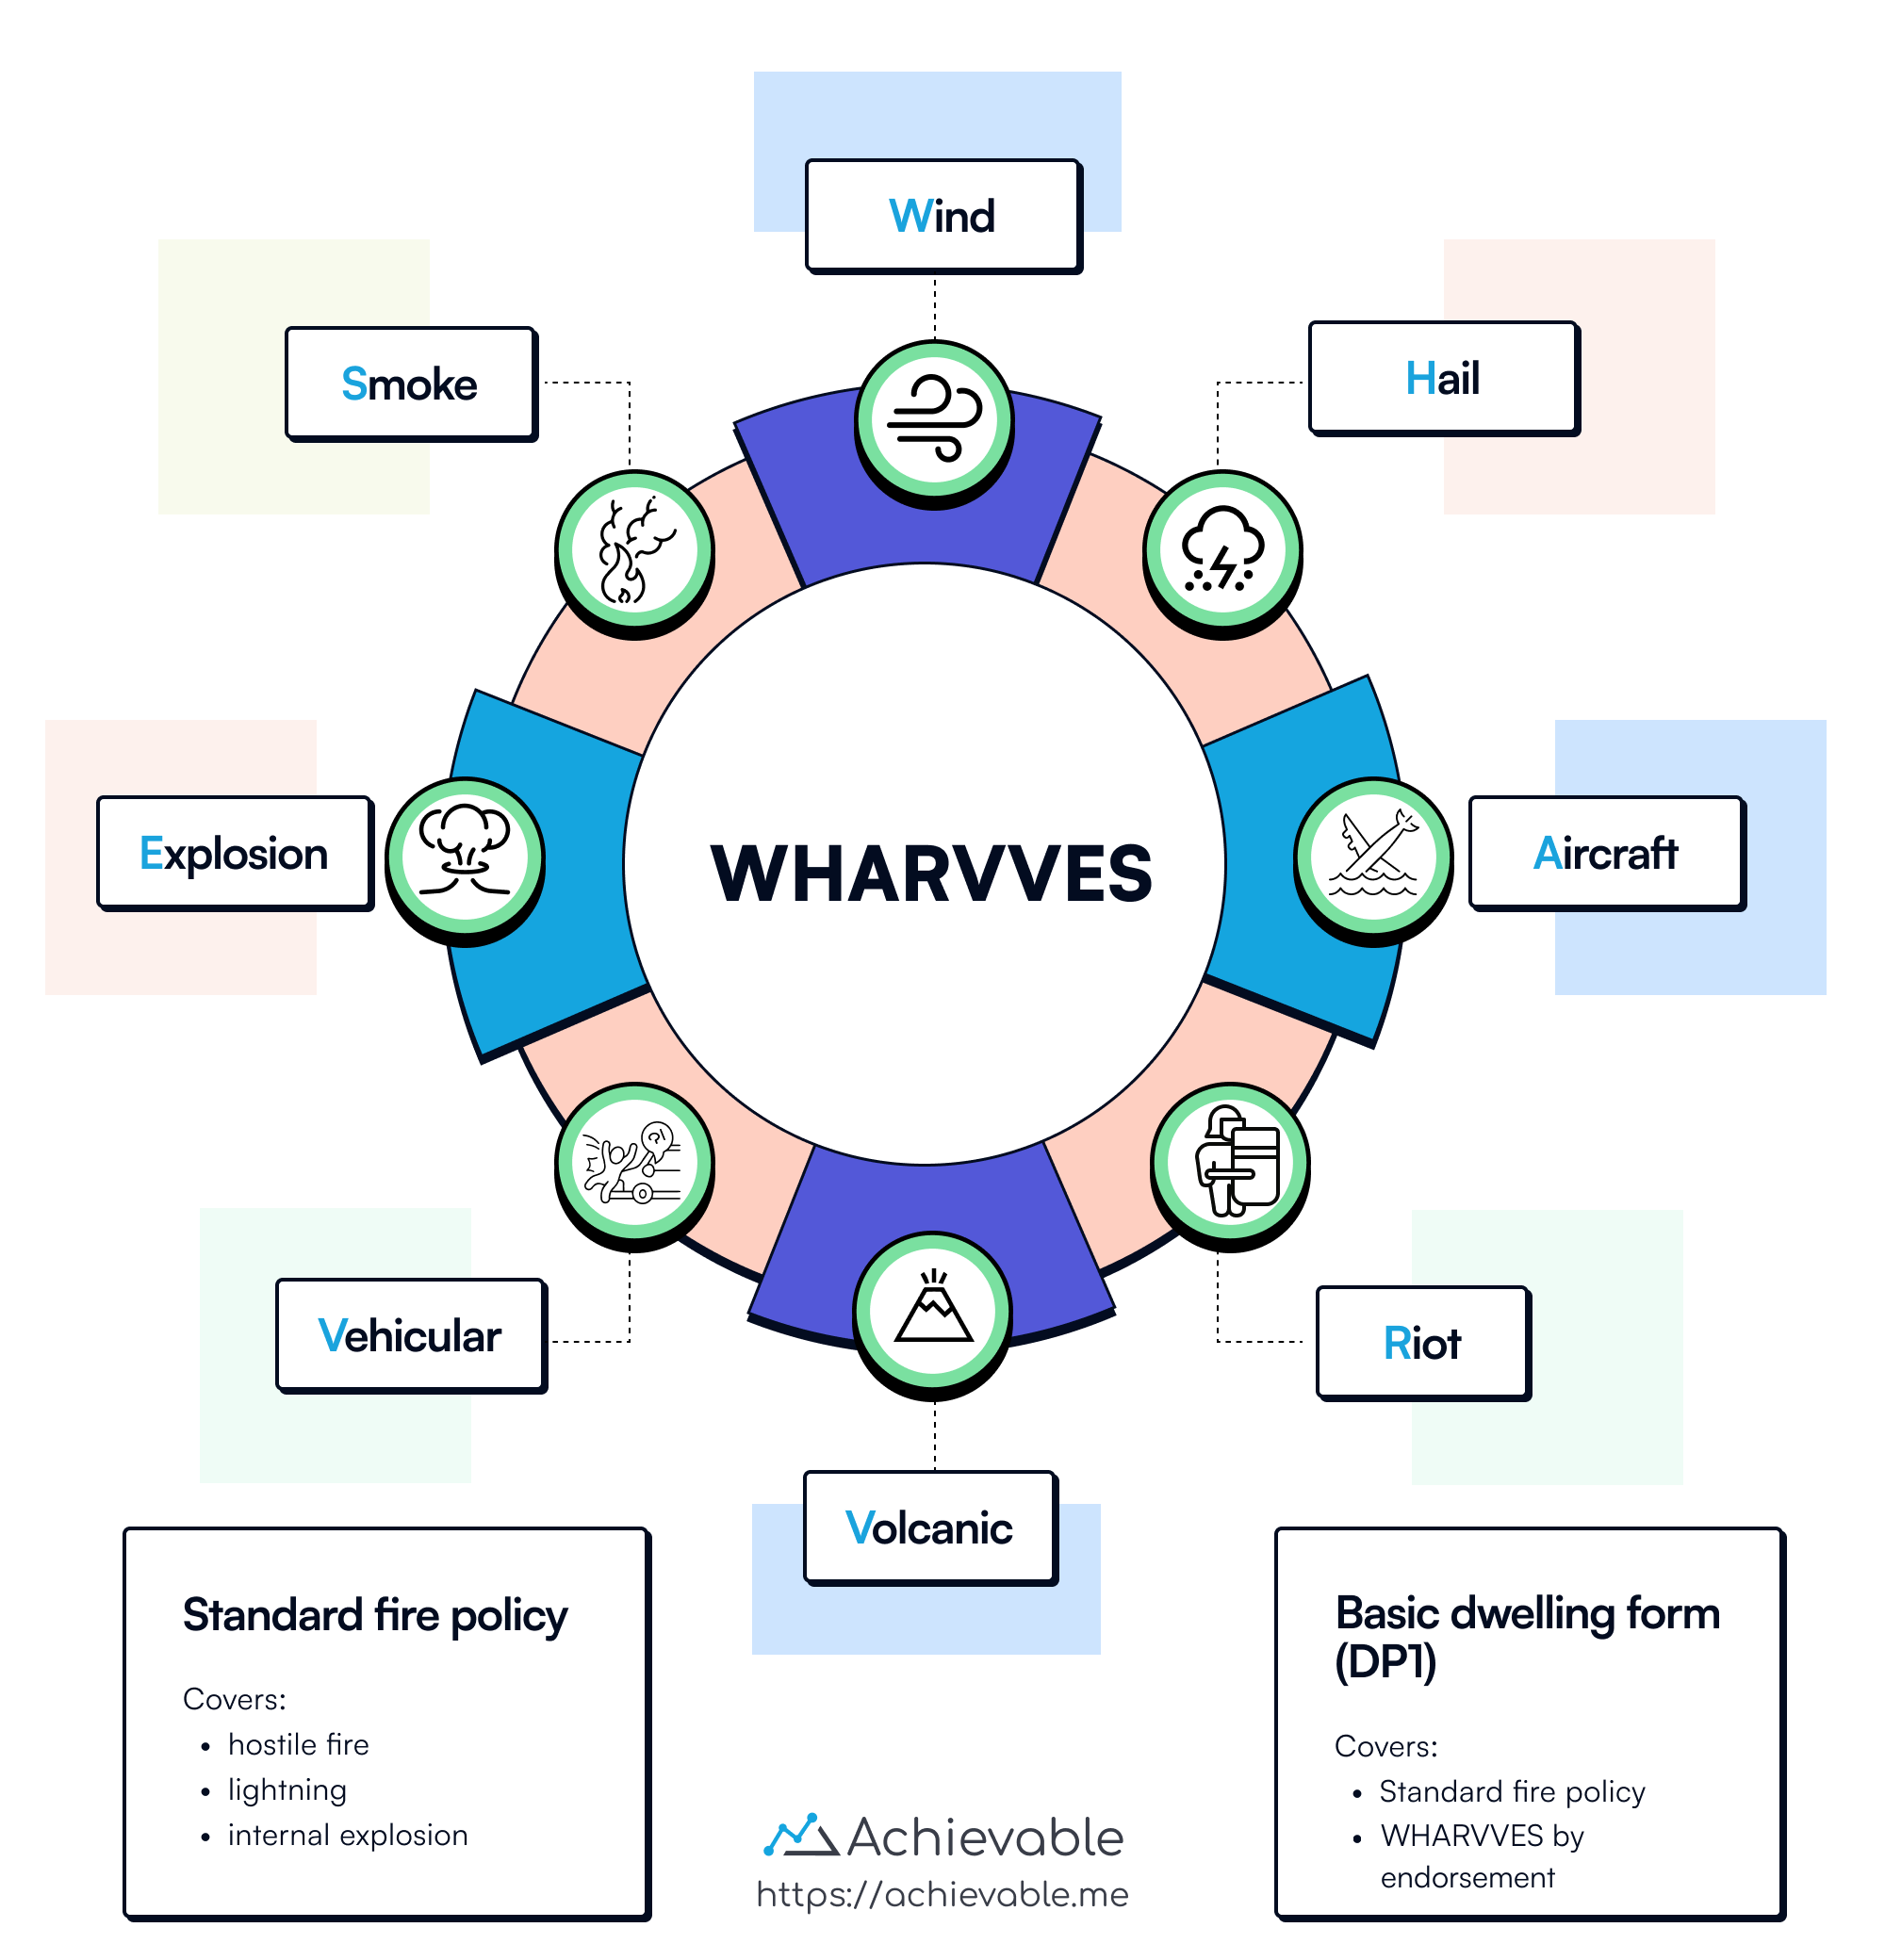
These extended coverages are automatically included in the DP2 and DP3 forms and may be added to the DP1 for an additional premium.
A common acronym for the extended coverages is WHARVVES.
Basic (DP1)
The DP1 provides the most limited coverage for dwellings and their contents compared to the DP2 and DP3 policies. DP1 covers:
- Hostile fire
- Lightning
- Internal Explosion
A hostile fire is burning in an area where it shouldn’t be burning. For example, if fire escapes from a wood-burning stove and damages other property, that damage would be covered.
A friendly fire is burning where it’s intended to burn (such as the fire contained within the wood-burning stove). Damage caused by a friendly fire is not covered.
Extended Coverage and Vandalism or Malicious Mischief (V&MM) may be added to the DP1 for an additional premium.
Broad (DP2)
The perils insured against in a DP2 policy include:
- all perils covered in a DP1 policy, and
- the perils appearing under Coverage C (named perils covering personal property)
Those additional named perils include:
- Weight of ice, snow, and sleet, which causes damage to property contained in the building.
- Loss or vandalism to covered property caused by burglars (burglary damage only, not theft itself).
- Loss caused by falling objects but not damage to fences, awnings, outdoor equipment, or outdoor radio and television antennas and aerials. Damage to the object that “falls” is not covered.
- Loss caused by accidental discharge or overflow (i.e., bursting pipes) of water or steam from plumbing, heating, air conditioning (A/C), or a fire-protective sprinkler system.
- Damage caused by the sudden and accidental tearing, cracking, burning, or bulging of a steam or hot water heating (i.e., bursting pipes), air conditioning, or protective sprinkler system.
- Loss due to the freezing of a plumbing, heating, A/C or, sprinkler system, or household appliance.
- Loss caused by artificially generated electrical current that results in sudden and accidental damage. Tubes, transistors, and similar components are not covered.
- Volcanic eruption (other than loss caused by shock waves or tremors.)
An acronym that can help you remember these is BIG AFFECT, as displayed below.
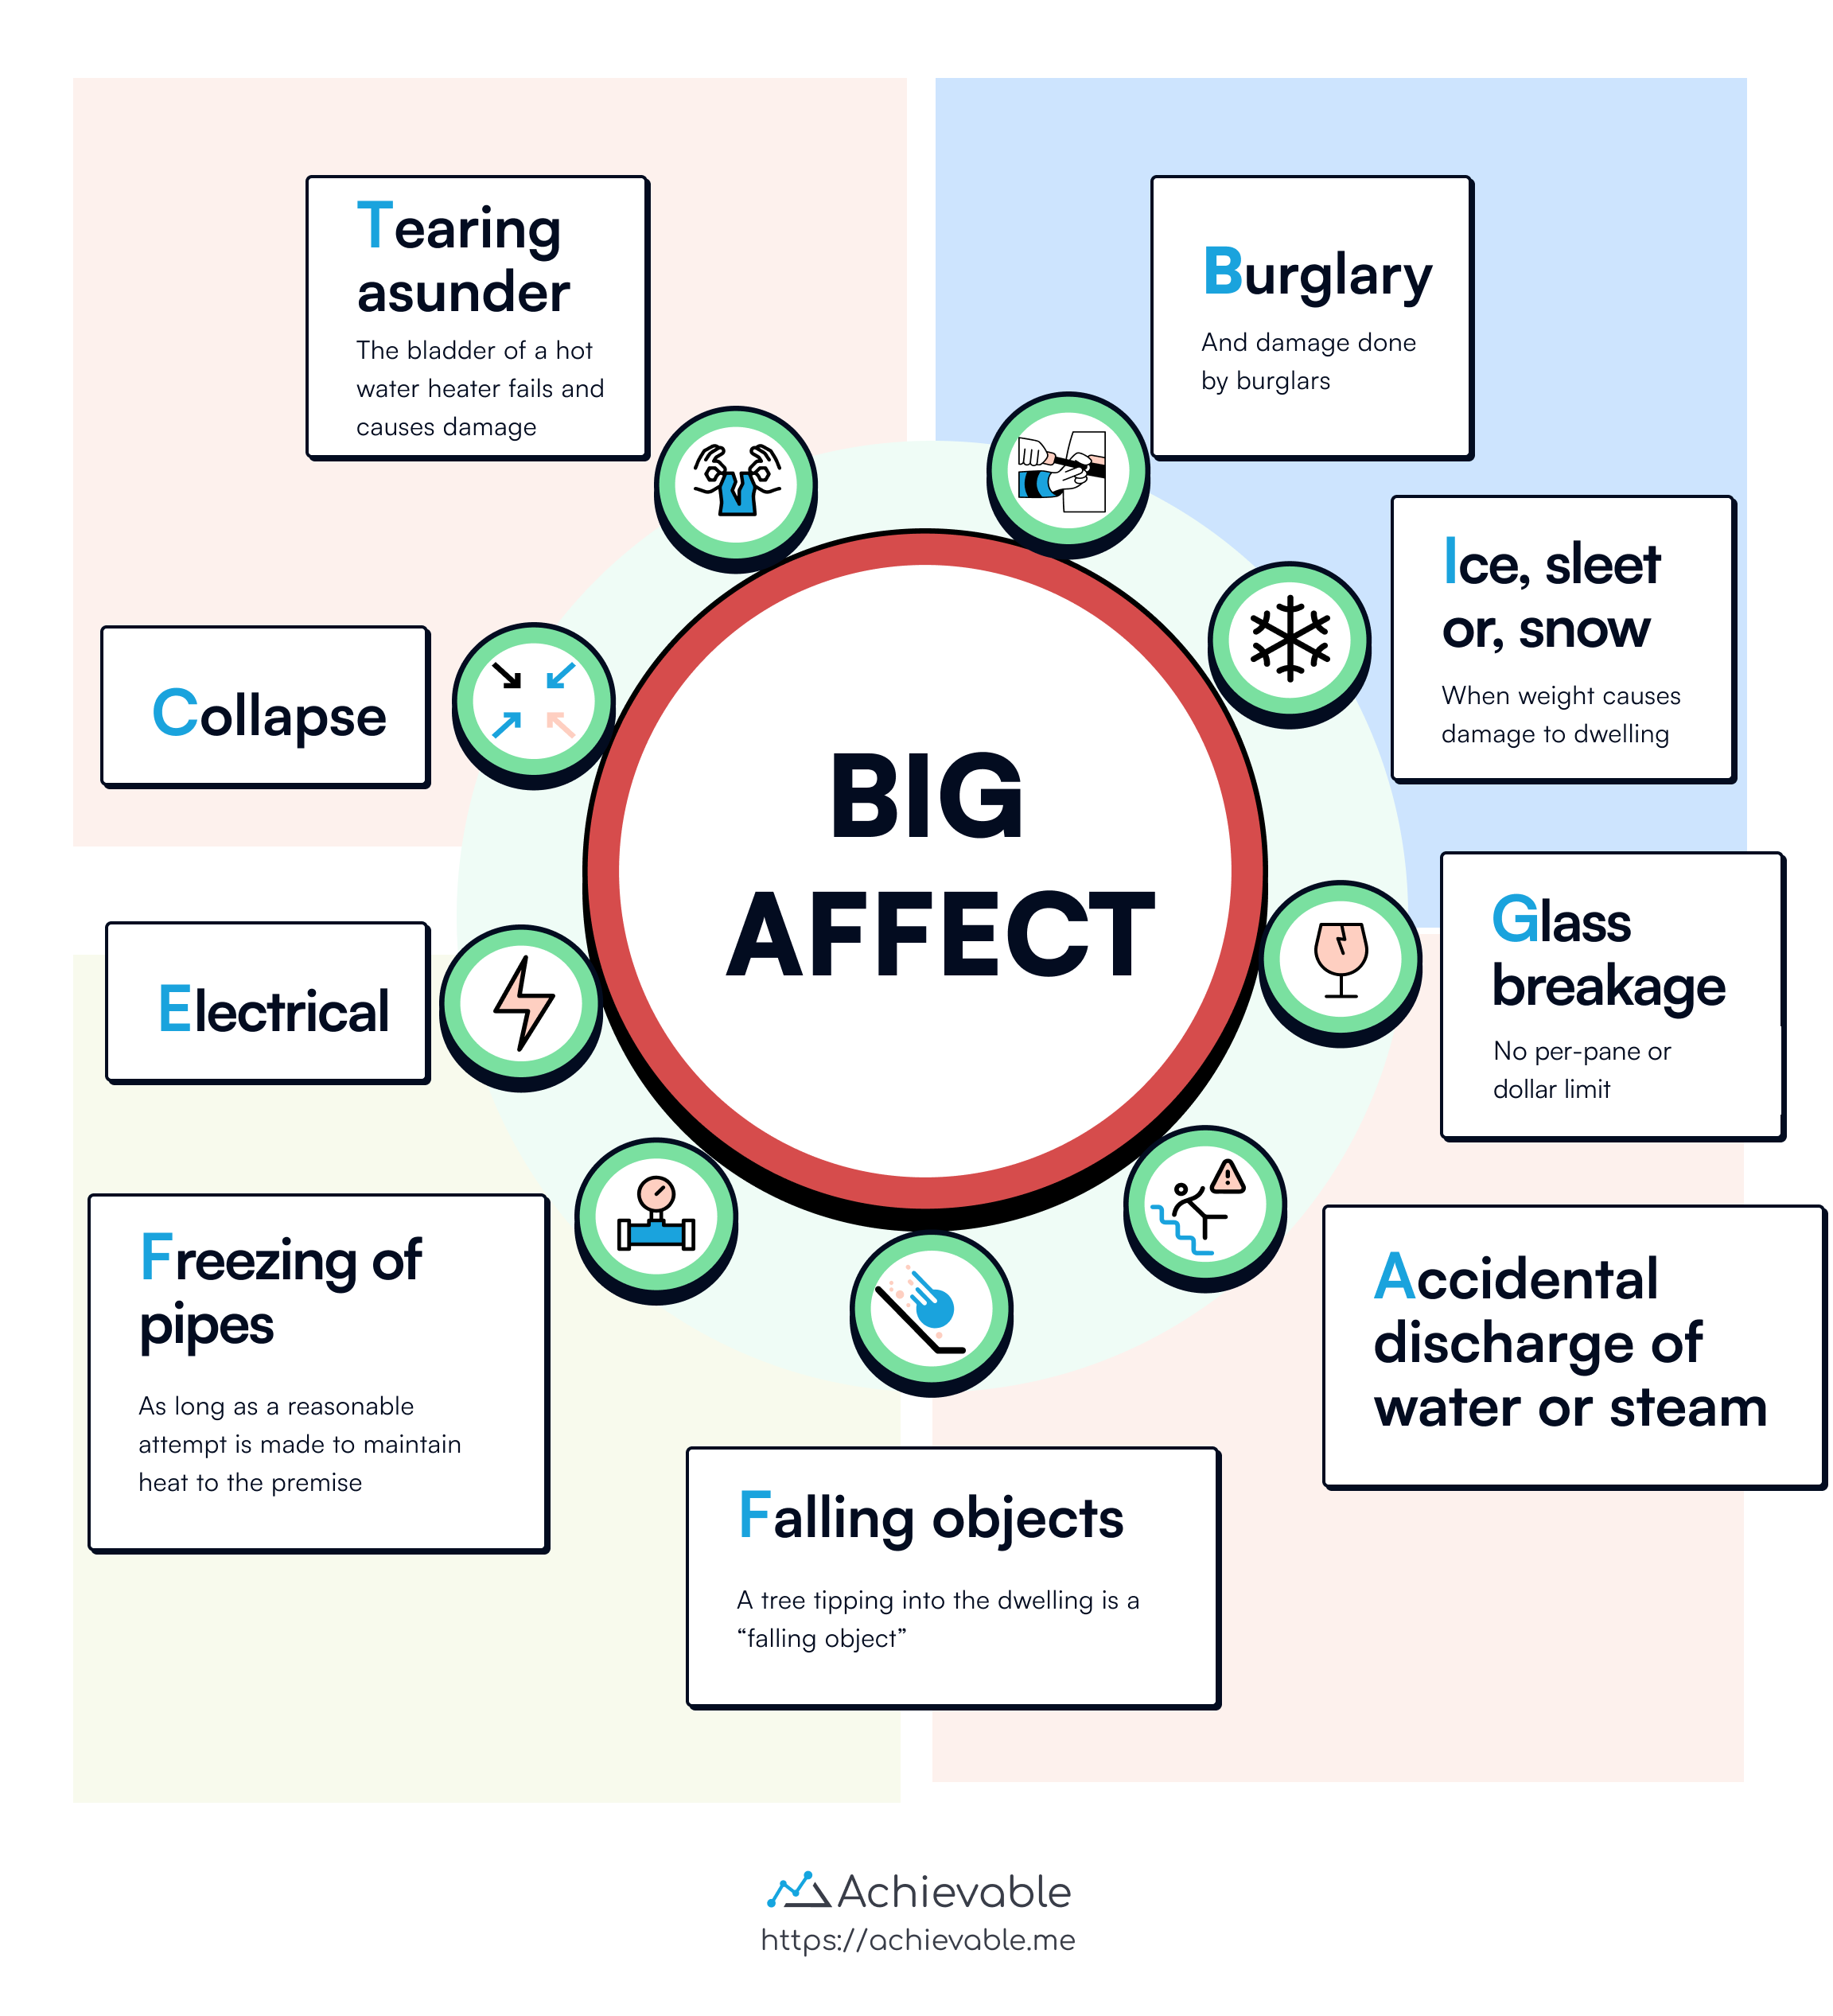
In addition to the above named perils, DP2 also provides coverage for Collapse and “Glass or Safety Glazing Material.”
The insurer will cover the breakage of glass or safety glazing material that is part of a covered dwelling, storm door, or storm window.
The DP-2 form also includes coverage for the breakage of glass or safety glazing material that is part of a covered building, such as windows or storm doors. There is no dollar or per-pane limit under the ISO Dwelling '02 form.
Collapse
The insurer will pay for direct physical loss to covered property involving the collapse of a dwelling (or any part of it) as a result of:
- A covered peril
- Hidden decay, or hidden insect or vermin damage, the insured did not know of
- Weight of contents, equipment, animals or people
- Weight of rain which collects on a roof
- Use of defective materials or methods, if the collapse occurs during construction, remodeling or renovation
Special (DP3)
The DP3 is an all-risk policy and provides the broadest protection of all the dwelling fire policies. The DP3 is similar in structure to the DP2, but it differs in an important way:
- Coverage A (dwelling) and Coverage B (other structures) are covered on an open-peril (all-risk) basis.
- Coverage C (personal property) remains named peril.
An all-risk policy covers all types of direct physical loss EXCEPT those specifically excluded.
This means that under a DP-3 policy, the dwelling and other structures are covered against all perils unless specifically excluded. To determine whether a loss is covered, you look at the exclusions, both the General Exclusions and those in the Perils Insured Against section. If the cause is not excluded, it is covered.
Dwelling property exclusions
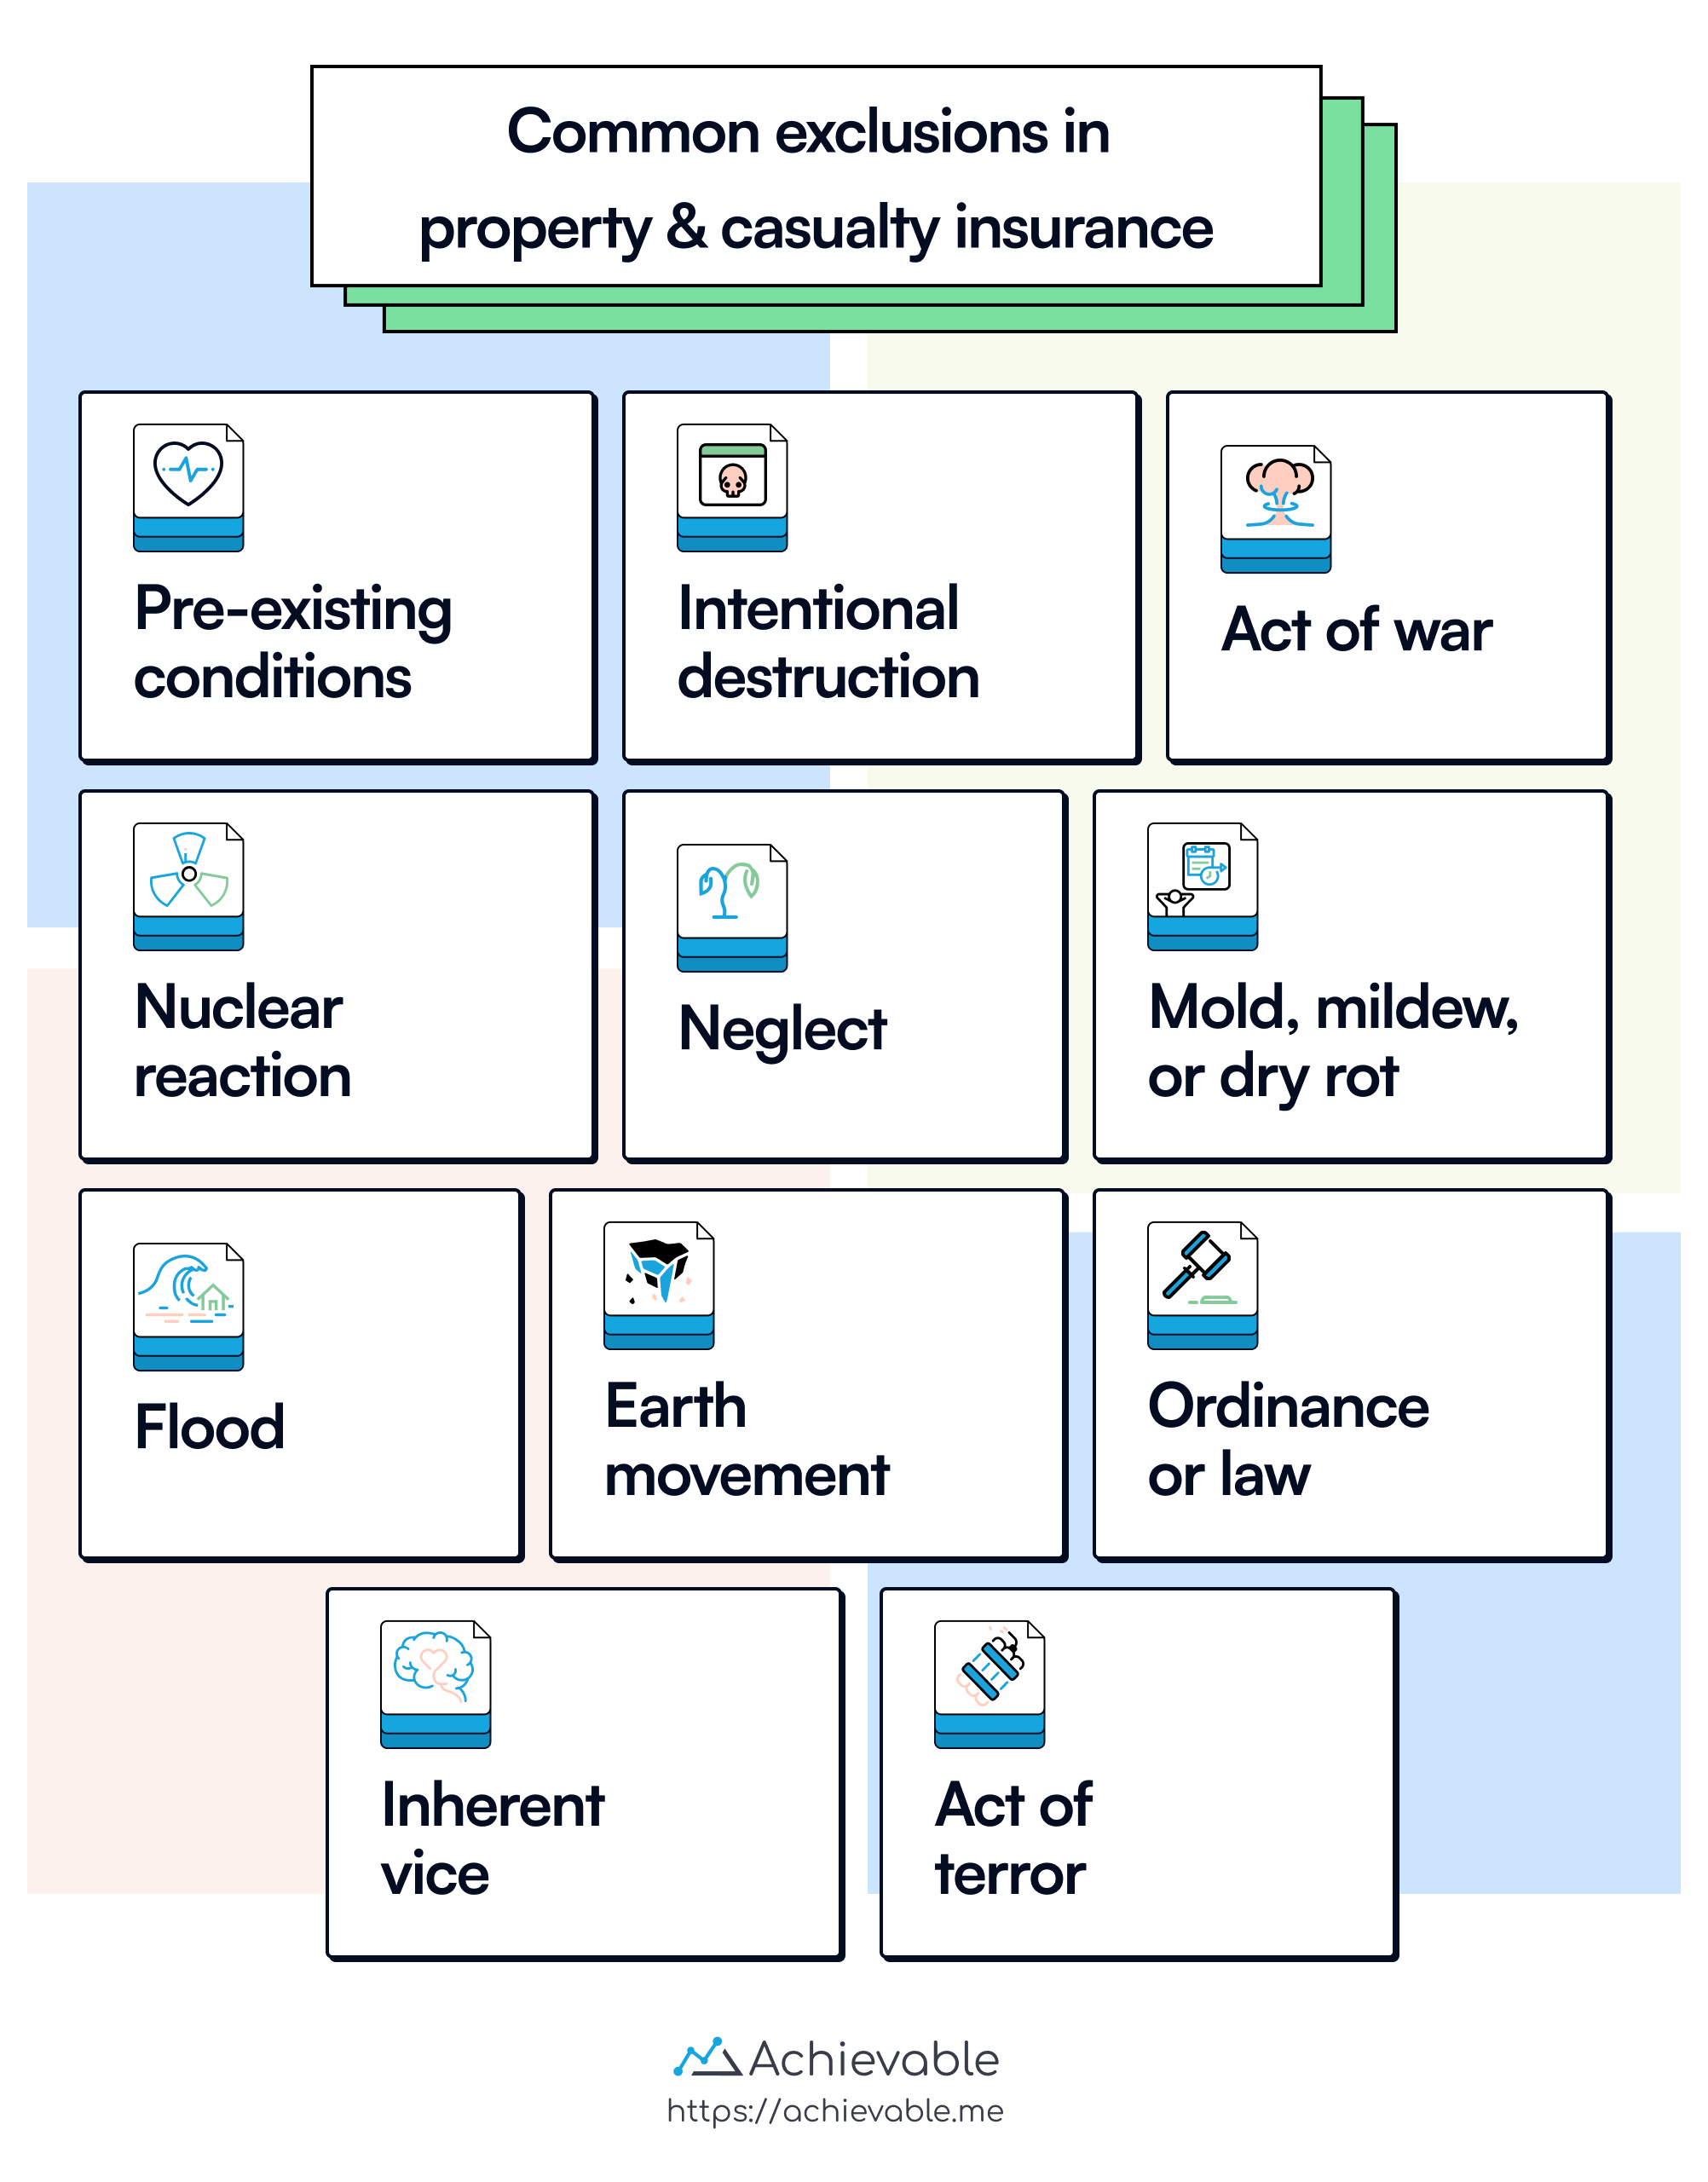
All three forms share nine general exclusions, which apply to every coverage. All policy forms exclude losses from:
- Ordinances or laws (Require more expensive reconstruction than was used in the original structure)
- Earth movement (Except for direct loss by fire or explosion resulting from earth movement)
- Land shock waves or tremors of a volcanic eruption (part of earth movement)
- Water damage
- Flooding
- Water back up into a building
- Water leaking or seeping from below ground
- Tidal surge
- Rapid run-off
- Mudslide
- Power interruption (Occurring away from the described location)
- Insured’s neglect (To save and preserve property following a loss)
- War and nuclear hazard
- Insured or someone else at the insured direction destroys property
- Governmental action (Seizure or destruction of property by order of a public authority, except to stop a fire from spreading)
The DP-2 and DP-3 give back a limited amount of ordinance or law coverage as an Other Coverage. The DP-1 has no such Other Coverage.
The DP-3 adds exclusions for its open-perils coverage of the dwelling and other structures only. They include inherent vice (a characteristic of property causing it to depreciate, spoil, break, or disintegrate), wear and tear, mold, wet or dry rot, vandalism or theft, and any loss that follows from an intentional and wrongful act committed in the course of it, once the dwelling has been vacant for more than 60 consecutive days immediately before the loss, weather conditions that combine with an excluded cause, the acts or decisions of any person or governmental body, and faulty planning, design, workmanship, materials or maintenance. An ensuing loss that is not itself excluded is covered.
Definitions
The dwelling forms define only two sets of terms. “You” and “your” mean the named insured shown in the declarations and the named insured’s spouse, if the spouse lives in the same household. “We,” “us” and “our” mean the insurance company. Other terms are explained where the forms use them: the described location is the property shown in the declarations, for example, and an internal explosion is an explosion inside the covered building.
When personal liability is added to a dwelling policy, the personal liability supplement adds its own definitions, such as insured, business, bodily injury, property damage, occurrence and residence premises, which work like the homeowners definitions.
Property coverages
DP1, DP2 and DP3 policies all provide four divisions of coverage, sometimes referred to as “insuring agreements.”
- Coverage A Dwelling
- Coverage B Other Structures
- Coverage C Personal Property
- Coverage D Fair Rental Value
Coverage A — Dwelling
This insuring agreement provides coverage for the dwelling principally used for residential purposes (owner- or non-owner-occupied).
Coverage A also includes:
- structures attached to the dwelling (such as an attached garage or carport)
- materials and supplies located on or next to the described location used to construct, alter or repair the dwelling or other structures on the described location
- building equipment and outdoor equipment used to service the described location and located on it, if not otherwise covered in the policy
Coverage B — Other structures
10% of Coverage A applies to structures on the described location detached from the dwelling by a clear space. “Other Structures” include:
- Garage not attached to the dwelling
- Swimming pool
- Cabana
- Any other structures on the premises connected to the dwelling by only a fence, utility line, or similar connection
Exclusions:
- Structures used for commercial, manufacturing or farming purposes. A structure that only contains such property, solely owned by the insured or a tenant of the dwelling, is covered, unless the property includes gaseous or liquid fuel other than fuel in a permanently installed tank of a vehicle or craft kept in it
- Structures rented or held for rental to anyone not a tenant of the dwelling, unless used solely as a private garage
- Damage to land
These exclusions apply to other structures under Coverage B. A structure attached to the dwelling is part of Coverage A, which has no exclusion for a structure used for commercial purposes; the dwelling itself must be used principally for dwelling purposes.
Coverage C — Personal property
Coverage C provides protection for the insured’s personal property owned or used by the named insured or resident family members.
-
Coverage C is optional on a dwelling policy. It applies only if a Coverage C limit is shown in the declarations, and the insured chooses that amount. Unlike a homeowners policy, there is no automatic Coverage C equal to a percentage of Coverage A.
-
Property away from the premises is covered anywhere in the world, but only up to 10% of the Coverage C limit, and any amount paid reduces the Coverage C limit for that loss. Rowboats and canoes are not covered away from the premises.
-
When personal property is moved to a newly acquired principal residence, the Coverage C limit applies at each residence for 30 days after the move begins, in proportion to the value of the property at each
Personal property not covered includes:
- Accounts
- Bills
- Currency, coins, bullion, gold, silver
- Deeds
- Securities
- Evidence of debt
- Manuscripts
- Passports
- Tickets
- Stamps
- Animals, birds, and fish
- Aircraft and its parts
- Motor vehicles (except those used to maintain or service the premises or assist the handicapped)
- Watercraft of all types, except rowboats and canoes (rowboats and canoes are covered)
- Electronic data and discs
- Credit card or fund transfer cards
- Property of roomer, renter, or boarder
Coverage D — Fair rental value
If part of the covered residence that is held for rental (or actually rented) to others becomes uninhabitable due to a covered loss under Coverage A, B, or C, the contract will pay the fair rental value.
Even without a Coverage D limit, the insured may use up to 20% of the Coverage A limit for lost fair rental value. On the DP-1, no more than 1/12 of that amount is paid for each month the rented part is unfit to use, and the payment reduces the Coverage A limit. On the DP-2 and DP-3, the 20% covers fair rental value and additional living expense combined, and it is additional insurance.
Coverage E — Additional living expense
Sometimes referred to as “Loss of Use,” this coverage section pays the insured’s necessary increased living expenses if a residence becomes uninhabitable due to a covered loss and the insured must move out while it’s being repaired, replaced, or rebuilt.
If a civil authority prohibits the insured from using the home because a covered peril, such as fire, has directly damaged a neighboring location, the policy pays additional living expense (and lost fair rental value) for up to two weeks. An evacuation because of a peril the policy does not cover, such as flood or disease, does not qualify.
Personal liability supplement
Dwelling policies (DP-1, DP-2, and DP-3) do not include personal liability or medical payments coverage.
If the insured wants this protection, it can be added by endorsement through the Personal Liability Supplement, which adds Coverage L (Personal Liability) and Coverage M (Medical Payments to Others), or by purchasing a separate Comprehensive Personal Liability (CPL) policy. Coverages L and M correspond to Coverages E and F of a homeowners policy.
The insureds include you (the named insured and a resident spouse), resident relatives, and other residents of your household under 21 who are in your care or the care of a resident relative. Neither coverage applies to injury or damage that an insured expects or intends, or that arises out of a business, professional services, premises an insured owns or rents that are not an insured location, aircraft, hovercraft, most motor vehicles (one used only to service a residence is covered) and larger watercraft, such as an owned sailboat 26 feet or longer or an owned boat with outboard motors of more than 25 total horsepower.
In addition to the limits, it pays claim expenses (defense costs, and up to $250 a day for earnings an insured loses assisting the defense at the insurer’s request), first aid expenses for others, and damage to property of others: up to $1,000 an occurrence, at replacement cost, for damage an insured causes, except intentional damage by an insured aged 13 or older.
Coverage L - Personal liability
Coverage L applies when a claim or suit is brought against an insured for damages because of bodily injury or property damage caused by an occurrence. The insurer pays the damages the insured is legally liable for, up to the limit for each occurrence, and provides a defense at its own expense, even if the suit is groundless, false or fraudulent.
Coverage L does not apply to most liability assumed by contract, loss assessments, damage to property an insured owns, damage to property an insured rents or has in its care (unless caused by fire, smoke or explosion), or bodily injury to you, to another insured in your household, or to a person eligible for workers’ compensation benefits that an insured provides or must provide.
Coverage M - Medical payments to others
Coverage M pays the necessary medical expenses of others incurred or medically ascertained within three years of an accident, up to the limit for each person, even if the insured is not liable.
It applies to a person on the insured location with an insured’s permission. Off it, the injury must arise out of a condition there or on the adjoining ways, or be caused by an insured’s activities, by a residence employee in the course of employment, or by an animal an insured owns or cares for. It does not pay for you, for anyone who regularly lives in your household or on the insured location (other than a residence employee), or for anyone eligible for workers’ compensation benefits.
Lesson summary
Dwelling policies are monoline policies used to insure residential properties. Here are some key points about dwelling policies:
-
Most dwelling properties are eligible for coverage, except farms and structures with more than four units or used mainly for commercial purposes. Mobile homes may qualify if permanently affixed and endorsed.
-
The Dwelling '02 program is utilized in most states, featuring three policy forms: Dwelling Property Basic Form (DP1), Dwelling Property Broad Form (DP2), and Dwelling Property Special Form (DP3).
Extended coverages included in DP2 and DP3 automatically (optional on the DP1 for an additional premium) are:
- Windstorm
- Hail
- Aircraft damage
- Riot or civil commotion
- Vehicle damage
- Volcanic eruption
- Explosion
- Smoke damage
Basic Coverage (DP1) includes coverage for:
- Hostile fire
- Lightning
- Internal Explosion
Extended Coverage and Vandalism or Malicious Mischief (V&MM) can be added for an additional premium.
Dwelling Property Broad Form (DP2) covers more perils than DP1, including all DP1 perils and additional ones like loss due to the weight of ice, snow, and sleet, vandalism by burglars, and accidental discharge or overflow of water or steam.
The Special Form (DP3) is an all-risk policy providing broad protection, covering all types of direct physical loss except for specific exclusions.
DP3 provides open-peril coverage for the dwelling (Coverage A) and other structures (Coverage B), but Coverage C remains named peril.
Dwelling policy coverages include:
- Coverage A: Dwelling
- Coverage B: Other Structures
- Coverage C: Personal Property
- Coverage D: Fair Rental Value
Exclusions from dwelling policies include losses from ordinances or laws, water damage, power interruption away from the described location, and governmental action.
Also excluded are earth movement, neglect, war, nuclear hazard and intentional loss.
Coverage B’s 10 percent limit is not additional insurance under DP-1 but is additional under DP-2 and DP-3