


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
CMA Part 1
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. External financial reporting decisions
2. Planning, budgeting, and forecasting
3. Performance management
3.1 Cost and variance measures
3.1.1 Comparison of actual to planned results
3.1.2 Calculating and interpreting variances
3.1.3 Flexible budgets
3.1.4 Management by exception and standard cost systems
3.2 Responsibility centers and reporting segments
3.3 Performance measures
4. Cost management
5. Internal control
6. Technology and analytics
Wrapping up
Achievable logoAchievable logo
3.1.1 Comparison of actual to planned results
Achievable CMA Part 1
3. Performance management
3.1. Cost and variance measures
Our CMA Part 1 course is currently in development and is a work-in-progress.

Comparison of actual to planned results

10 min read
Font
Discuss
Share
Feedback

Learning outcome statements

The learning outcome statements relevant for this section are:

  1. analyze performance against operational goals using measures based on revenue, manufacturing costs, nonmanufacturing costs, and profit depending on the type of center or unit being measured
  2. explain the reasons for variances within a performance monitoring system
  3. prepare a performance analysis by comparing actual results to the master budget, calculate favorable and unfavorable variances from the budget, and provide explanations for variances
  4. identify and describe the benefits and limitations of measuring performance by comparing actual results to the master budget

Performance analysis across key metrics

Now that the budgets are set, the next step is to measure the actual results against these budgets. This process is typically done by analyzing the differences between budgeted and actual results, referred to as variances.

Variance analysis provides a systematic approach to understanding where performance aligns with or deviates from expectations, helping organizations identify areas for improvement or celebration. Performance is assessed using key metrics tailored to the type of responsibility center or operational focus. These metrics typically include:

  1. Revenue
    Revenue analysis compares actual sales to budgeted sales, identifying variances caused by factors such as price changes, shifts in sales volume, or changes in product mix.
  2. Manufacturing costs
    Manufacturing costs include direct materials, direct labor, and manufacturing overhead. Variance analysis for these costs helps organizations pinpoint inefficiencies or unexpected changes in input costs or usage.
  3. Nonmanufacturing costs
    Nonmanufacturing costs, such as administrative and selling expenses, are critical to overall profitability. Monitoring these costs ensures they remain aligned with budgeted amounts.
  4. Profitability
    Profitability metrics, such as net income and contribution margin, provide an overarching perspective on performance. These metrics incorporate the combined effects of revenue and cost variances, offering a summary view of financial health.

Which measures matter most depends on the type of responsibility center: cost centers are evaluated mainly on manufacturing or nonmanufacturing costs, revenue centers on revenue, and profit or investment centers on profit measures such as contribution margin. Responsibility centers, covered in a later chapter, explains how each center type is evaluated in detail.

Understanding variances

Variance analysis is a fundamental tool in performance management, providing insights into how actual results compare to planned expectations. These “planned expectations” can be the budgets that we have already discussed and prepared in the previous sections or standards developed for production. Variances are categorized as either favorable or unfavorable, depending on their impact on organizational goals.

Definitions
Favorable variance
Occurs when actual results positively exceed expectations, improving profitability. For instance, in the context of revenues, a favorable variance might mean actual sales revenue exceeded the budgeted amount. With costs, a favorable variance occurs when actual costs are lower than budgeted, signaling efficient resource usage or cost savings.
Unfavorable variance
Occurs when actual results negatively deviate from expectations, reducing profitability. For revenues, this might mean lower-than-expected sales or average selling prices. For costs, an unfavorable variance occurs when actual expenses exceed budgeted amounts, possibly due to inefficiencies or unexpected price increases.

The first step in variance analysis is to calculate the total variance, which represents the overall difference between actual results and the master budget. This total variance provides a high-level picture of how well performance aligns with expectations and is expressed as:

Total variance=Actual results−Master budget results

Watch the sign: under Actual results−Master budget results, a positive number is favorable for revenue and profit but unfavorable for costs - higher actual revenue helps profitability, while higher actual costs hurt it. Always label a variance favorable (F) or unfavorable (U) by its effect on operating income, not by whether the subtraction comes out positive or negative. And remember: a favorable variance isn’t automatically good news - it can come from cutting corners, like skipping maintenance to save costs.

Example: Master budget vs. actual results

Achievable Co.'s master budget assumed 10,000 units sold at $20 per unit, variable costs of $12 per unit, and fixed costs of $50,000. Actual results were 9,000 units sold at $21 per unit, variable costs of $12.50 per unit, and fixed costs of $52,000.

Line item Master budget Actual Variance F/U
Revenue $200,000 $189,000 $11,000 U
Variable costs $120,000 $112,500 $7,500 F
Contribution margin $80,000 $76,500 $3,500 U
Fixed costs $50,000 $52,000 $2,000 U
Operating income $30,000 $24,500 $5,500 U

Answer: operating income came in $5,500 unfavorable overall. Notice that the variable cost variance looks favorable ($7,500 F) only because the company sold 1,000 fewer units than planned - the actual cost per unit was $12.50, higher than the $12.00 budgeted. A flexible budget (covered in a later chapter) removes this volume effect so the cost variance reflects price and efficiency only.

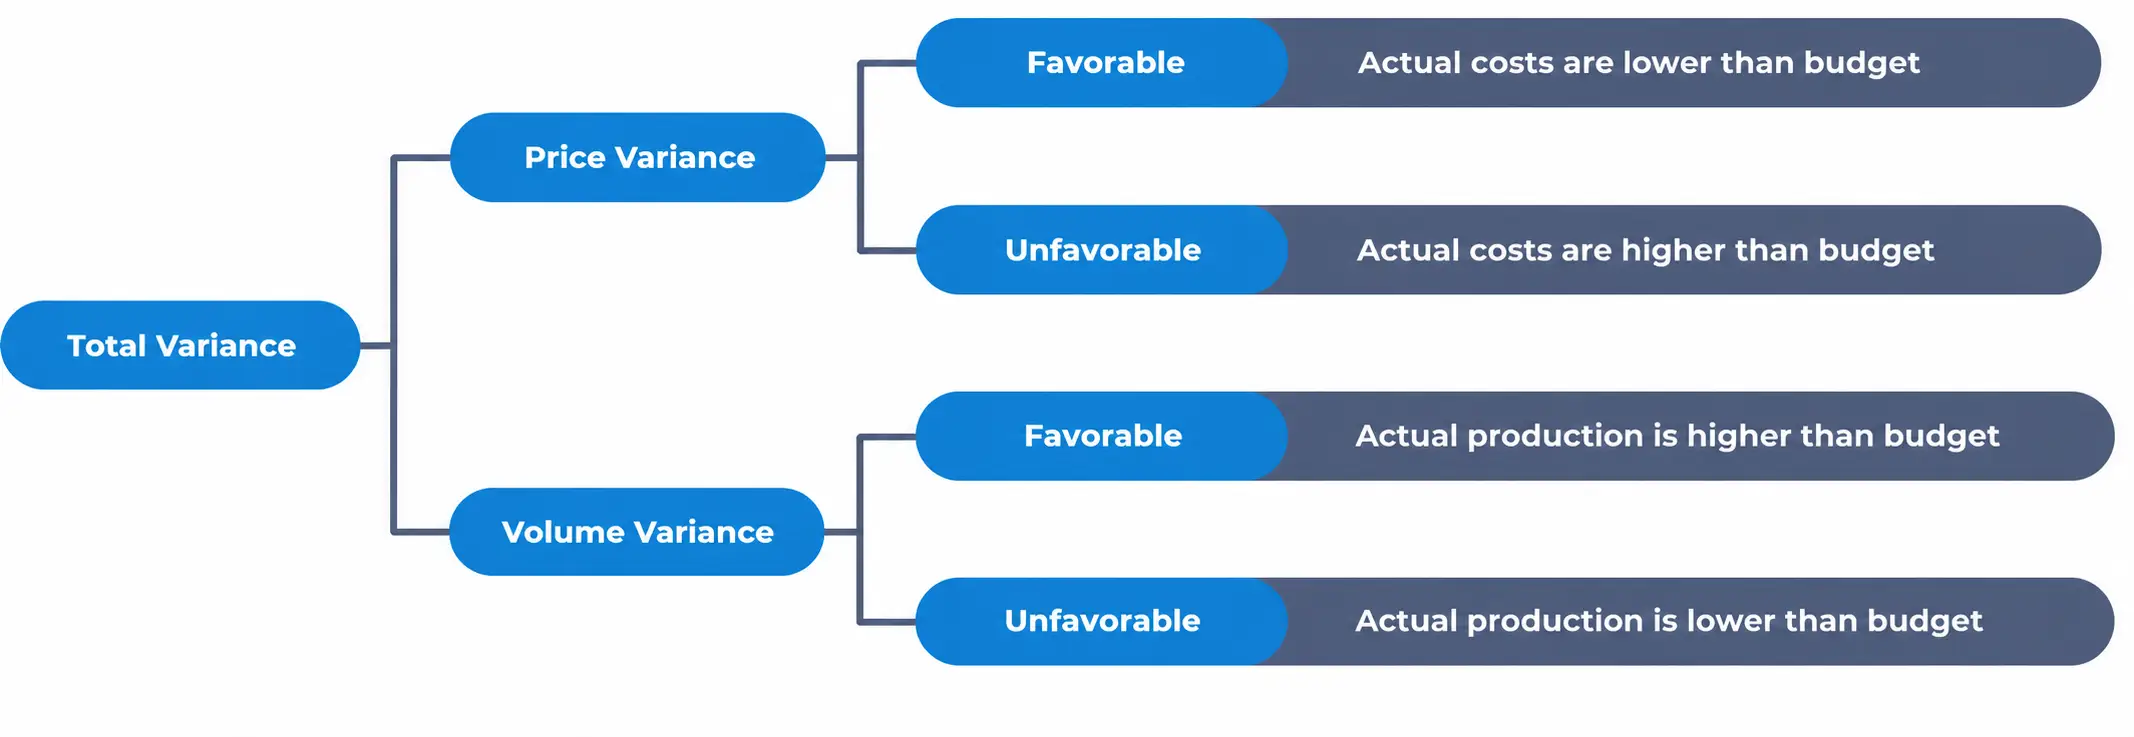
To refine decision-making, the total variance is further broken down into specific components, such as price variances and volume variances. This detailed breakdown allows organizations to identify the root causes of deviations, such as higher-than-expected input prices or lower production volumes.

Splitting total variance into price and volume variance, each shown as favorable or unfavorable.
Total Variance Breakdown
Achievable

Benefits and limitations of master budget comparisons

Comparing actual results to the master budget is the simplest form of variance analysis: it’s quick to prepare, it ties results directly back to the original plan, and it gives one overall read on whether the company hit its profit targets.

The main limitation is that the master budget is fixed at a single planned volume. When actual volume differs from plan, that volume difference bleeds into every cost variance, making it hard to tell how much of a variance reflects a manager’s performance versus simply selling or producing a different number of units. In the example above, the $7,500 favorable variable cost variance didn’t come from better cost control - it came from selling fewer units than planned, and taken at face value it could wrongly suggest the production manager cut costs.

Flexible budgeting, covered in a later chapter, fixes this by adjusting the budget to the volume actually achieved, so the remaining variances reflect price and efficiency rather than volume.

Common causes of variances

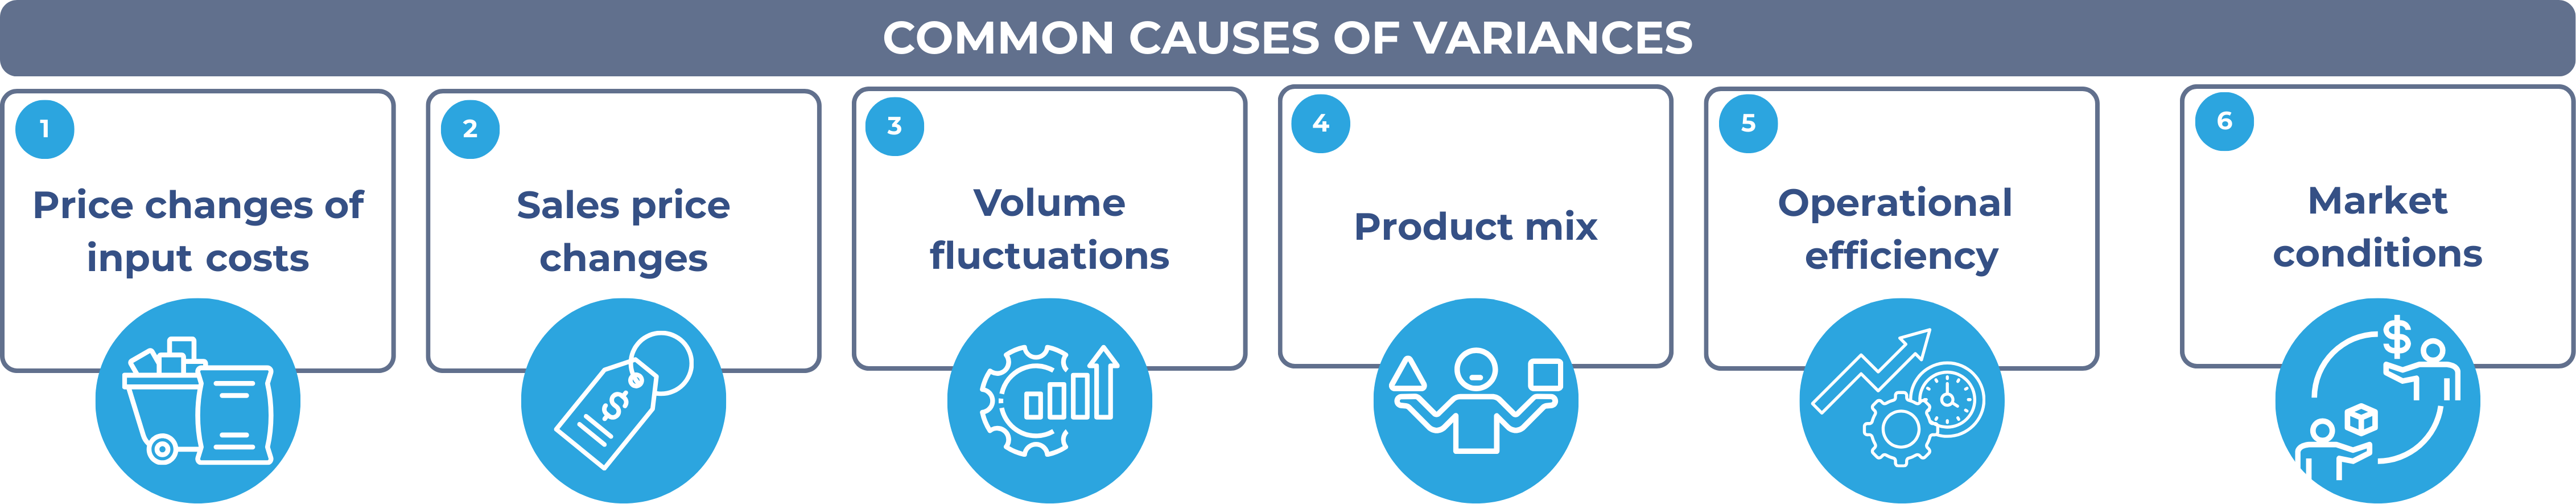
Variances arise from multiple factors, which can either positively or negatively affect performance. Understanding these drivers helps organizations interpret performance results and implement corrective actions. Below are common causes of variances, along with how they may result in favorable or unfavorable outcomes:

Six causes of variances: input price changes, sales price, volume fluctuations, product mix, operational efficiency, and market conditions.
Common causes of variances
Achievable

1. Price changes of input costs

Price changes related to input costs affect the cost of raw materials, labor, or overhead.

  • Favorable input price variances:
    These occur when actual input prices are lower than budgeted. Examples include negotiating supplier discounts, benefiting from market price declines, or using alternative materials that are cheaper yet still meet quality standards. Lower utility rates or energy costs can also drive favorable variances.
  • Unfavorable input price variances:
    These arise when input prices exceed expectations. For instance, inflationary pressures, supply chain disruptions, or shortages of raw materials can drive up costs. Wage increases due to labor market conditions or collective bargaining agreements may also cause unfavorable labor price variances.

2. Sales price

Sales price variances occur when the actual selling price of products or services differs from the budgeted price.

  • Favorable sales price variances:
    These occur when products or services are sold at prices higher than anticipated. This can happen due to strong brand positioning, successful premium pricing strategies, or market conditions allowing for higher price points without sacrificing demand.
  • Unfavorable sales price variances:
    Unfavorable variances occur when actual selling prices are lower than planned. Causes include competitive pressure forcing price reductions, promotional discounts, or shifts in consumer behavior favoring lower-priced alternatives.

3. Volume fluctuations

Volume variances result from differences between actual and budgeted production or sales volumes, and the two have distinct effects.

  • Favorable volume variances:
    Selling more units than budgeted raises total contribution margin, since more units are earning margin. Producing more units than budgeted spreads fixed costs over a larger base, lowering the fixed cost per unit.
  • Unfavorable volume variances:
    Selling fewer units than budgeted lowers total contribution margin. Producing fewer units than budgeted raises the fixed cost per unit, since fixed costs are spread over a smaller base.

4. Product mix

Product mix variances occur when the actual proportion of high-margin versus low-margin products sold deviates from budgeted expectations.

  • Favorable product mix variances:
    Selling a higher proportion of high-margin products than budgeted increases overall profitability. For example, successful marketing efforts for premium products can result in a favorable product mix variance.
  • Unfavorable product mix variances:
    A shift toward lower-margin products, even if total sales volume meets expectations, can reduce profitability. This may occur due to customer preferences shifting to discounted products or inventory shortages of high-margin items.

5. Operational efficiency

Operational efficiency variances reflect differences in productivity, resource utilization, or waste levels.

  • Favorable efficiency variances:
    Greater-than-expected efficiency in operations, such as reduced material waste or improved labor productivity, can lead to favorable variances. Process improvements, technological upgrades, or better workforce management are common drivers of these efficiencies.
  • Unfavorable efficiency variances:
    Operational inefficiencies, such as machine downtime, increased material waste, or unproductive labor hours, can result in unfavorable variances. Poor training, inadequate maintenance, or supply chain delays often contribute to these inefficiencies.

6. Market conditions

External factors like customer demand, competition, or economic trends drive market-conditions variances, mostly by moving price and volume. These factors can influence results but aren’t normally computed separately in a company’s variance analysis.

By identifying and analyzing these causes, organizations can better understand the drivers of favorable and unfavorable variances, enabling targeted strategies to address underperformance or capitalize on positive outcomes. For now it is important to know the sources of these variances. We will be discussing how to integrate them in computations in subsequent chapters.

Performance metrics by center type

  • Variance analysis compares actual results to budgets/standards to assess performance
  • Key metrics: revenue, manufacturing costs (materials, labor, overhead), nonmanufacturing costs (admin/selling), profitability (net income, contribution margin)
  • Metric emphasis depends on center type: cost centers → costs, revenue centers → revenue, profit/investment centers → profit measures

Variance basics

  • Favorable variance: actual results improve profitability (higher revenue, lower costs)
  • Unfavorable variance: actual results reduce profitability (lower revenue, higher costs)
  • Formula: Total variance=Actual results−Master budget results
  • Label F/U based on effect on operating income, not sign of subtraction
  • Caution: favorable variances aren’t always “good” (e.g., cost cutting from skipped maintenance)
  • Total variance can be broken into components (price variance, volume variance) to find root causes

Master budget comparison: benefits & limitations

  • Benefit: simple, quick, ties directly to original plan, gives overall profit picture
  • Limitation: master budget is fixed at planned volume, so volume differences distort cost variances
  • Can’t distinguish manager performance from volume effects (e.g., favorable cost variance may just reflect lower unit sales, not efficiency)
  • Flexible budgeting (later topic) fixes this by adjusting budget to actual volume, isolating price/efficiency effects

Common causes of variances

  • Input price changes: favorable (discounts, lower rates) vs. unfavorable (inflation, shortages, wage hikes)
  • Sales price: favorable (premium pricing, strong demand) vs. unfavorable (competitive discounting, lower prices)
  • Volume fluctuations: more units sold/produced than budget = favorable (higher margin, lower fixed cost/unit); fewer units = unfavorable
  • Product mix: higher proportion of high-margin products = favorable; shift to low-margin = unfavorable
  • Operational efficiency: less waste/better productivity = favorable; downtime/waste/poor training = unfavorable
  • Market conditions: external demand/competition/economic trends affect price & volume, not separately computed

Sign up for free to take 10 quiz questions on this topic

Previous
Next  | 3.1.2 Calculating and interpreting variances
All rights reserved ©2016 - 2026 Achievable, Inc.

Comparison of actual to planned results

Learning outcome statements

The learning outcome statements relevant for this section are:

  1. analyze performance against operational goals using measures based on revenue, manufacturing costs, nonmanufacturing costs, and profit depending on the type of center or unit being measured
  2. explain the reasons for variances within a performance monitoring system
  3. prepare a performance analysis by comparing actual results to the master budget, calculate favorable and unfavorable variances from the budget, and provide explanations for variances
  4. identify and describe the benefits and limitations of measuring performance by comparing actual results to the master budget

Performance analysis across key metrics

Now that the budgets are set, the next step is to measure the actual results against these budgets. This process is typically done by analyzing the differences between budgeted and actual results, referred to as variances.

Variance analysis provides a systematic approach to understanding where performance aligns with or deviates from expectations, helping organizations identify areas for improvement or celebration. Performance is assessed using key metrics tailored to the type of responsibility center or operational focus. These metrics typically include:

  1. Revenue
    Revenue analysis compares actual sales to budgeted sales, identifying variances caused by factors such as price changes, shifts in sales volume, or changes in product mix.
  2. Manufacturing costs
    Manufacturing costs include direct materials, direct labor, and manufacturing overhead. Variance analysis for these costs helps organizations pinpoint inefficiencies or unexpected changes in input costs or usage.
  3. Nonmanufacturing costs
    Nonmanufacturing costs, such as administrative and selling expenses, are critical to overall profitability. Monitoring these costs ensures they remain aligned with budgeted amounts.
  4. Profitability
    Profitability metrics, such as net income and contribution margin, provide an overarching perspective on performance. These metrics incorporate the combined effects of revenue and cost variances, offering a summary view of financial health.

Which measures matter most depends on the type of responsibility center: cost centers are evaluated mainly on manufacturing or nonmanufacturing costs, revenue centers on revenue, and profit or investment centers on profit measures such as contribution margin. Responsibility centers, covered in a later chapter, explains how each center type is evaluated in detail.

Understanding variances

Variance analysis is a fundamental tool in performance management, providing insights into how actual results compare to planned expectations. These “planned expectations” can be the budgets that we have already discussed and prepared in the previous sections or standards developed for production. Variances are categorized as either favorable or unfavorable, depending on their impact on organizational goals.

Definitions
Favorable variance
Occurs when actual results positively exceed expectations, improving profitability. For instance, in the context of revenues, a favorable variance might mean actual sales revenue exceeded the budgeted amount. With costs, a favorable variance occurs when actual costs are lower than budgeted, signaling efficient resource usage or cost savings.
Unfavorable variance
Occurs when actual results negatively deviate from expectations, reducing profitability. For revenues, this might mean lower-than-expected sales or average selling prices. For costs, an unfavorable variance occurs when actual expenses exceed budgeted amounts, possibly due to inefficiencies or unexpected price increases.

The first step in variance analysis is to calculate the total variance, which represents the overall difference between actual results and the master budget. This total variance provides a high-level picture of how well performance aligns with expectations and is expressed as:

Total variance=Actual results−Master budget results

Watch the sign: under Actual results−Master budget results, a positive number is favorable for revenue and profit but unfavorable for costs - higher actual revenue helps profitability, while higher actual costs hurt it. Always label a variance favorable (F) or unfavorable (U) by its effect on operating income, not by whether the subtraction comes out positive or negative. And remember: a favorable variance isn’t automatically good news - it can come from cutting corners, like skipping maintenance to save costs.

Example: Master budget vs. actual results

Achievable Co.'s master budget assumed 10,000 units sold at $20 per unit, variable costs of $12 per unit, and fixed costs of $50,000. Actual results were 9,000 units sold at $21 per unit, variable costs of $12.50 per unit, and fixed costs of $52,000.

Line item Master budget Actual Variance F/U
Revenue $200,000 $189,000 $11,000 U
Variable costs $120,000 $112,500 $7,500 F
Contribution margin $80,000 $76,500 $3,500 U
Fixed costs $50,000 $52,000 $2,000 U
Operating income $30,000 $24,500 $5,500 U

Answer: operating income came in $5,500 unfavorable overall. Notice that the variable cost variance looks favorable ($7,500 F) only because the company sold 1,000 fewer units than planned - the actual cost per unit was $12.50, higher than the $12.00 budgeted. A flexible budget (covered in a later chapter) removes this volume effect so the cost variance reflects price and efficiency only.

To refine decision-making, the total variance is further broken down into specific components, such as price variances and volume variances. This detailed breakdown allows organizations to identify the root causes of deviations, such as higher-than-expected input prices or lower production volumes.

Benefits and limitations of master budget comparisons

Comparing actual results to the master budget is the simplest form of variance analysis: it’s quick to prepare, it ties results directly back to the original plan, and it gives one overall read on whether the company hit its profit targets.

The main limitation is that the master budget is fixed at a single planned volume. When actual volume differs from plan, that volume difference bleeds into every cost variance, making it hard to tell how much of a variance reflects a manager’s performance versus simply selling or producing a different number of units. In the example above, the $7,500 favorable variable cost variance didn’t come from better cost control - it came from selling fewer units than planned, and taken at face value it could wrongly suggest the production manager cut costs.

Flexible budgeting, covered in a later chapter, fixes this by adjusting the budget to the volume actually achieved, so the remaining variances reflect price and efficiency rather than volume.

Common causes of variances

Variances arise from multiple factors, which can either positively or negatively affect performance. Understanding these drivers helps organizations interpret performance results and implement corrective actions. Below are common causes of variances, along with how they may result in favorable or unfavorable outcomes:

1. Price changes of input costs

Price changes related to input costs affect the cost of raw materials, labor, or overhead.

  • Favorable input price variances:
    These occur when actual input prices are lower than budgeted. Examples include negotiating supplier discounts, benefiting from market price declines, or using alternative materials that are cheaper yet still meet quality standards. Lower utility rates or energy costs can also drive favorable variances.
  • Unfavorable input price variances:
    These arise when input prices exceed expectations. For instance, inflationary pressures, supply chain disruptions, or shortages of raw materials can drive up costs. Wage increases due to labor market conditions or collective bargaining agreements may also cause unfavorable labor price variances.

2. Sales price

Sales price variances occur when the actual selling price of products or services differs from the budgeted price.

  • Favorable sales price variances:
    These occur when products or services are sold at prices higher than anticipated. This can happen due to strong brand positioning, successful premium pricing strategies, or market conditions allowing for higher price points without sacrificing demand.
  • Unfavorable sales price variances:
    Unfavorable variances occur when actual selling prices are lower than planned. Causes include competitive pressure forcing price reductions, promotional discounts, or shifts in consumer behavior favoring lower-priced alternatives.

3. Volume fluctuations

Volume variances result from differences between actual and budgeted production or sales volumes, and the two have distinct effects.

  • Favorable volume variances:
    Selling more units than budgeted raises total contribution margin, since more units are earning margin. Producing more units than budgeted spreads fixed costs over a larger base, lowering the fixed cost per unit.
  • Unfavorable volume variances:
    Selling fewer units than budgeted lowers total contribution margin. Producing fewer units than budgeted raises the fixed cost per unit, since fixed costs are spread over a smaller base.

4. Product mix

Product mix variances occur when the actual proportion of high-margin versus low-margin products sold deviates from budgeted expectations.

  • Favorable product mix variances:
    Selling a higher proportion of high-margin products than budgeted increases overall profitability. For example, successful marketing efforts for premium products can result in a favorable product mix variance.
  • Unfavorable product mix variances:
    A shift toward lower-margin products, even if total sales volume meets expectations, can reduce profitability. This may occur due to customer preferences shifting to discounted products or inventory shortages of high-margin items.

5. Operational efficiency

Operational efficiency variances reflect differences in productivity, resource utilization, or waste levels.

  • Favorable efficiency variances:
    Greater-than-expected efficiency in operations, such as reduced material waste or improved labor productivity, can lead to favorable variances. Process improvements, technological upgrades, or better workforce management are common drivers of these efficiencies.
  • Unfavorable efficiency variances:
    Operational inefficiencies, such as machine downtime, increased material waste, or unproductive labor hours, can result in unfavorable variances. Poor training, inadequate maintenance, or supply chain delays often contribute to these inefficiencies.

6. Market conditions

External factors like customer demand, competition, or economic trends drive market-conditions variances, mostly by moving price and volume. These factors can influence results but aren’t normally computed separately in a company’s variance analysis.

By identifying and analyzing these causes, organizations can better understand the drivers of favorable and unfavorable variances, enabling targeted strategies to address underperformance or capitalize on positive outcomes. For now it is important to know the sources of these variances. We will be discussing how to integrate them in computations in subsequent chapters.

Key points

Performance metrics by center type

  • Variance analysis compares actual results to budgets/standards to assess performance
  • Key metrics: revenue, manufacturing costs (materials, labor, overhead), nonmanufacturing costs (admin/selling), profitability (net income, contribution margin)
  • Metric emphasis depends on center type: cost centers → costs, revenue centers → revenue, profit/investment centers → profit measures

Variance basics

  • Favorable variance: actual results improve profitability (higher revenue, lower costs)
  • Unfavorable variance: actual results reduce profitability (lower revenue, higher costs)
  • Formula: Total variance=Actual results−Master budget results
  • Label F/U based on effect on operating income, not sign of subtraction
  • Caution: favorable variances aren’t always “good” (e.g., cost cutting from skipped maintenance)
  • Total variance can be broken into components (price variance, volume variance) to find root causes

Master budget comparison: benefits & limitations

  • Benefit: simple, quick, ties directly to original plan, gives overall profit picture
  • Limitation: master budget is fixed at planned volume, so volume differences distort cost variances
  • Can’t distinguish manager performance from volume effects (e.g., favorable cost variance may just reflect lower unit sales, not efficiency)
  • Flexible budgeting (later topic) fixes this by adjusting budget to actual volume, isolating price/efficiency effects

Common causes of variances

  • Input price changes: favorable (discounts, lower rates) vs. unfavorable (inflation, shortages, wage hikes)
  • Sales price: favorable (premium pricing, strong demand) vs. unfavorable (competitive discounting, lower prices)
  • Volume fluctuations: more units sold/produced than budget = favorable (higher margin, lower fixed cost/unit); fewer units = unfavorable
  • Product mix: higher proportion of high-margin products = favorable; shift to low-margin = unfavorable
  • Operational efficiency: less waste/better productivity = favorable; downtime/waste/poor training = unfavorable
  • Market conditions: external demand/competition/economic trends affect price & volume, not separately computed

More from Cost and variance measures

  • Calculating and interpreting variances