


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
CMA Part 1
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. External financial reporting decisions
2. Planning, budgeting, and forecasting
2.1 Strategic planning
2.1.1 Analysis of external and internal factors affecting strategy
2.1.2 Long-term mission and goals
2.1.3 Alignment of tactics with long-term strategic goals
2.1.4 Strategic planning models and analytical techniques
2.1.5 Characteristics of successful strategic planning process
2.2 Budgeting concepts
2.3 Forecasting techniques
2.4 Budgeting methodologies
2.5 Annual profit plan and supporting schedules
2.6 Top-level planning and analysis
3. Performance management
4. Cost management
5. Internal control
6. Technology and analytics
Wrapping up
Achievable logoAchievable logo
2.1.3 Alignment of tactics with long-term strategic goals
Achievable CMA Part 1
2. Planning, budgeting, and forecasting
2.1. Strategic planning
Our CMA Part 1 course is currently in development and is a work-in-progress.

Alignment of tactics with long-term strategic goals

6 min read
Font
Discuss
Share
Feedback

Learning outcome statements

The learning outcome statements relevant for this section are:

  1. explain why short-term objectives, tactics for achieving these objectives, and operational planning (master budget) must be congruent with the strategic plan and contribute to the achievement of long-term strategic goals

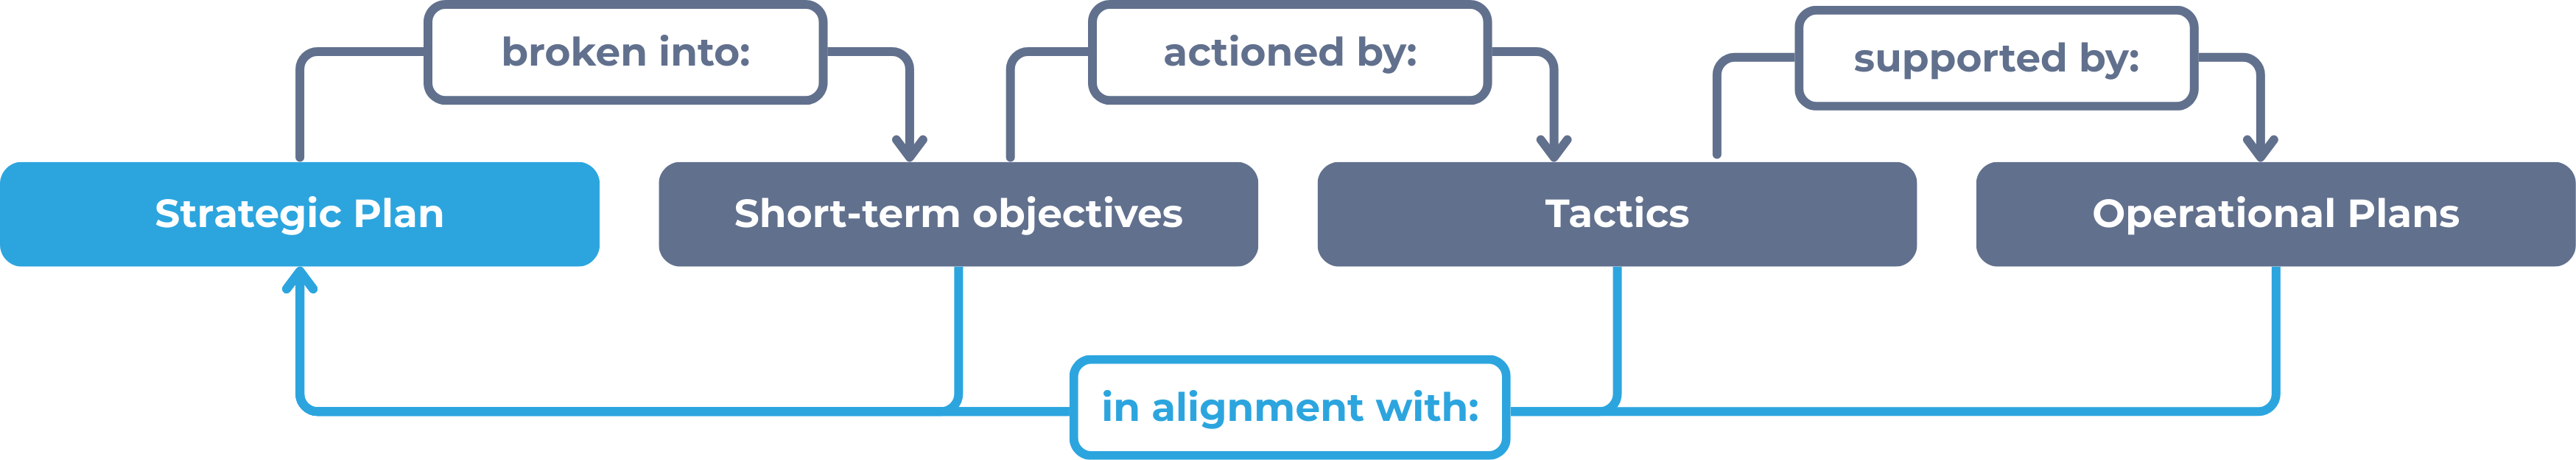
For an organization to successfully achieve its long-term strategic goals, short-term objectives, tactics, and operational planning must be closely aligned with the broader strategy. This ensures that every action, from the smallest task to high-level planning, contributes to the same overarching mission. The hierarchy below shows how each level cascades from the organization’s mission down through the strategic plan, short-term objectives, tactics, and day-to-day operational planning.

Hierarchy of plans
Hierarchy of plans
Achievable

Short-term objectives

Definitions
Short-term objectives
These are specific, measurable goals set for a short timeframe (usually within a year) that act as milestones toward achieving long-term strategic goals.

These short-term objectives must be aligned with the strategic plan and they should be specific and measurable with clear targets set to track progress.

Tactics

Definitions
Tactics
These are the concrete actions taken to meet short-term objectives. These actions are more focused and immediate than broader strategies but must support them.

Tactics need to directly address short-term goals with each action contributing to reach specific objectives, and be resource-efficient.

Operational planning and the master budget

Operational planning focuses on the day-to-day activities that need to be executed to achieve short-term objectives. This is where the master budget comes into play.

Definitions
Master budget
This is a comprehensive financial plan that consolidates all of the organization’s individual budgets (sales, production, expenses, etc.) into a unified plan for the upcoming period, typically one fiscal year.

The master budget serves several important purposes in strategic alignment:

  • Resource allocation: the master budget ensures that funds and other resources are directed toward priority initiatives.
  • Monitoring performance: by comparing actual results with the budget, managers can identify variances and make adjustments.

Example: Tracing one strategic goal through the hierarchy

Suppose a company’s strategic plan sets a five-year goal of becoming a top-3 brand in the Midwest region.

  • Short-term objective: raise brand awareness in the Midwest to 30% within the first year.
  • Tactic: launch a targeted digital marketing campaign and sign new distributor agreements to expand retail presence.
  • Master budget: the sales budget plans for the expected increase in regional volume, the marketing budget funds the digital campaign, and the production and cash budgets ensure the company can supply and finance the expansion.
  • Monitoring: KPIs such as brand awareness and regional sales volume, together with budget variance analysis, show whether the company is on track.

Notice that the strategic plan spans several years, while the master budget translates the first year of that plan into an operational, financial plan.

Importance of congruence with the strategic plan

For tactical actions and operational planning to effectively support long-term goals, there must be congruence between all levels of planning. Congruence means that every part of the organization, from top-level strategy to individual tasks, is moving in the same direction toward the achievement of the overall strategic goals. This congruence is essential to achieve consistency in decision making, efficient utilization of resources and synergy, among other benefits.

Without this congruence, problems quickly surface. Resources get spent on initiatives that don’t advance the strategy, departments can fall into short-termism - cutting R&D, training, or marketing to hit this year’s budget or profit target at the expense of long-term goals - and individual departments can end up optimizing their own targets while undermining the organization as a whole (suboptimization). Strategy should drive the budget, not the other way around.

Progress is measured through a combination of:

  1. financial performance indicators (e.g., revenue growth, cost control, profit margins); and
  2. non-financial indicators (e.g., customer satisfaction, market share growth).

Monitoring alignment: to ensure that short-term tactics are contributing to the long-term goals, organizations track:

  • Key performance indicators (KPIs): these metrics are chosen based on their relevance to both short-term and long-term objectives. For example, sales volume might be a short-term KPI, while market share could serve as a long-term KPI.
  • Budget variance analysis: the monitoring role described above - comparing actual results against a budget flexed to actual activity levels, so volume effects aren’t mistaken for efficiency - triggers timely adjustments to tactics or operations.

Milestones and benchmarks set at the start of the planning process also help determine if the organization is on track to meet its long-term strategic goals. When misalignment occurs, managers can intervene to correct the course and ensure that short-term actions are realigned with the strategy.

Types of control systems

KPIs, variance analysis, and milestones are controls: they keep tactics and operations congruent with the strategic plan. Control systems are classified by when they act relative to the activity they control:

  • Preliminary (feedforward) controls act before an activity begins. They prevent problems by checking inputs and plans in advance - for example, inspecting raw materials on receipt or approving a capital project before funds are committed.
  • Screening (concurrent) controls act during the activity. At checkpoints, work must meet a standard before it can continue, so problems are corrected while the activity is under way - for example, inspecting output at each stage of production. They are also called yes/no controls.
  • Post-action (feedback) controls act after the activity is complete. They compare results with the plan so the next cycle can be corrected - for example, budget variance analysis and performance reviews.

Most organizations combine all three. Post-action controls are the most widely used, but they act only after a problem has occurred; preliminary and screening controls catch it earlier.

Control systems that monitor these metrics are covered in later chapters, including responsibility centers and internal control objectives.

Hierarchy of planning

  • Mission → strategic plan → short-term objectives → tactics → operational planning (master budget)
  • Each level must cascade from and support the one above to achieve long-term strategic goals

Short-term objectives and tactics

  • Short-term objectives: specific, measurable milestones (usually within a year) toward strategic goals
  • Tactics: concrete, resource-efficient actions taken to meet short-term objectives
  • Both must directly support and align with the broader strategic plan

Operational planning and the master budget

  • Operational planning = day-to-day activities executed via the master budget
  • Master budget: consolidates all individual budgets (sales, production, expenses, etc.) into one unified financial plan, typically for one fiscal year
  • Key roles: resource allocation (funding priority initiatives) and performance monitoring (comparing actual vs. budget to spot variances)
  • Example chain: 5-yr strategic goal → 1-yr objective (brand awareness) → tactics (marketing campaign, distributor deals) → budgets (sales, marketing, production, cash) → KPI/variance monitoring

Congruence across planning levels

  • Congruence = all levels moving in the same strategic direction; ensures consistent decisions, efficient resource use, synergy
  • Strategy should drive the budget, not vice versa
  • Lack of congruence causes: wasted resources, short-termism (cutting R&D/training/marketing to hit annual targets), and suboptimization (departments optimizing own goals at the org’s expense)

Monitoring alignment

  • Progress tracked via financial indicators (revenue growth, cost control, margins) and non-financial indicators (customer satisfaction, market share)
  • KPIs: chosen for relevance to both short- and long-term goals (e.g., sales volume vs. market share)
  • Budget variance analysis: compare actual results to a flexed budget to isolate efficiency from volume effects, triggering corrective action
  • Milestones/benchmarks set early help detect misalignment so managers can realign tactics with strategy

Types of control systems (by timing)

  • Preliminary (feedforward): before the activity; prevents problems by checking inputs (e.g., inspecting materials, approving capital projects)
  • Screening (concurrent): during the activity; work must pass checkpoints to continue (e.g., in-process inspection)
  • Post-action (feedback): after the activity; compares results with the plan to correct the next cycle (e.g., variance analysis)

Sign up for free to take 12 quiz questions on this topic

Previous
Next  | 2.1.4 Strategic planning models and analytical techniques
All rights reserved ©2016 - 2026 Achievable, Inc.

Alignment of tactics with long-term strategic goals

Learning outcome statements

The learning outcome statements relevant for this section are:

  1. explain why short-term objectives, tactics for achieving these objectives, and operational planning (master budget) must be congruent with the strategic plan and contribute to the achievement of long-term strategic goals

For an organization to successfully achieve its long-term strategic goals, short-term objectives, tactics, and operational planning must be closely aligned with the broader strategy. This ensures that every action, from the smallest task to high-level planning, contributes to the same overarching mission. The hierarchy below shows how each level cascades from the organization’s mission down through the strategic plan, short-term objectives, tactics, and day-to-day operational planning.

Short-term objectives

Definitions
Short-term objectives
These are specific, measurable goals set for a short timeframe (usually within a year) that act as milestones toward achieving long-term strategic goals.

These short-term objectives must be aligned with the strategic plan and they should be specific and measurable with clear targets set to track progress.

Tactics

Definitions
Tactics
These are the concrete actions taken to meet short-term objectives. These actions are more focused and immediate than broader strategies but must support them.

Tactics need to directly address short-term goals with each action contributing to reach specific objectives, and be resource-efficient.

Operational planning and the master budget

Operational planning focuses on the day-to-day activities that need to be executed to achieve short-term objectives. This is where the master budget comes into play.

Definitions
Master budget
This is a comprehensive financial plan that consolidates all of the organization’s individual budgets (sales, production, expenses, etc.) into a unified plan for the upcoming period, typically one fiscal year.

The master budget serves several important purposes in strategic alignment:

  • Resource allocation: the master budget ensures that funds and other resources are directed toward priority initiatives.
  • Monitoring performance: by comparing actual results with the budget, managers can identify variances and make adjustments.

Example: Tracing one strategic goal through the hierarchy

Suppose a company’s strategic plan sets a five-year goal of becoming a top-3 brand in the Midwest region.

  • Short-term objective: raise brand awareness in the Midwest to 30% within the first year.
  • Tactic: launch a targeted digital marketing campaign and sign new distributor agreements to expand retail presence.
  • Master budget: the sales budget plans for the expected increase in regional volume, the marketing budget funds the digital campaign, and the production and cash budgets ensure the company can supply and finance the expansion.
  • Monitoring: KPIs such as brand awareness and regional sales volume, together with budget variance analysis, show whether the company is on track.

Notice that the strategic plan spans several years, while the master budget translates the first year of that plan into an operational, financial plan.

Importance of congruence with the strategic plan

For tactical actions and operational planning to effectively support long-term goals, there must be congruence between all levels of planning. Congruence means that every part of the organization, from top-level strategy to individual tasks, is moving in the same direction toward the achievement of the overall strategic goals. This congruence is essential to achieve consistency in decision making, efficient utilization of resources and synergy, among other benefits.

Without this congruence, problems quickly surface. Resources get spent on initiatives that don’t advance the strategy, departments can fall into short-termism - cutting R&D, training, or marketing to hit this year’s budget or profit target at the expense of long-term goals - and individual departments can end up optimizing their own targets while undermining the organization as a whole (suboptimization). Strategy should drive the budget, not the other way around.

Progress is measured through a combination of:

  1. financial performance indicators (e.g., revenue growth, cost control, profit margins); and
  2. non-financial indicators (e.g., customer satisfaction, market share growth).

Monitoring alignment: to ensure that short-term tactics are contributing to the long-term goals, organizations track:

  • Key performance indicators (KPIs): these metrics are chosen based on their relevance to both short-term and long-term objectives. For example, sales volume might be a short-term KPI, while market share could serve as a long-term KPI.
  • Budget variance analysis: the monitoring role described above - comparing actual results against a budget flexed to actual activity levels, so volume effects aren’t mistaken for efficiency - triggers timely adjustments to tactics or operations.

Milestones and benchmarks set at the start of the planning process also help determine if the organization is on track to meet its long-term strategic goals. When misalignment occurs, managers can intervene to correct the course and ensure that short-term actions are realigned with the strategy.

Types of control systems

KPIs, variance analysis, and milestones are controls: they keep tactics and operations congruent with the strategic plan. Control systems are classified by when they act relative to the activity they control:

  • Preliminary (feedforward) controls act before an activity begins. They prevent problems by checking inputs and plans in advance - for example, inspecting raw materials on receipt or approving a capital project before funds are committed.
  • Screening (concurrent) controls act during the activity. At checkpoints, work must meet a standard before it can continue, so problems are corrected while the activity is under way - for example, inspecting output at each stage of production. They are also called yes/no controls.
  • Post-action (feedback) controls act after the activity is complete. They compare results with the plan so the next cycle can be corrected - for example, budget variance analysis and performance reviews.

Most organizations combine all three. Post-action controls are the most widely used, but they act only after a problem has occurred; preliminary and screening controls catch it earlier.

Control systems that monitor these metrics are covered in later chapters, including responsibility centers and internal control objectives.

Key points

Hierarchy of planning

  • Mission → strategic plan → short-term objectives → tactics → operational planning (master budget)
  • Each level must cascade from and support the one above to achieve long-term strategic goals

Short-term objectives and tactics

  • Short-term objectives: specific, measurable milestones (usually within a year) toward strategic goals
  • Tactics: concrete, resource-efficient actions taken to meet short-term objectives
  • Both must directly support and align with the broader strategic plan

Operational planning and the master budget

  • Operational planning = day-to-day activities executed via the master budget
  • Master budget: consolidates all individual budgets (sales, production, expenses, etc.) into one unified financial plan, typically for one fiscal year
  • Key roles: resource allocation (funding priority initiatives) and performance monitoring (comparing actual vs. budget to spot variances)
  • Example chain: 5-yr strategic goal → 1-yr objective (brand awareness) → tactics (marketing campaign, distributor deals) → budgets (sales, marketing, production, cash) → KPI/variance monitoring

Congruence across planning levels

  • Congruence = all levels moving in the same strategic direction; ensures consistent decisions, efficient resource use, synergy
  • Strategy should drive the budget, not vice versa
  • Lack of congruence causes: wasted resources, short-termism (cutting R&D/training/marketing to hit annual targets), and suboptimization (departments optimizing own goals at the org’s expense)

Monitoring alignment

  • Progress tracked via financial indicators (revenue growth, cost control, margins) and non-financial indicators (customer satisfaction, market share)
  • KPIs: chosen for relevance to both short- and long-term goals (e.g., sales volume vs. market share)
  • Budget variance analysis: compare actual results to a flexed budget to isolate efficiency from volume effects, triggering corrective action
  • Milestones/benchmarks set early help detect misalignment so managers can realign tactics with strategy

Types of control systems (by timing)

  • Preliminary (feedforward): before the activity; prevents problems by checking inputs (e.g., inspecting materials, approving capital projects)
  • Screening (concurrent): during the activity; work must pass checkpoints to continue (e.g., in-process inspection)
  • Post-action (feedback): after the activity; compares results with the plan to correct the next cycle (e.g., variance analysis)

More from Strategic planning

  • Analysis of external and internal factors affecting strategy
  • Long-term mission and goals
  • Strategic planning models and analytical techniques
  • Characteristics of successful strategic planning process