


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
AP Macroeconomics
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
1. Core economic concepts
2. Measurement of economic performance
3. Modeling of income and prices
4. Financial sector
5. Long-run consequences of stabilization policy
5.1 The Phillips curve
5.2 Fiscal policy in the long run
5.3 Monetary policy in the long run
5.4 Stagflation
6. Open economy
Achievable logoAchievable logo
5.4 Stagflation
Achievable AP Macroeconomics
5. Long-run consequences of stabilization policy
Our AP Macroeconomics course is currently in development and is a work-in-progress.

Stagflation

9 min read
Font
Discuss
Share
Feedback

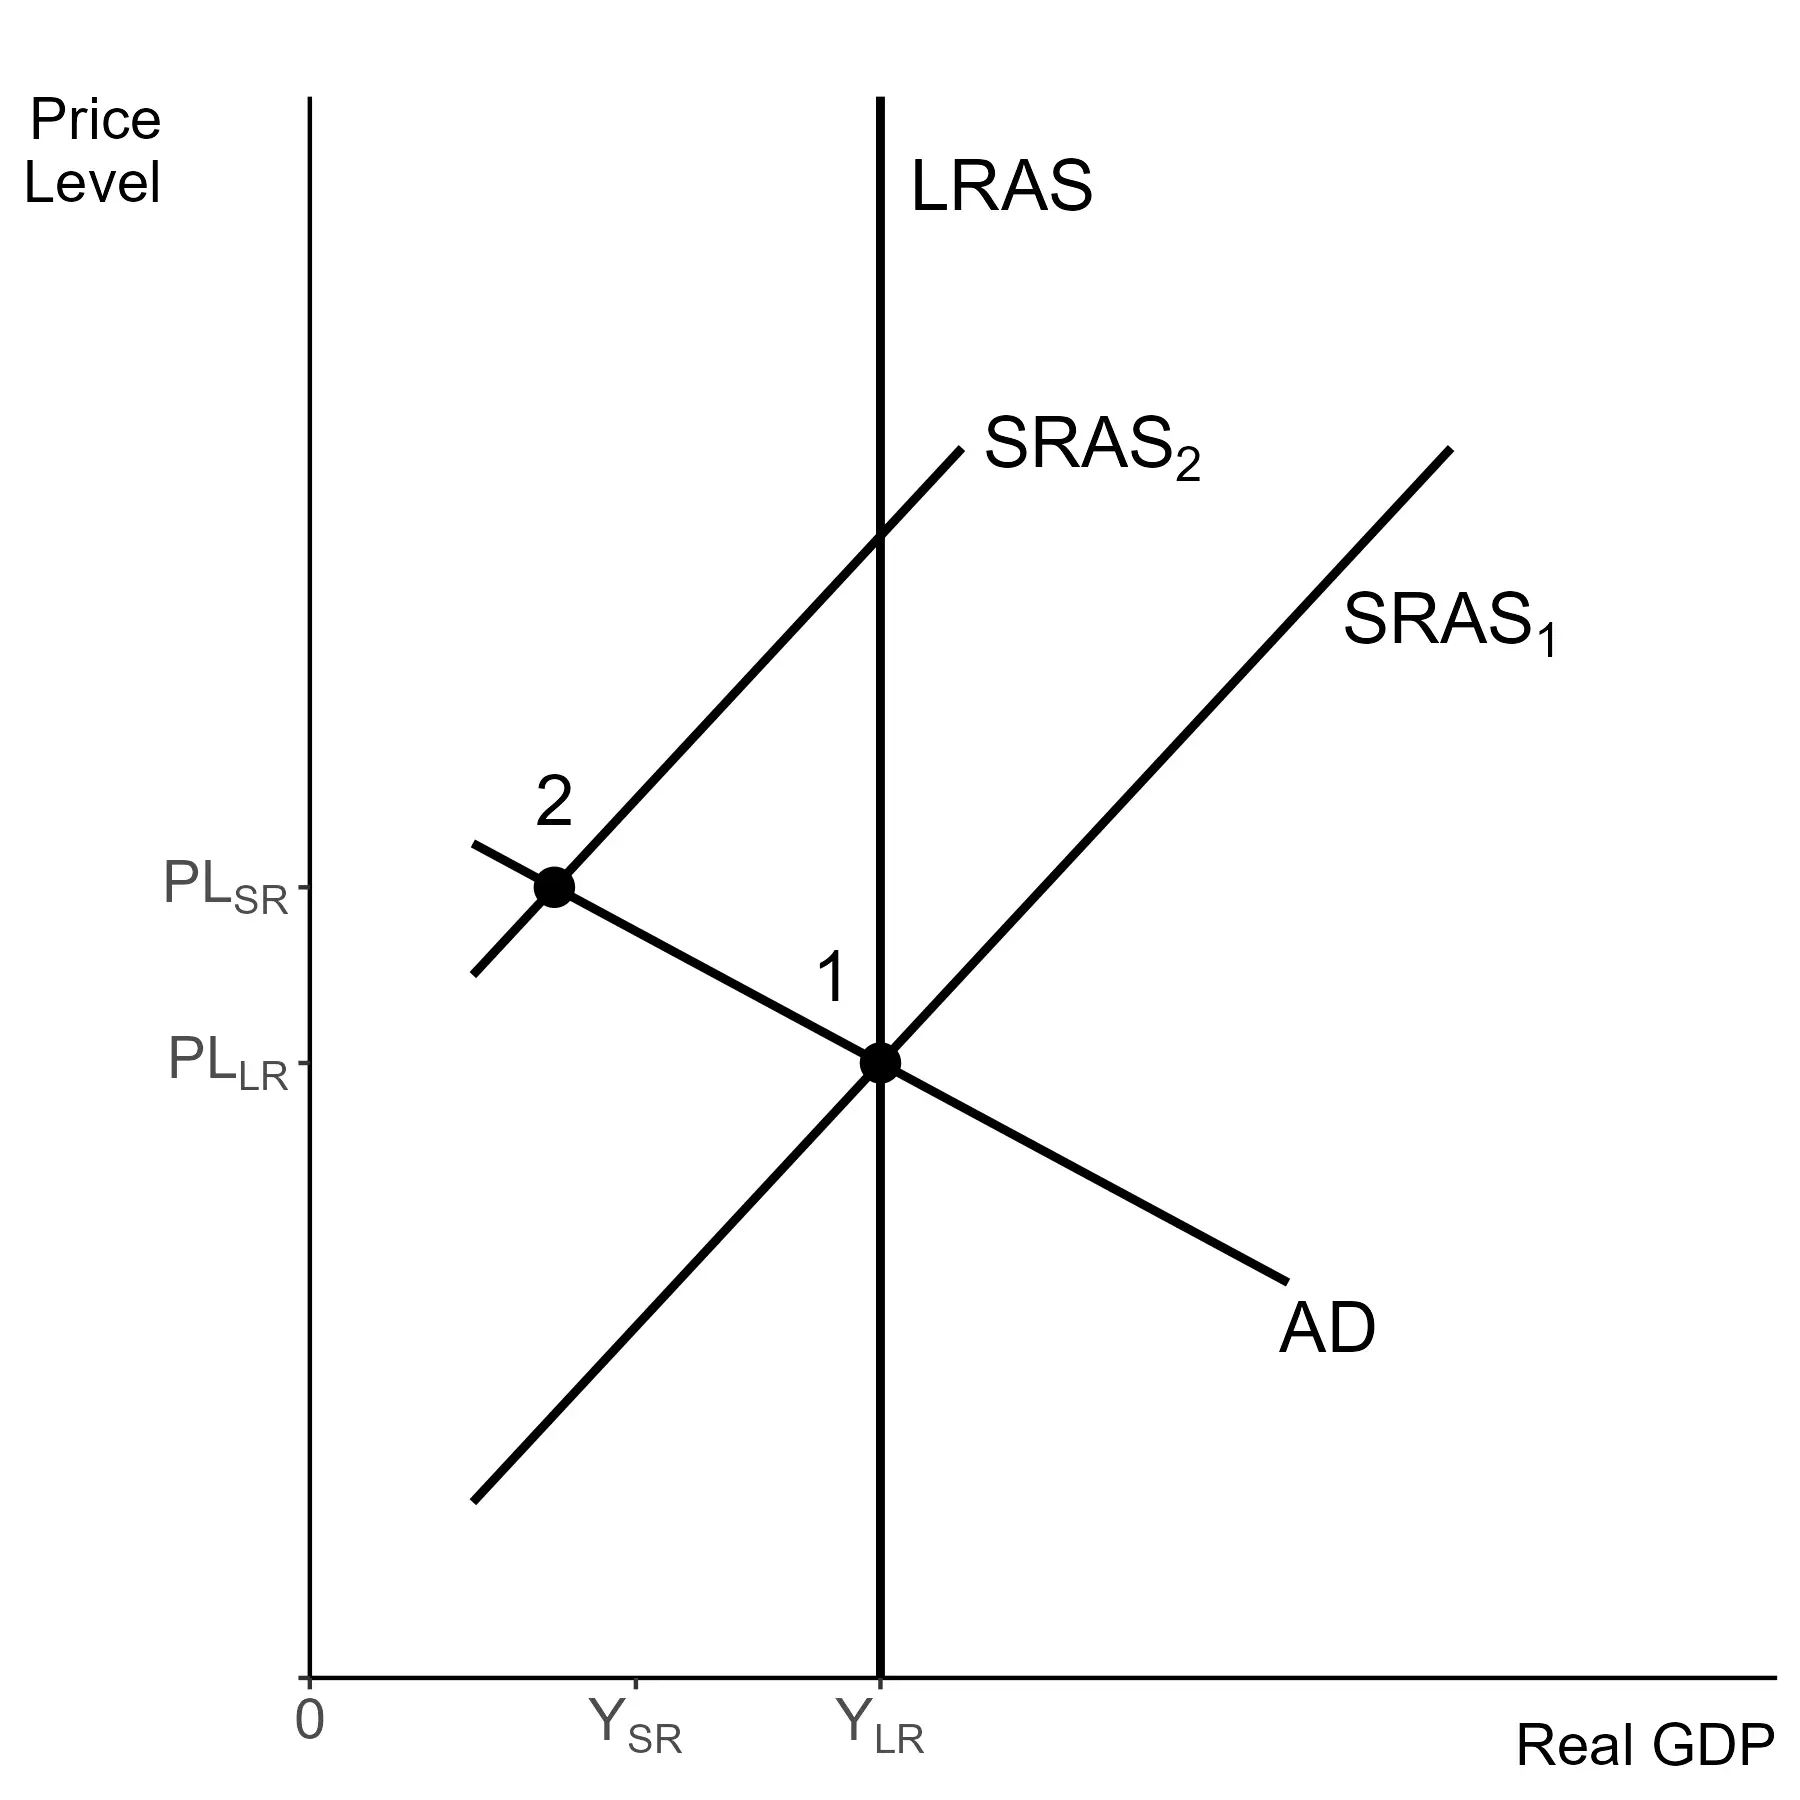
As a final look at the long run impacts, we are going to review an extended example looking at stagflation. Recall that this situation is most likely caused by a negative supply shock, a significant shift of SRAS to the left. Not only does it cause a recession, lowering output and increasing unemployment but it also increases the price level.

If no policy action is taken, the transition to the long run is for prices to fall. The supply shock dissipates and GDP and unemployment return to where they were before.

A negative supply shock shifting $SRAS$ to the left, with $SRAS$ shifting right as the long run self-adjustment.
Stagflation in the short run and long run
Achievable

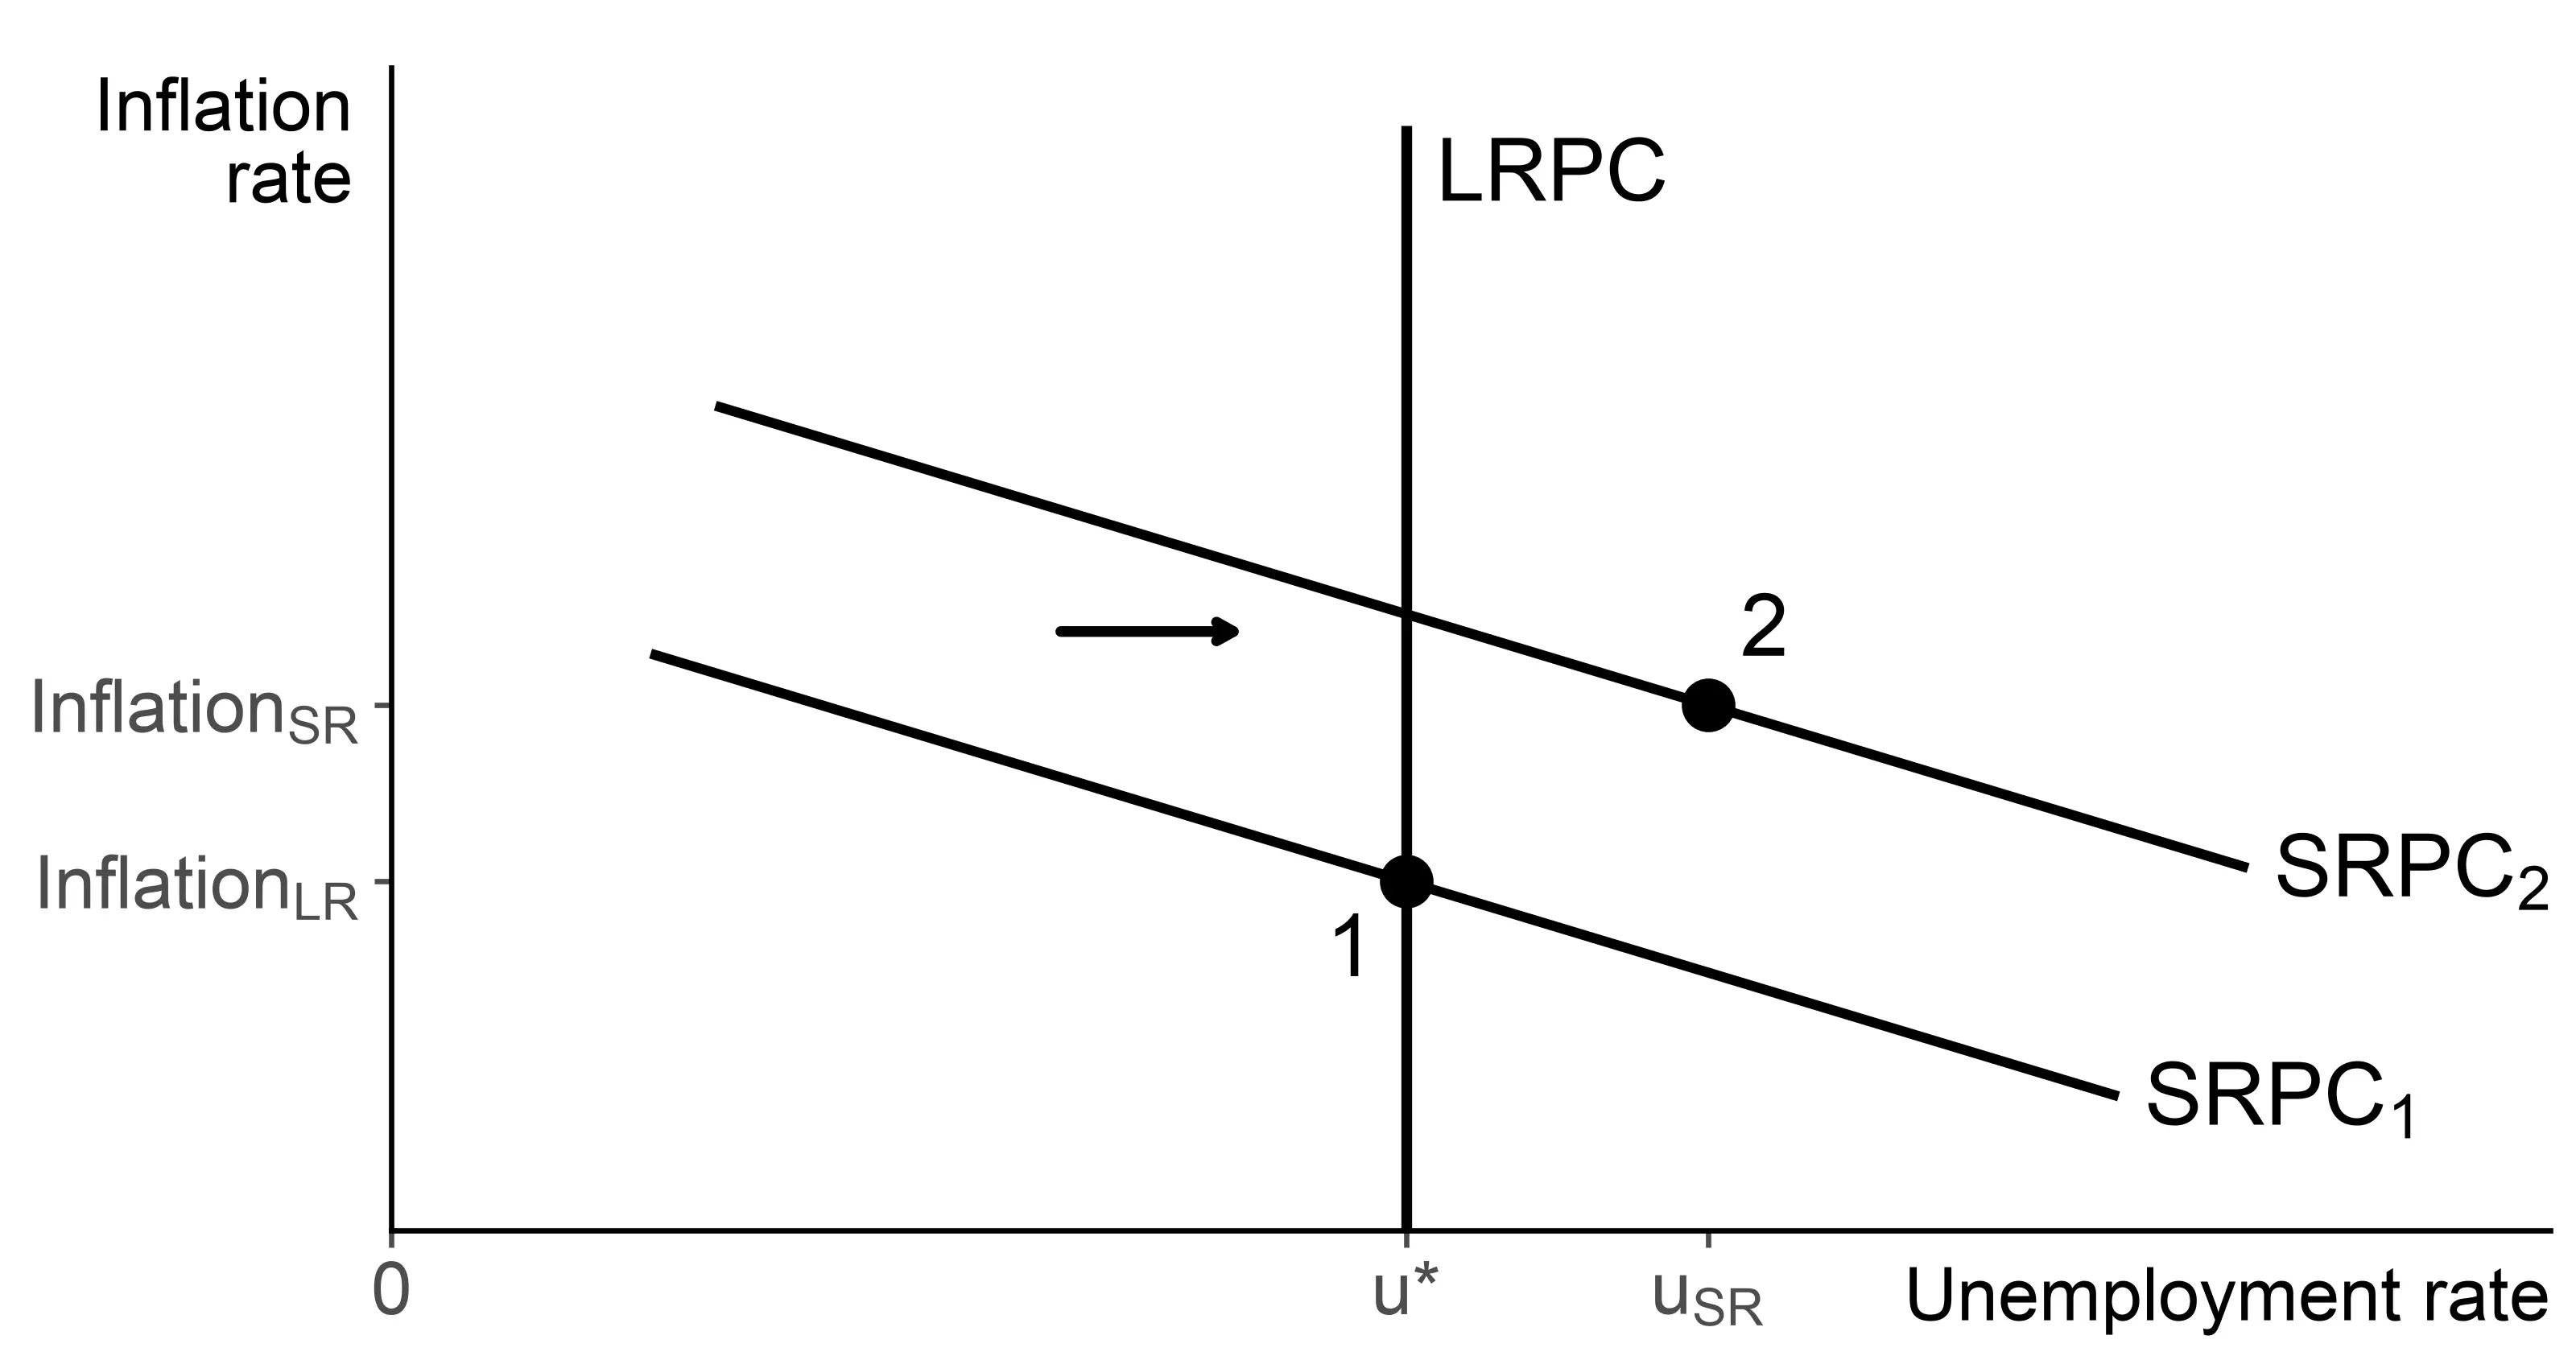
If long run inflation expectations do not change, there is a similar outcome looking at Phillips curves. The short run Phillips curve shifts right, increasing inflation and increasing unemployment. The trade-off between inflation and unemployment also gets worse. For every level of unemployment, inflation is higher.

As the supply shock dissipates, the SRPC shifts back to its original position, returning unemployment and inflation to their starting levels.

A negative supply shock shifting the $SRPC$ to the right, raising both inflation and unemployment
Stagflation on the Phillips curve
Achievable

As with any recession, policymakers may wish to shorten the recession rather than allow the economy to self-adjust. However, each policy option has significant trade-offs. To close a recessionary gap, our basic policy recommendation is expansionary policy.

Fiscal Policy Response

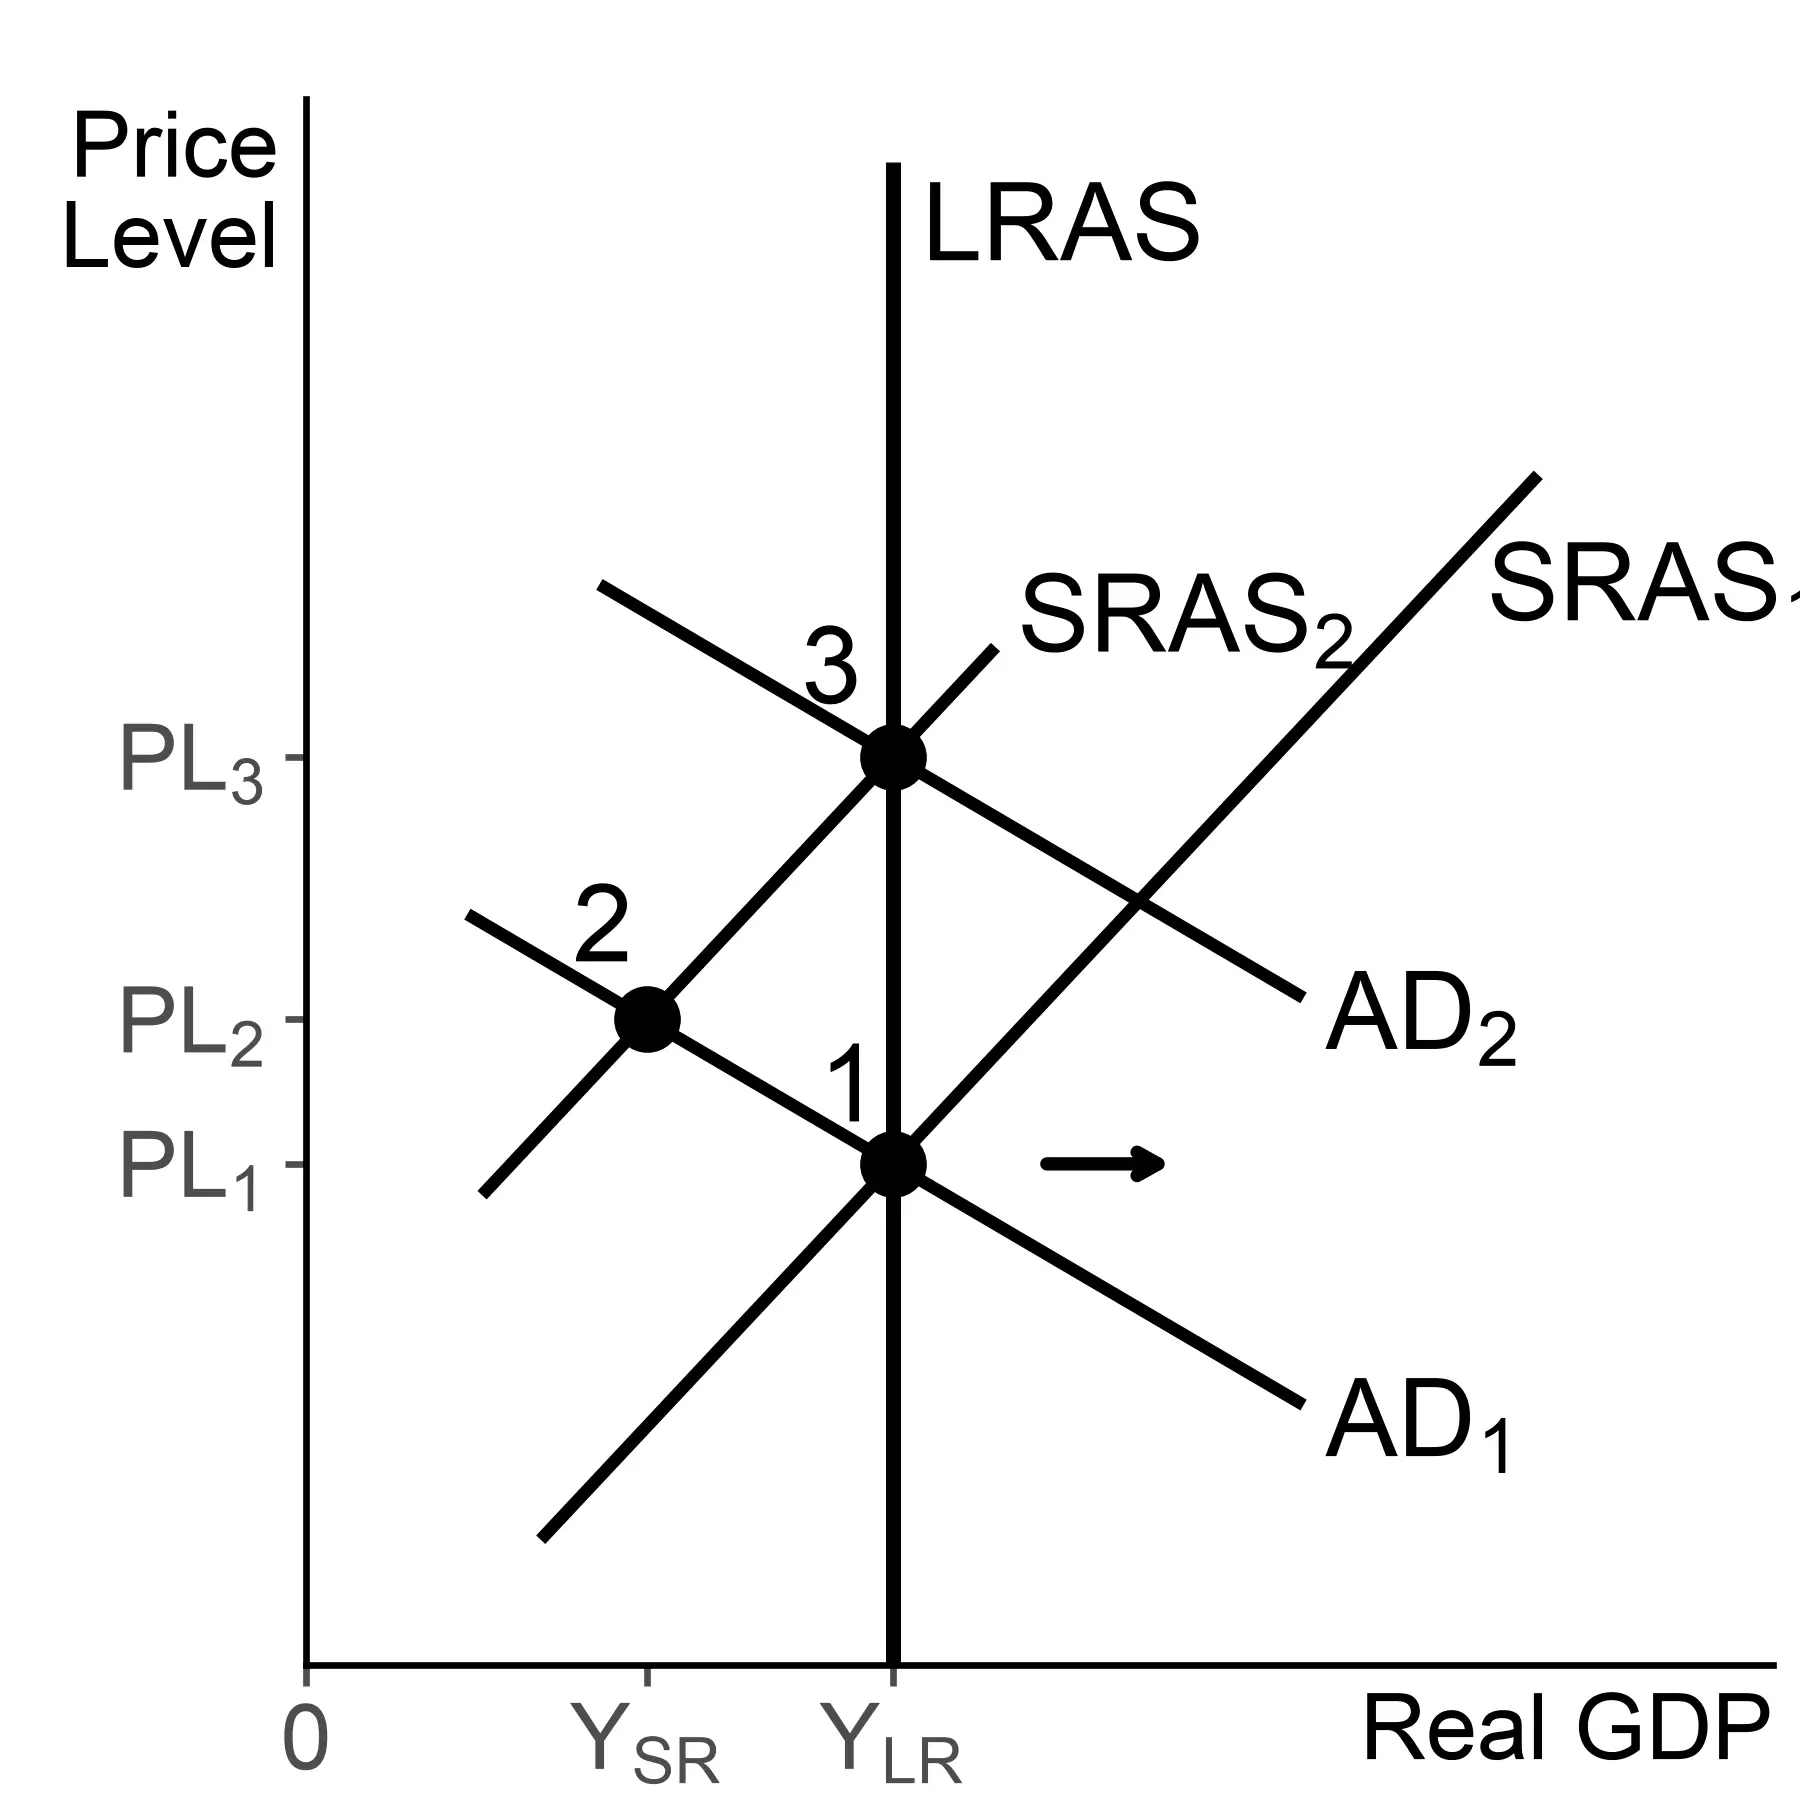
Expansionary fiscal policy could take the form of increased government spending, increased transfers, or tax cuts. Any of these would shift AD to the right, and regardless of the reason for a recession, these fiscal changes increase Y and PL.

Expansionary fiscal policy shifts $AD$ to the right, moving the economy from point 2 to point 3, back at potential GDP with a higher price level
Fiscal response to stagflation
Achievable

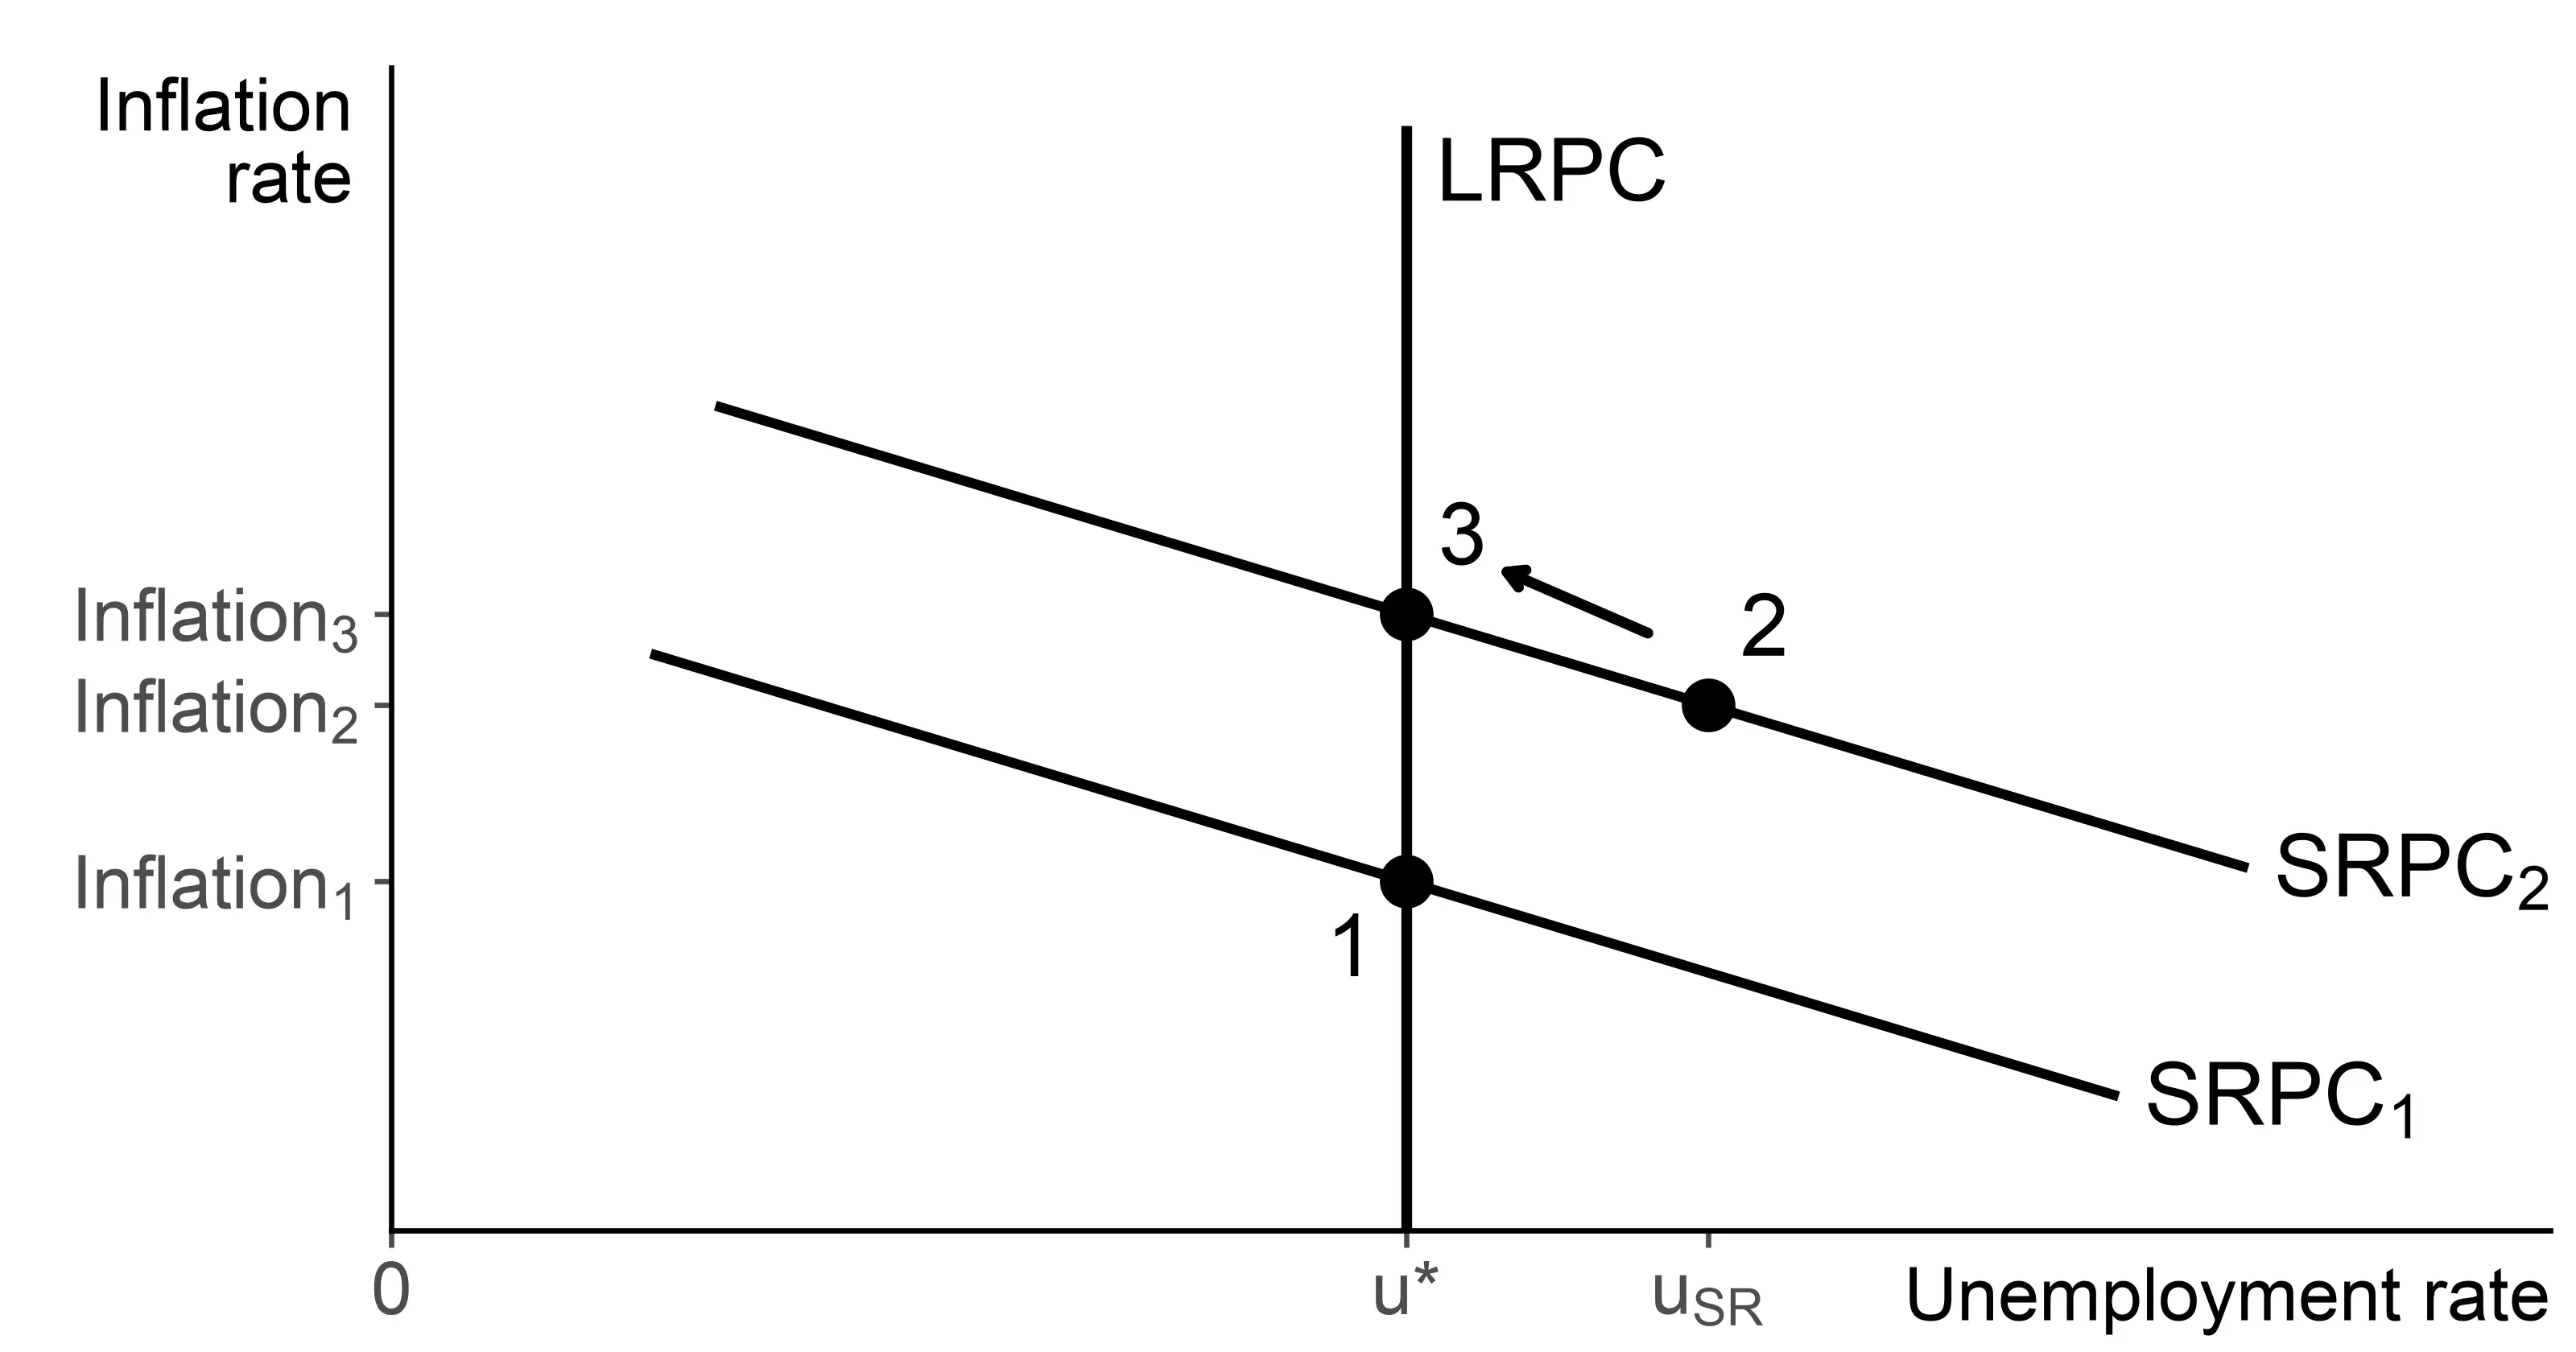
This moves the economy along the new short run Phillips curve, with lower unemployment in exchange for higher inflation.

A movement along $SRPC_2$ from point 2 to point 3, with lower unemployment and higher inflation
Fiscal response on the Phillips curve
Achievable

Real GDP and unemployment return to the long run level. In exchange the price level ends up permanently higher. Inflation itself comes back down once expectations settle, because the long run Phillips curve is vertical. In addition, the government takes on debt, which increases interest rates. This crowds out private investment and makes payments on previous debt more expensive.

Monetary Policy Response

Expansionary monetary policy is achieved by expanding the money supply, which lowers interest rates and shifts AD to the right. Policy lags are a factor that complicates monetary policy versus fiscal policy.

For monetary policy the important policy lag is implementation lag, which is slower. This means that monetary policy will overshoot, or push the economy past full employment in the short run. This is especially true if monetary policy is combined with fiscal policy. Given recent US experiences with responses to recessions and economic crises, it is also fair to assume overshooting because policymakers would prefer to do “too much” rather than “too little.”

The long run adjustment to this monetary policy action is for prices to adjust upwards and for inflation expectations to rise. Monetary policy does close the recessionary gap in the long run, but can be considered to cause additional inflation due to implementation lag.

Inflation expectations

The following discussion is slightly advanced for this level, but it highlights that the AD-AS model as we have seen it fails to pick up the full scope of the destructiveness of stagflation. The weakness is that permanent changes in inflation expectations shift AD as well.

Shocks that cause stagflation need not be transitory. If they are not, then expected inflation should rise. Because the changes are permanent, households prefer to purchase this year instead of next year and this increase in consumption shifts AD to the right.

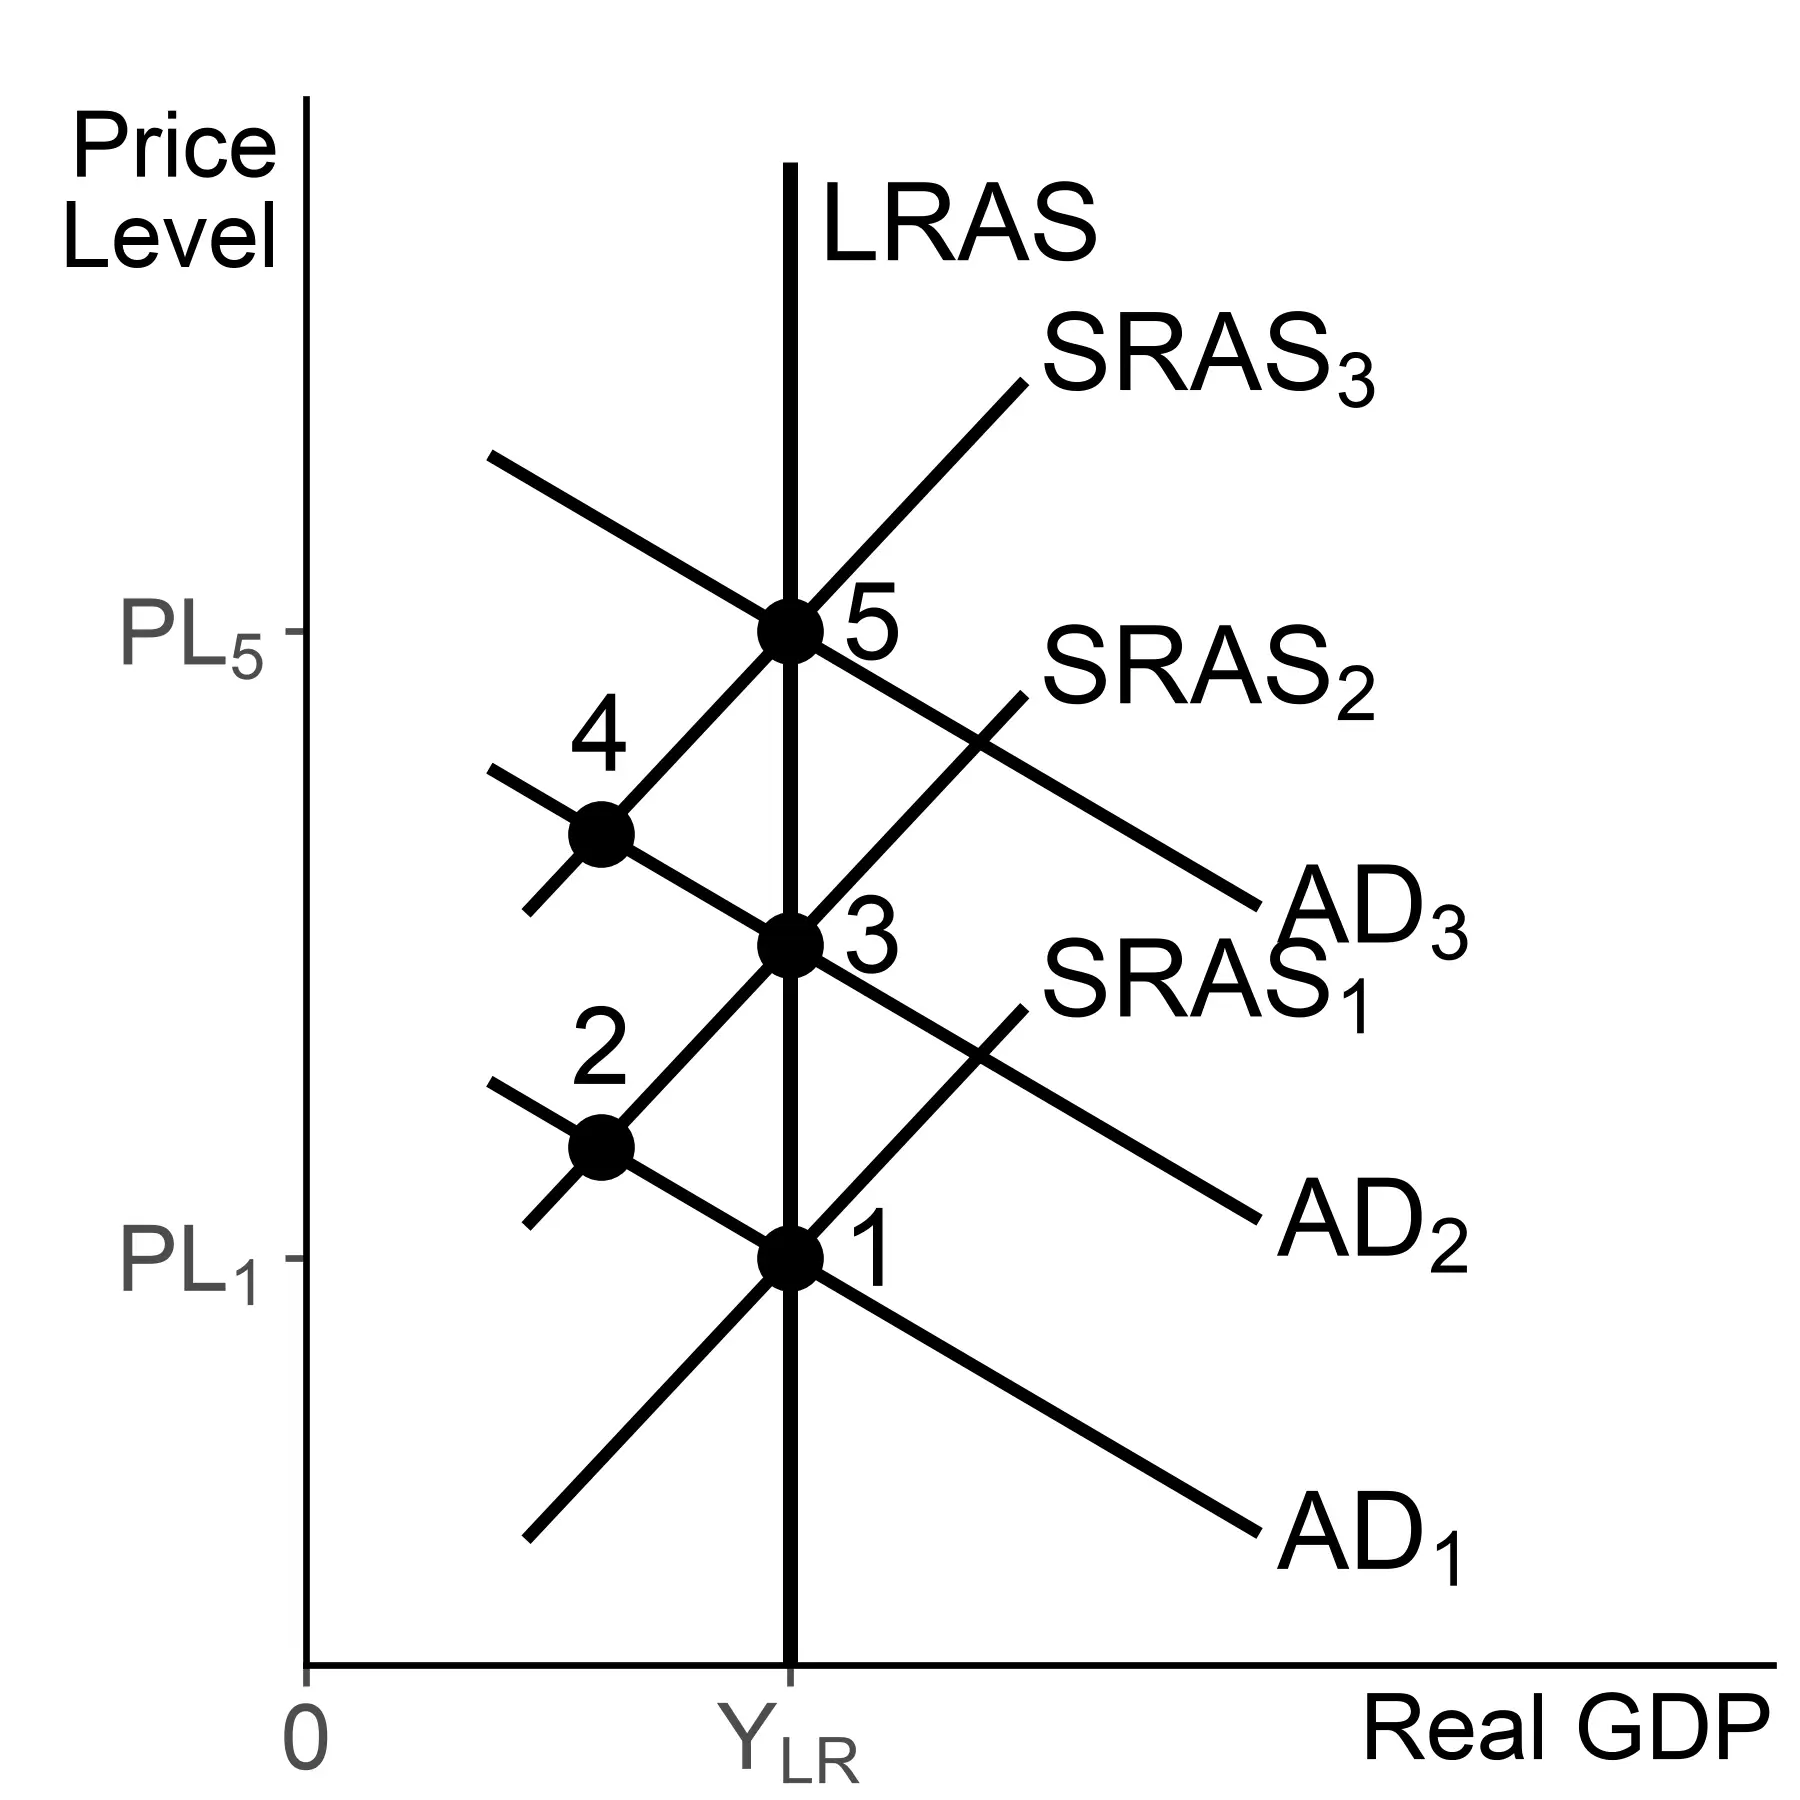
This cycle can repeat for many steps before settling into a long run equilibrium. At each stage, expected inflation increases, shifting SRAS further left and AD to the right. The result will be an economy back at the original equilibrium level of GDP but with a much higher price level.

$SRAS$ shifting left and $AD$ shifting right in turn, ending on $LRAS$ at a much higher price level
Stagflation with rising inflation expectations
Achievable

On the Phillips curve, unemployment returns to the natural rate, but inflation is significantly higher than the initial level. Recall that in the long run, the Phillips curve equilibrium level of inflation is the expected level of inflation.

Data example: Oil shocks of the 1970s and the Volcker recession

In the 1970s, the United States faced two large oil shocks stemming from political events in the Middle East. From October 1973 until March of 1974 the United States faced an oil embargo from oil producing Arab countries. Then in 1980, 4% of the world’s oil production was taken offline, and gas prices did not come back down until the mid-1980s.

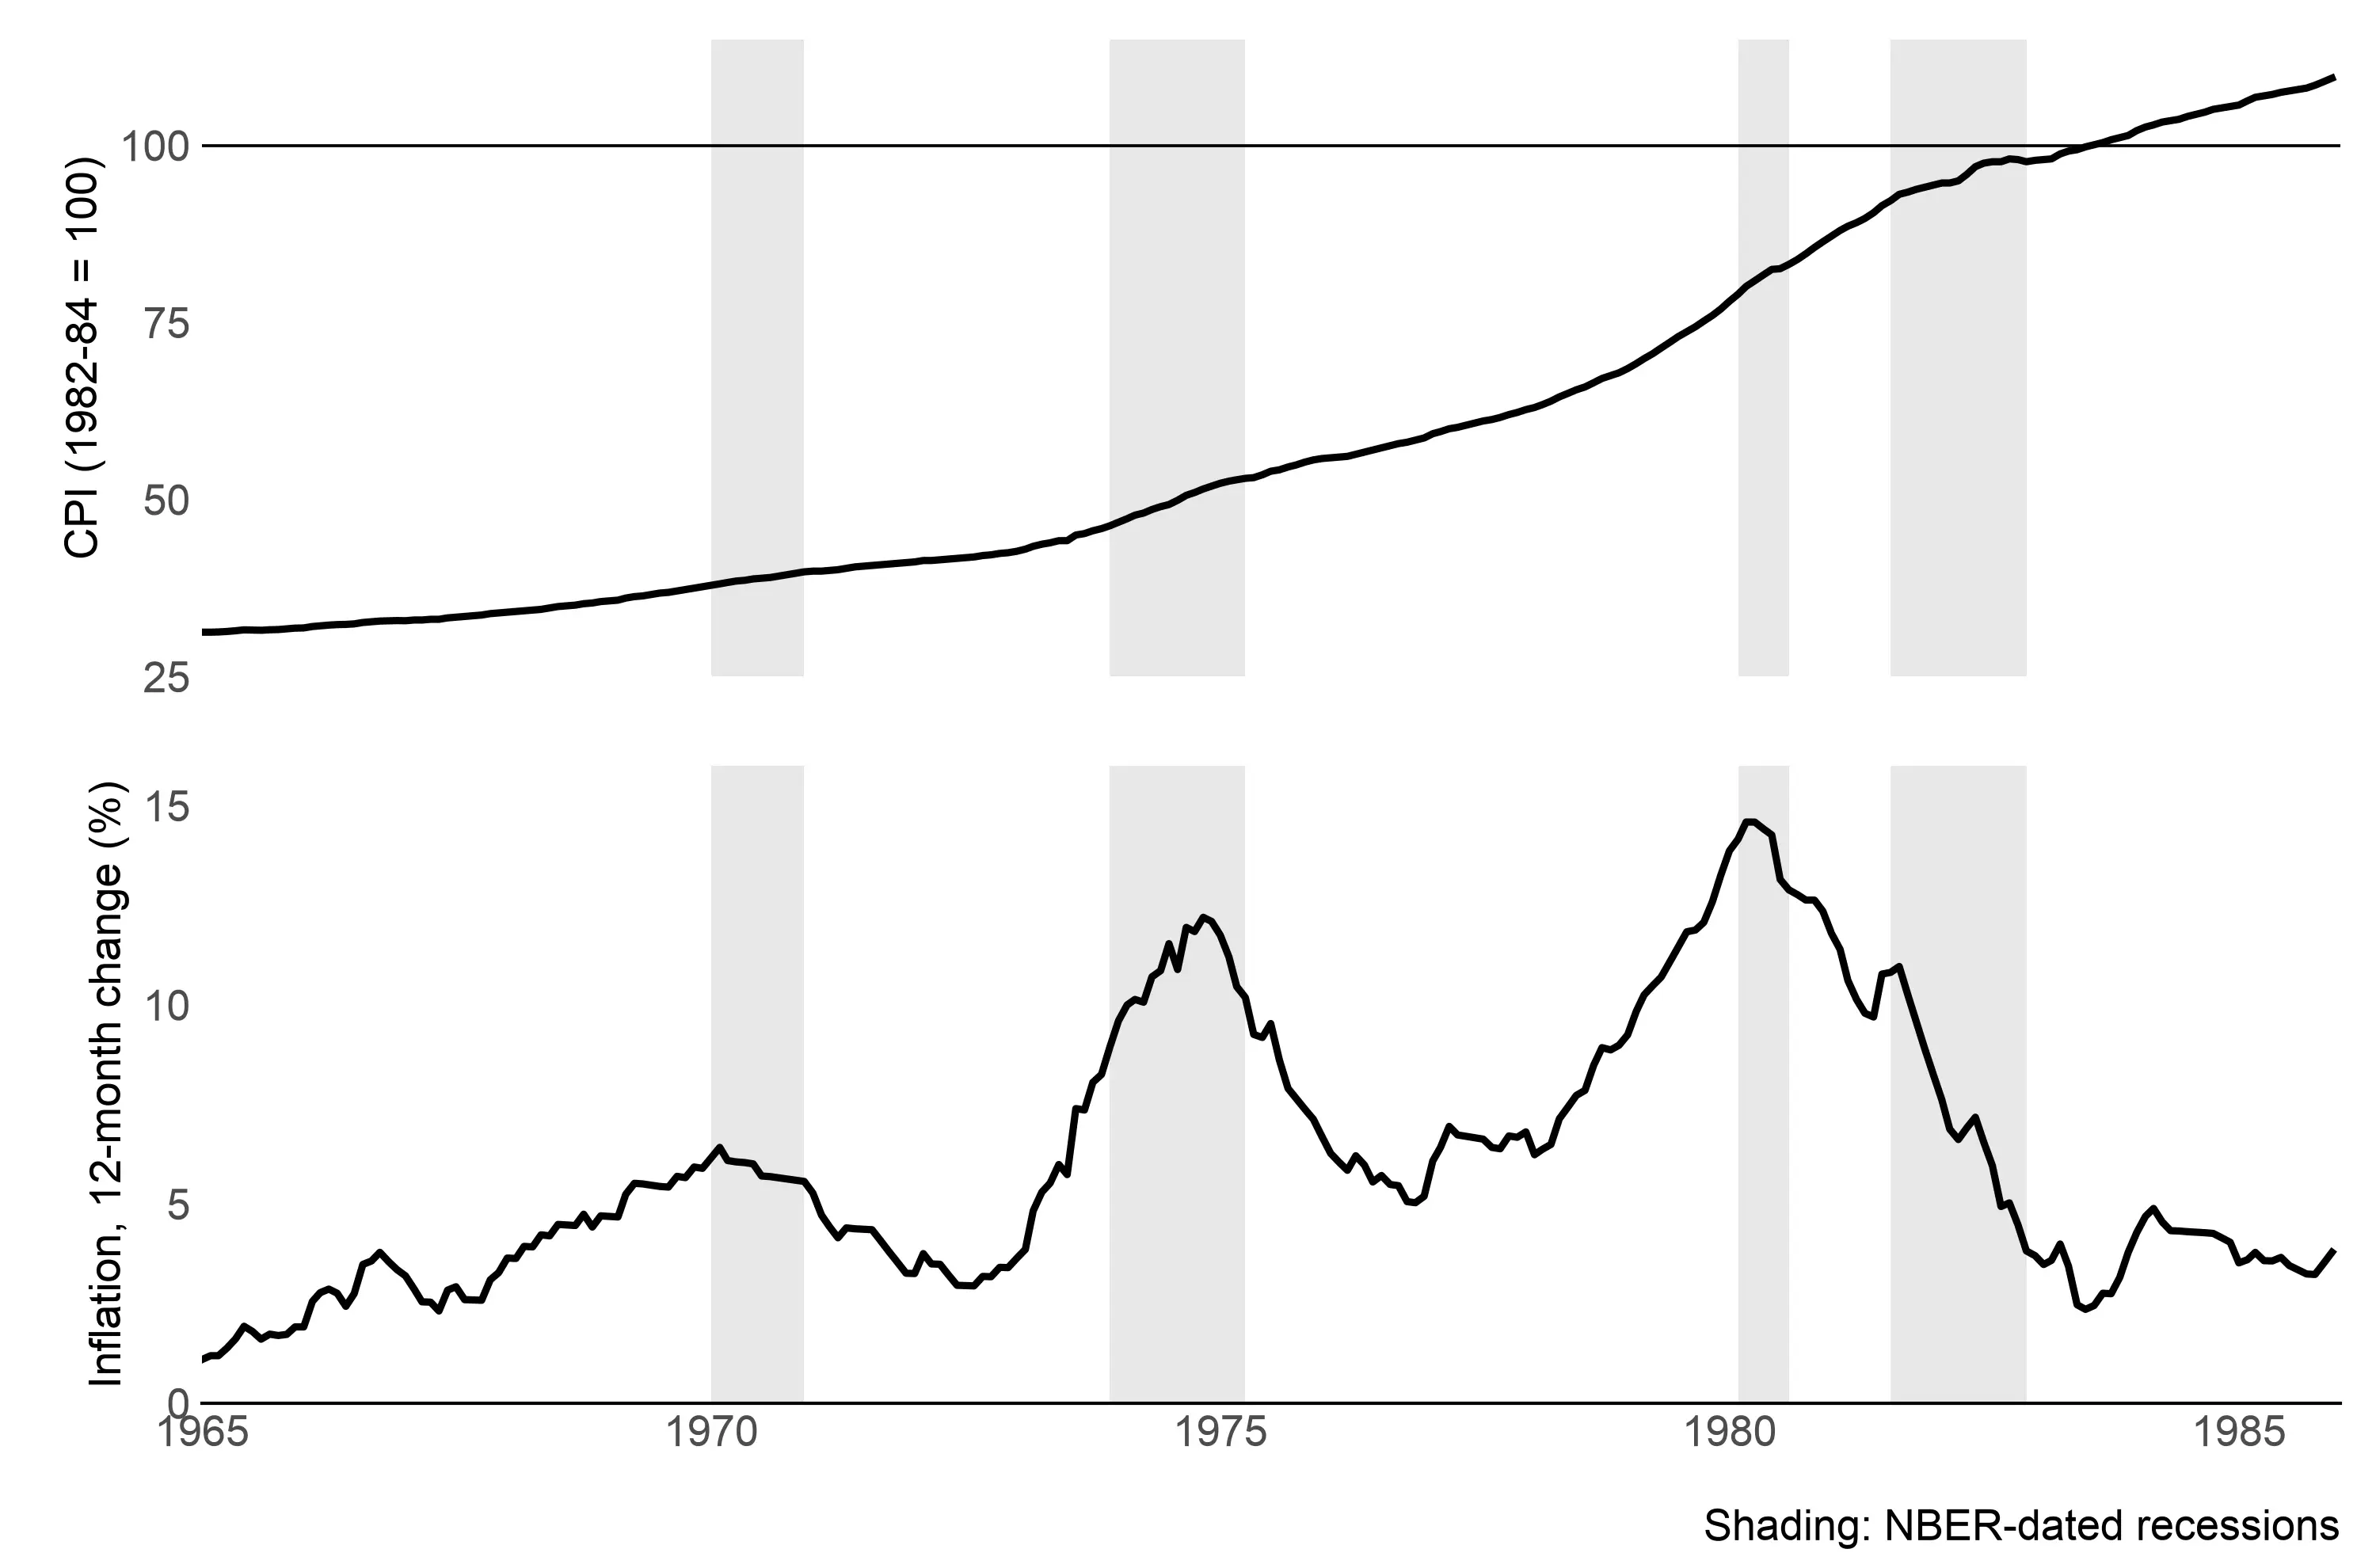
For reference here is inflation from 1965-1985.

The CPI rising from about 31 in 1965 to about 110 at the end of 1985, with 12-month inflation peaking near 12% in 1974 and near 15% in 1980
CPI and inflation (1965-1985)
U.S. Bureau of Labor Statistics (retrieved from FRED, Federal Reserve Bank of St. Louis)
/
Public domain

This gives a good idea why the base “year” for the CPI is the average of 1982-84.

The natural question is, if two oil shocks are what made inflation go up then what made inflation go down? The answer is primarily the actions of a new Chairman of the Federal Reserve, Paul Volcker, who was appointed in 1979 and would remain in the position until 1987.

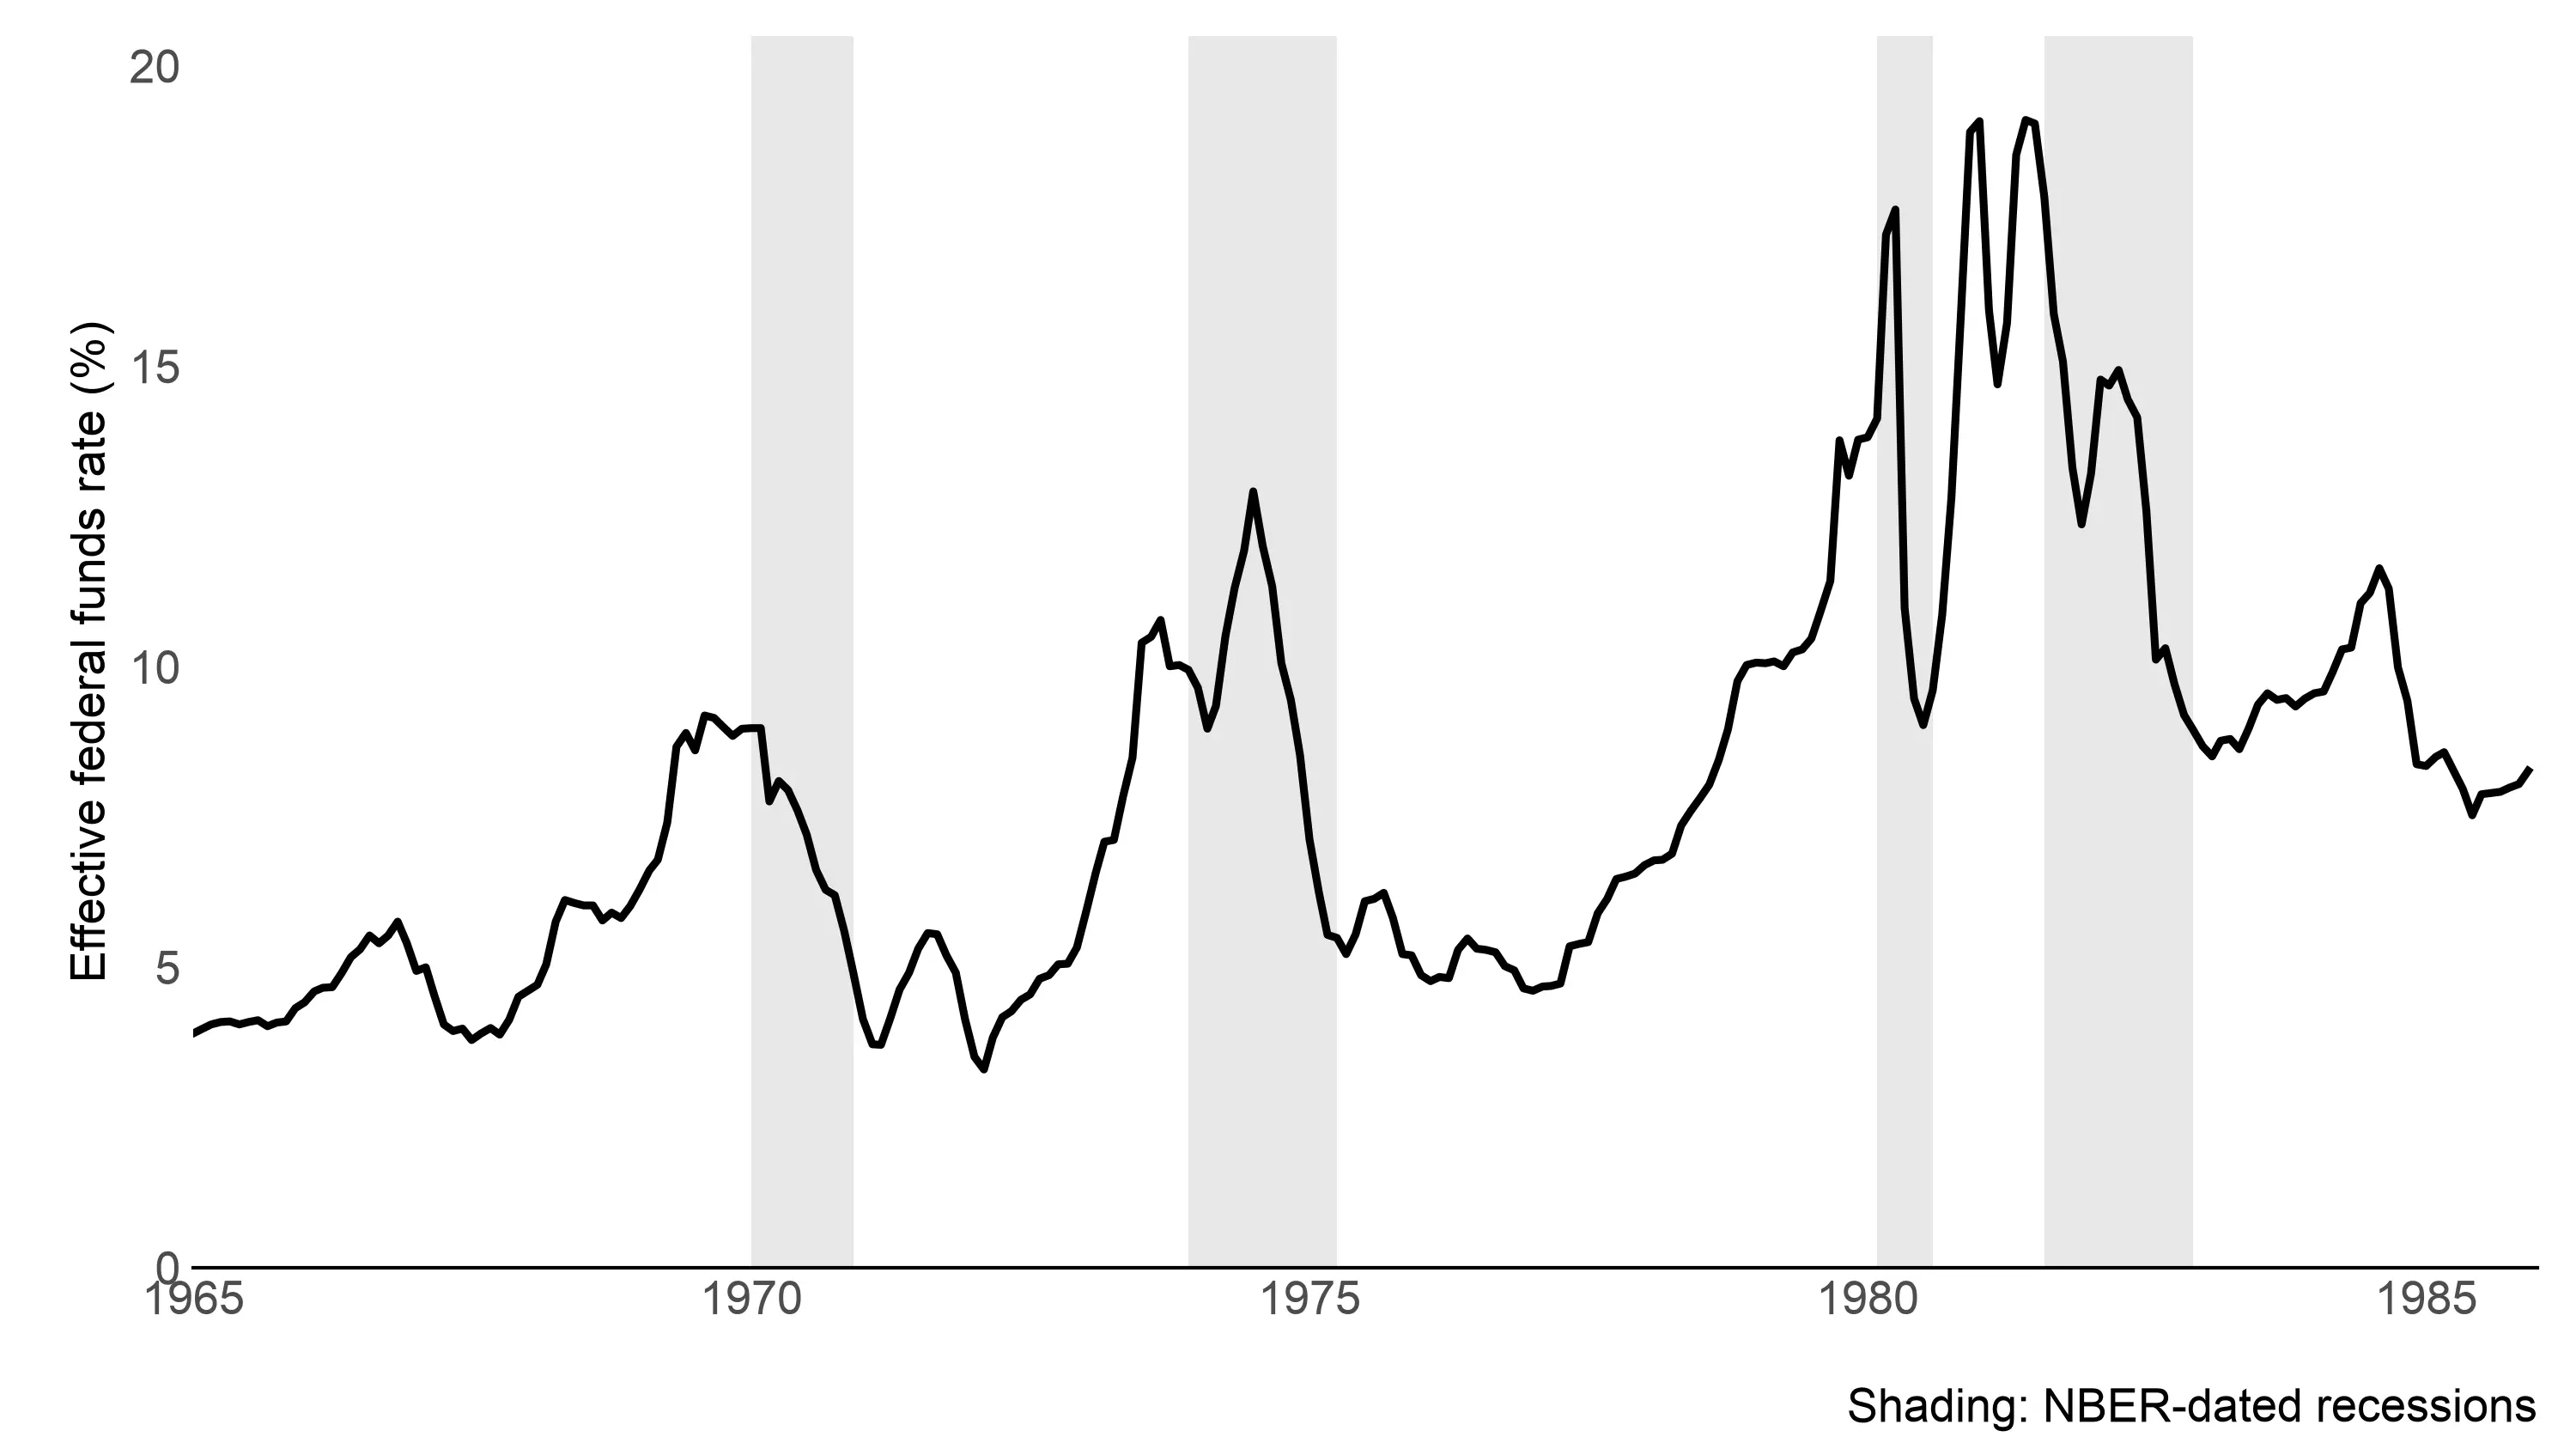
Here is the Fed funds rate from 1965-1985.

The effective federal funds rate rising above 19% in 1981, then falling to about 8% by the end of 1985
Federal funds rate (1965-1985)
Board of Governors of the Federal Reserve System (US) via FRED
/
Public domain

Volcker raised the Fed Funds rate to over 19% and signalled a commitment to eliminating inflation. This caused a recession in 1980, with unemployment rising to over 10%. During the recovery unemployment did not significantly decline, which led to the second recession. This is sometimes called a “double-dip” recession, one where the recovery is incomplete. So output shrinks, then grows, but ends up shrinking again.

It was the addition of the commitment to eliminating inflation along with the actions that matched that goal are what “killed” inflation in the United States. When inflation expectations rise, strong action must be taken for them to drop again.

From 1984 up until COVID in 2020, inflation was broadly considered tamed. Although a more nuanced view would say that not only were better monetary policy choices made starting with Volcker, there was also a fair amount of luck.

Stagflation basics & self-adjustment

  • Caused by negative supply shock: SRAS shifts left, causing recession (lower Y, higher unemployment) plus higher price level
  • Without intervention, SRAS shifts back right as shock dissipates; Y/unemployment return to original levels
  • On Phillips curve: SRPC shifts right (worse inflation/unemployment trade-off), then shifts back as shock fades, assuming inflation expectations unchanged

Fiscal policy response

  • Expansionary fiscal policy (↑ spending, ↑ transfers, tax cuts) shifts AD right
  • Moves economy along new SRPC: lower unemployment, higher inflation; closes recessionary gap, returns Y to potential
  • Trade-offs: price level permanently higher; government debt increases, raising interest rates, crowding out private investment, raising cost of servicing past debt

Monetary policy response

  • Expansionary monetary policy expands money supply, lowers interest rates, shifts AD right
  • Implementation lag is slow, causing overshoot (economy pushed past full employment), especially if combined with fiscal policy
  • Policymakers historically bias toward “too much” stimulus
  • Long run: prices adjust upward, inflation expectations rise; recessionary gap closes but with added inflation

Inflation expectations amplifying stagflation

  • AD-AS model understates stagflation’s damage if shocks are permanent (not transitory)
  • Rising expected inflation shifts AD right (consumers buy now vs. later) while SRAS shifts further left repeatedly
  • Process repeats until new equilibrium: Y back to original level, but price level much higher
  • On Phillips curve: unemployment returns to natural rate, but inflation settles much higher since long-run inflation = expected inflation

Historical example: 1970s oil shocks & Volcker recession

  • Two oil shocks (1973-74 embargo, 1980 supply cut) drove inflation up sharply (CPI base period reflects this: 1982-84 average)
  • Volcker (Fed Chair, 1979-87) raised Fed funds rate above 19%, committing credibly to ending inflation
  • Caused “double-dip” recession (1980, then second recession) with unemployment over 10%, incomplete recovery between dips
  • Combination of strong credible action + commitment successfully broke inflation expectations; inflation stayed tamed 1984-2020
  • Lesson: once inflation expectations rise, strong decisive policy action needed to reverse them

Sign up for free to take 5 quiz questions on this topic

Previous
Next  | 6.1 Exchange rates
All rights reserved ©2016 - 2026 Achievable, Inc.

Stagflation

As a final look at the long run impacts, we are going to review an extended example looking at stagflation. Recall that this situation is most likely caused by a negative supply shock, a significant shift of SRAS to the left. Not only does it cause a recession, lowering output and increasing unemployment but it also increases the price level.

If no policy action is taken, the transition to the long run is for prices to fall. The supply shock dissipates and GDP and unemployment return to where they were before.

If long run inflation expectations do not change, there is a similar outcome looking at Phillips curves. The short run Phillips curve shifts right, increasing inflation and increasing unemployment. The trade-off between inflation and unemployment also gets worse. For every level of unemployment, inflation is higher.

As the supply shock dissipates, the SRPC shifts back to its original position, returning unemployment and inflation to their starting levels.

As with any recession, policymakers may wish to shorten the recession rather than allow the economy to self-adjust. However, each policy option has significant trade-offs. To close a recessionary gap, our basic policy recommendation is expansionary policy.

Fiscal Policy Response

Expansionary fiscal policy could take the form of increased government spending, increased transfers, or tax cuts. Any of these would shift AD to the right, and regardless of the reason for a recession, these fiscal changes increase Y and PL.

This moves the economy along the new short run Phillips curve, with lower unemployment in exchange for higher inflation.

Real GDP and unemployment return to the long run level. In exchange the price level ends up permanently higher. Inflation itself comes back down once expectations settle, because the long run Phillips curve is vertical. In addition, the government takes on debt, which increases interest rates. This crowds out private investment and makes payments on previous debt more expensive.

Monetary Policy Response

Expansionary monetary policy is achieved by expanding the money supply, which lowers interest rates and shifts AD to the right. Policy lags are a factor that complicates monetary policy versus fiscal policy.

For monetary policy the important policy lag is implementation lag, which is slower. This means that monetary policy will overshoot, or push the economy past full employment in the short run. This is especially true if monetary policy is combined with fiscal policy. Given recent US experiences with responses to recessions and economic crises, it is also fair to assume overshooting because policymakers would prefer to do “too much” rather than “too little.”

The long run adjustment to this monetary policy action is for prices to adjust upwards and for inflation expectations to rise. Monetary policy does close the recessionary gap in the long run, but can be considered to cause additional inflation due to implementation lag.

Inflation expectations

The following discussion is slightly advanced for this level, but it highlights that the AD-AS model as we have seen it fails to pick up the full scope of the destructiveness of stagflation. The weakness is that permanent changes in inflation expectations shift AD as well.

Shocks that cause stagflation need not be transitory. If they are not, then expected inflation should rise. Because the changes are permanent, households prefer to purchase this year instead of next year and this increase in consumption shifts AD to the right.

This cycle can repeat for many steps before settling into a long run equilibrium. At each stage, expected inflation increases, shifting SRAS further left and AD to the right. The result will be an economy back at the original equilibrium level of GDP but with a much higher price level.

On the Phillips curve, unemployment returns to the natural rate, but inflation is significantly higher than the initial level. Recall that in the long run, the Phillips curve equilibrium level of inflation is the expected level of inflation.

Data example: Oil shocks of the 1970s and the Volcker recession

In the 1970s, the United States faced two large oil shocks stemming from political events in the Middle East. From October 1973 until March of 1974 the United States faced an oil embargo from oil producing Arab countries. Then in 1980, 4% of the world’s oil production was taken offline, and gas prices did not come back down until the mid-1980s.

For reference here is inflation from 1965-1985.

This gives a good idea why the base “year” for the CPI is the average of 1982-84.

The natural question is, if two oil shocks are what made inflation go up then what made inflation go down? The answer is primarily the actions of a new Chairman of the Federal Reserve, Paul Volcker, who was appointed in 1979 and would remain in the position until 1987.

Here is the Fed funds rate from 1965-1985.

Volcker raised the Fed Funds rate to over 19% and signalled a commitment to eliminating inflation. This caused a recession in 1980, with unemployment rising to over 10%. During the recovery unemployment did not significantly decline, which led to the second recession. This is sometimes called a “double-dip” recession, one where the recovery is incomplete. So output shrinks, then grows, but ends up shrinking again.

It was the addition of the commitment to eliminating inflation along with the actions that matched that goal are what “killed” inflation in the United States. When inflation expectations rise, strong action must be taken for them to drop again.

From 1984 up until COVID in 2020, inflation was broadly considered tamed. Although a more nuanced view would say that not only were better monetary policy choices made starting with Volcker, there was also a fair amount of luck.

Key points

Stagflation basics & self-adjustment

  • Caused by negative supply shock: SRAS shifts left, causing recession (lower Y, higher unemployment) plus higher price level
  • Without intervention, SRAS shifts back right as shock dissipates; Y/unemployment return to original levels
  • On Phillips curve: SRPC shifts right (worse inflation/unemployment trade-off), then shifts back as shock fades, assuming inflation expectations unchanged

Fiscal policy response

  • Expansionary fiscal policy (↑ spending, ↑ transfers, tax cuts) shifts AD right
  • Moves economy along new SRPC: lower unemployment, higher inflation; closes recessionary gap, returns Y to potential
  • Trade-offs: price level permanently higher; government debt increases, raising interest rates, crowding out private investment, raising cost of servicing past debt

Monetary policy response

  • Expansionary monetary policy expands money supply, lowers interest rates, shifts AD right
  • Implementation lag is slow, causing overshoot (economy pushed past full employment), especially if combined with fiscal policy
  • Policymakers historically bias toward “too much” stimulus
  • Long run: prices adjust upward, inflation expectations rise; recessionary gap closes but with added inflation

Inflation expectations amplifying stagflation

  • AD-AS model understates stagflation’s damage if shocks are permanent (not transitory)
  • Rising expected inflation shifts AD right (consumers buy now vs. later) while SRAS shifts further left repeatedly
  • Process repeats until new equilibrium: Y back to original level, but price level much higher
  • On Phillips curve: unemployment returns to natural rate, but inflation settles much higher since long-run inflation = expected inflation

Historical example: 1970s oil shocks & Volcker recession

  • Two oil shocks (1973-74 embargo, 1980 supply cut) drove inflation up sharply (CPI base period reflects this: 1982-84 average)
  • Volcker (Fed Chair, 1979-87) raised Fed funds rate above 19%, committing credibly to ending inflation
  • Caused “double-dip” recession (1980, then second recession) with unemployment over 10%, incomplete recovery between dips
  • Combination of strong credible action + commitment successfully broke inflation expectations; inflation stayed tamed 1984-2020
  • Lesson: once inflation expectations rise, strong decisive policy action needed to reverse them

More from Long-run consequences of stabilization policy

  • The Phillips curve
  • Fiscal policy in the long run
  • Monetary policy in the long run