


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
ACCA Financial Accounting
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. The context and purpose of financial reporting
2. Accounting principles, concepts and qualitative characteristics
3. Double-entry bookkeeping and accounting systems
4. Recording transactions and events
5. Reconciliations
5.1 Bank reconciliation statement
5.2 Payables account reconciliation
6. Preparing trial balance
7. Preparing financial statements
8. Preparing basic consolidated financial statements
9. Interpretation of financial statements
Wrapping up
Achievable logoAchievable logo
5.2 Payables account reconciliation
Achievable ACCA Financial Accounting
5. Reconciliations
Our ACCA course is currently in development and is a work-in-progress.

Payables account reconciliation

8 min read
Font
Discuss
Share
Feedback

This chapter explains what the payables ledger is used for, why you reconcile it to supplier statements, what typically causes differences, and how to prepare (and correct) a reconciliation. You’ll learn how to spot timing differences, omissions, and errors so liabilities are reported accurately.

Learning objectives

By the end of this chapter, you should be able to:

  • Explain the purpose of the payables general ledger account and how it relates to double-entry bookkeeping.
  • Explain the purpose of reconciling the payables general ledger account to external documents.
  • Prepare a reconciliation of the payables general ledger account to supplier statements.
  • Identify and correct errors that would be highlighted by performing a reconciliation of the payables general ledger account.
  • Identify the payables balance to be reported in the financial statements.

Introduction

Businesses often buy goods and services on credit. When that happens, amounts owed to suppliers build up in the payables ledger. Credit purchases are recorded as a debit to purchases and a credit to trade payables, so the payables account normally carries a credit balance. Paying a supplier is recorded as a debit to trade payables and a credit to cash, which reduces the amount owed, and a purchase return is recorded as a debit to trade payables and a credit to purchase returns. The closing credit balance on the payables account is the amount owed to suppliers, and that balance is reported as a current liability in the statement of financial position.

At month-end, suppliers usually send a statement showing:

  • the opening balance
  • invoices issued
  • payments received
  • credit notes issued
  • the closing balance

Just like a bank reconciliation compares your cash book to the bank statement, a payables reconciliation compares your payables ledger balance to the supplier’s statement. In an ideal situation, the closing balances match. When they don’t, the difference is usually explained by timing, missing entries, or errors.

Causes of payables differences

Below are some of the reasons why the payables ledger may not agree with the supplier statements.

  • Timing differences resulting from goods or payments in transit
    • Goods in transit: Goods shipped by the supplier, usually, near month-end, may be recorded on the supplier’s statement but not yet received or recorded by the buyer. This creates a temporary difference between the supplier’s statement and the payables ledger balance until the goods arrive and are processed.
    • Payments in transit: Payments to the supplier, usually, near month-end, may be recorded in the payables ledger (reducing the balance) but not yet received or processed by the supplier. The payables ledger balance will show a lower balance while the supplier’s statement still reflects the higher unpaid amount until the payment clears.
  • Credit notes not yet processed: The business may have returned goods or identified pricing errors and therefore recorded a debit in the trade payables ledger account to reduce amounts owed. The buyer issues a debit note to record the return and notify the supplier; the supplier replies with its own credit note once it agrees to the adjustment. However, if the supplier hasn’t yet processed the return or agreed to the adjustment, their statement won’t reflect the reduction. The supplier statement will show a higher balance than the payables ledger account.
  • Recording errors and disputes: Either party may have made posting errors, duplicate entries, or recorded incorrect amounts. Disputes over quantities delivered, pricing agreements, or quality issues can also lead to different recorded balances while the issue is being resolved.

Why the need for payables ledger reconciliation?

Reconciling payables to external documents (supplier statements, invoices, delivery notes) helps ensure the accuracy and completeness of recorded liabilities.

A reconciliation helps you identify:

  • omitted invoices
  • understated or overstated invoices
  • duplicate entries
  • pricing errors
  • timing differences

It also helps prevent overpayment, detect fraud, maintain good supplier relationships, and ensure the financial statements reflect the actual amounts owed.

Preparation of the payables reconciliation

The following are steps you can follow to prepare the payables reconciliation.

  1. Trace or match each item on the trade payables ledger account to the supplier’s statement and mark them.
  2. Post the unmarked items on the supplier’s statement to the trade payables ledger account.
  3. Correct errors made in the payables ledger account.

Illustration: Payables ledger reconciliation

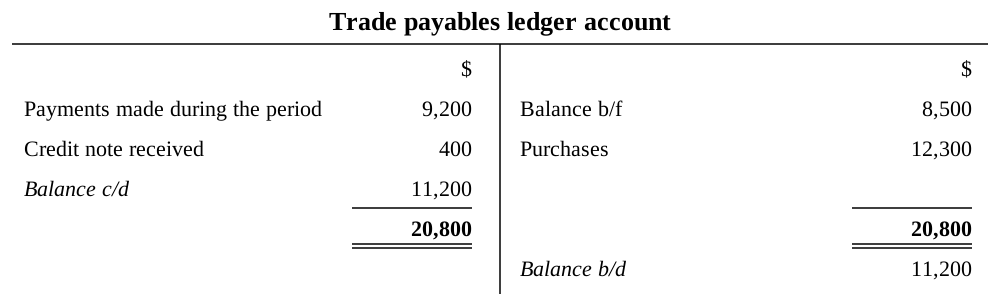
Kaufmano Trading Company maintains a trade payables ledger for all suppliers. The following ledger shows the activities with Reliable Suppliers Ltd for December 2024.

Trade payables ledger account: payments of 9,200, a credit note of 400 and balance c/d of 11,200 on the debit side; balance b/f of 8,500 and purchases of 12,300 on the credit side; totals of 20,800; balance b/d of 11,200.
Trade payables ledger account
Achievable

The statement received from the supplier shows that Kaufmano Trading Company owes $14,350.

Additional information:

  1. Goods worth $1,500 were delivered on 31 December, but the invoice was not received until 3 January 2025.
  2. A payment of $500 was made on 30 December but was not processed by the supplier until 2 January 2025.
  3. A debit note for $150 relating to damaged goods returned in December has not yet been received by the supplier.
  4. There appears to be an invoice for $1,000 worth of goods that the supplier delivered, but Kaufmano Trading Company has not recorded the invoice amount.

Required: Prepare a reconciliation statement showing how the payables ledger balance of $11,200 reconciles to the supplier statement balance of $14,350.

Suggested solution

Step 1: Identify items that were not recorded in the payables ledger and their effect on the ledger account.

Do you know the items?

(spoiler)
  1. Goods worth $1,500 would have caused the payables ledger balance to be lower than the supplier statement.
  2. Invoice for $1,000 worth of goods delivered but not recorded. This would also have caused the payables ledger balance to be lower than the supplier’s statement.

When reconciling the payables ledger to the supplier statement, both unrecorded items should be credited (added) to the payables ledger. This brings the ledger up to the same position as the supplier statement, so both balances are on “common ground.”

If those items already appear on the supplier statement, then once they are entered in the payables ledger, the two balances should agree.

Step 2: Identify items that were recorded in the payables ledger but not in the supplier statements and their effect on the ledger account.

Do you know the items?

(spoiler)
  1. Payment of $500 made on 30 December. This would have caused the supplier statement balance to be higher.
  2. Debit note for $150 for damaged goods returned. This would have also caused the supplier statement balance to be higher.

For both items, when reconciling from the payables ledger to the supplier statement, the amounts would be added to the ledger balance.

If you reconcile in the other direction - starting from the supplier statement balance down to the ledger balance - every adjustment above simply flips sign: additions become subtractions, and subtractions become additions.

Step 3: Prepare a reconciliation statement showing how the payables ledger balance of $11,200 reconciles to the supplier statement balance of $14,350.

(spoiler)

Kaufmano Trading Company
Payables reconciliation statement

$ $
Balance per payables ledger 11,200
Add: items recorded by supplier but not in our ledger
Goods delivered on 31 December (invoice not yet received) 1,500
Error - invoice not recorded 1,000 2,500
Add: items recorded in our ledger but not yet by the supplier
Payment in transit 500
Debit note for goods returned (not yet received by the supplier) 150 650
Balance per supplier statement 14,350

Correcting the ledger and the reported balance

Two of the four differences are genuine omissions from Kaufmano’s own records, not just timing lags on the supplier’s side: the goods delivered on 31 December and the invoice the supplier issued that Kaufmano never recorded. Both represent real purchases that happened before year-end, so they need to be posted to the ledger rather than left as reconciling items:

  • Goods delivered 31 December, invoice not yet received: debit purchases, credit trade payables, $1,500.
  • Invoice for goods delivered but not recorded: debit purchases, credit trade payables, $1,000.

Posting both entries brings the ledger balance to $11,200 + $1,500 + $1,000 = $13,700.

The $500 payment and the $150 debit note are different - Kaufmano already recorded both correctly, and it’s the supplier’s records that haven’t caught up yet. These stay as timing differences in the reconciliation rather than ledger corrections: $13,700 + $500 + $150 = $14,350, which matches the supplier’s statement.

Because the $1,500 and $1,000 items reflect real purchases that occurred before year-end, the corrected balance of $13,700 - not the supplier’s $14,350 - is the trade payables liability Kaufmano reports in its financial statements.

Payables ledger basics

  • Credit purchases: debit purchases, credit trade payables; payments: debit trade payables, credit cash; purchase returns: debit trade payables, credit purchase returns
  • Payables account normally carries credit balance = amount owed to suppliers
  • Closing credit balance reported as current liability in statement of financial position
  • Supplier statements show opening balance, invoices, payments, credit notes, closing balance

Causes of payables vs. supplier statement differences

  • Timing differences: goods in transit (supplier records before buyer receives/records) and payments in transit (buyer records before supplier processes)
  • Credit notes not yet processed: buyer issues debit note for returns/pricing errors, but supplier hasn’t yet agreed/recorded matching credit note
  • Recording errors, duplicate entries, or disputes over quantity/price/quality

Purpose of reconciliation

  • Ensures accuracy and completeness of recorded liabilities
  • Identifies omitted/understated/overstated invoices, duplicates, pricing errors, timing differences
  • Helps prevent overpayment, detect fraud, maintain supplier relationships, ensure accurate financial statements

Preparing the reconciliation

  • Steps: match ledger items to supplier statement; post unmarked supplier statement items to the ledger; correct ledger errors
  • Items recorded by supplier but missing from ledger (e.g., goods delivered but invoice not yet received, unrecorded invoice) → add to ledger balance
  • Items recorded in ledger but not yet by supplier (e.g., payment in transit, debit note not yet received by supplier) → add to ledger balance when reconciling ledger to supplier statement (direction determines sign; reversing direction flips all additions/subtractions)
  • Reconciliation statement bridges ledger balance to supplier statement balance through these adjustments

Correcting the ledger and reporting the liability

  • Distinguish genuine omissions (real purchases not yet recorded by buyer) from pure timing differences (items correctly recorded by buyer, lagging on supplier’s side)
  • Genuine omissions must be posted: debit purchases, credit trade payables, for each missing invoice/goods received
  • Timing differences (payments/debit notes already recorded by buyer) remain as reconciling items only, not ledger corrections
  • The corrected ledger balance (after posting omissions), not the supplier’s statement figure, is the amount reported as trade payables in the financial statements

Sign up for free to take 7 quiz questions on this topic

Previous
Next  | 6.1 The trial balance
All rights reserved ©2016 - 2026 Achievable, Inc.

Payables account reconciliation

This chapter explains what the payables ledger is used for, why you reconcile it to supplier statements, what typically causes differences, and how to prepare (and correct) a reconciliation. You’ll learn how to spot timing differences, omissions, and errors so liabilities are reported accurately.

Learning objectives

By the end of this chapter, you should be able to:

  • Explain the purpose of the payables general ledger account and how it relates to double-entry bookkeeping.
  • Explain the purpose of reconciling the payables general ledger account to external documents.
  • Prepare a reconciliation of the payables general ledger account to supplier statements.
  • Identify and correct errors that would be highlighted by performing a reconciliation of the payables general ledger account.
  • Identify the payables balance to be reported in the financial statements.

Introduction

Businesses often buy goods and services on credit. When that happens, amounts owed to suppliers build up in the payables ledger. Credit purchases are recorded as a debit to purchases and a credit to trade payables, so the payables account normally carries a credit balance. Paying a supplier is recorded as a debit to trade payables and a credit to cash, which reduces the amount owed, and a purchase return is recorded as a debit to trade payables and a credit to purchase returns. The closing credit balance on the payables account is the amount owed to suppliers, and that balance is reported as a current liability in the statement of financial position.

At month-end, suppliers usually send a statement showing:

  • the opening balance
  • invoices issued
  • payments received
  • credit notes issued
  • the closing balance

Just like a bank reconciliation compares your cash book to the bank statement, a payables reconciliation compares your payables ledger balance to the supplier’s statement. In an ideal situation, the closing balances match. When they don’t, the difference is usually explained by timing, missing entries, or errors.

Causes of payables differences

Below are some of the reasons why the payables ledger may not agree with the supplier statements.

  • Timing differences resulting from goods or payments in transit
    • Goods in transit: Goods shipped by the supplier, usually, near month-end, may be recorded on the supplier’s statement but not yet received or recorded by the buyer. This creates a temporary difference between the supplier’s statement and the payables ledger balance until the goods arrive and are processed.
    • Payments in transit: Payments to the supplier, usually, near month-end, may be recorded in the payables ledger (reducing the balance) but not yet received or processed by the supplier. The payables ledger balance will show a lower balance while the supplier’s statement still reflects the higher unpaid amount until the payment clears.
  • Credit notes not yet processed: The business may have returned goods or identified pricing errors and therefore recorded a debit in the trade payables ledger account to reduce amounts owed. The buyer issues a debit note to record the return and notify the supplier; the supplier replies with its own credit note once it agrees to the adjustment. However, if the supplier hasn’t yet processed the return or agreed to the adjustment, their statement won’t reflect the reduction. The supplier statement will show a higher balance than the payables ledger account.
  • Recording errors and disputes: Either party may have made posting errors, duplicate entries, or recorded incorrect amounts. Disputes over quantities delivered, pricing agreements, or quality issues can also lead to different recorded balances while the issue is being resolved.

Why the need for payables ledger reconciliation?

Reconciling payables to external documents (supplier statements, invoices, delivery notes) helps ensure the accuracy and completeness of recorded liabilities.

A reconciliation helps you identify:

  • omitted invoices
  • understated or overstated invoices
  • duplicate entries
  • pricing errors
  • timing differences

It also helps prevent overpayment, detect fraud, maintain good supplier relationships, and ensure the financial statements reflect the actual amounts owed.

Preparation of the payables reconciliation

The following are steps you can follow to prepare the payables reconciliation.

  1. Trace or match each item on the trade payables ledger account to the supplier’s statement and mark them.
  2. Post the unmarked items on the supplier’s statement to the trade payables ledger account.
  3. Correct errors made in the payables ledger account.

Illustration: Payables ledger reconciliation

Kaufmano Trading Company maintains a trade payables ledger for all suppliers. The following ledger shows the activities with Reliable Suppliers Ltd for December 2024.

The statement received from the supplier shows that Kaufmano Trading Company owes $14,350.

Additional information:

  1. Goods worth $1,500 were delivered on 31 December, but the invoice was not received until 3 January 2025.
  2. A payment of $500 was made on 30 December but was not processed by the supplier until 2 January 2025.
  3. A debit note for $150 relating to damaged goods returned in December has not yet been received by the supplier.
  4. There appears to be an invoice for $1,000 worth of goods that the supplier delivered, but Kaufmano Trading Company has not recorded the invoice amount.

Required: Prepare a reconciliation statement showing how the payables ledger balance of $11,200 reconciles to the supplier statement balance of $14,350.

Suggested solution

Step 1: Identify items that were not recorded in the payables ledger and their effect on the ledger account.

Do you know the items?

(spoiler)
  1. Goods worth $1,500 would have caused the payables ledger balance to be lower than the supplier statement.
  2. Invoice for $1,000 worth of goods delivered but not recorded. This would also have caused the payables ledger balance to be lower than the supplier’s statement.

When reconciling the payables ledger to the supplier statement, both unrecorded items should be credited (added) to the payables ledger. This brings the ledger up to the same position as the supplier statement, so both balances are on “common ground.”

If those items already appear on the supplier statement, then once they are entered in the payables ledger, the two balances should agree.

Step 2: Identify items that were recorded in the payables ledger but not in the supplier statements and their effect on the ledger account.

Do you know the items?

(spoiler)
  1. Payment of $500 made on 30 December. This would have caused the supplier statement balance to be higher.
  2. Debit note for $150 for damaged goods returned. This would have also caused the supplier statement balance to be higher.

For both items, when reconciling from the payables ledger to the supplier statement, the amounts would be added to the ledger balance.

If you reconcile in the other direction - starting from the supplier statement balance down to the ledger balance - every adjustment above simply flips sign: additions become subtractions, and subtractions become additions.

Step 3: Prepare a reconciliation statement showing how the payables ledger balance of $11,200 reconciles to the supplier statement balance of $14,350.

(spoiler)

Kaufmano Trading Company
Payables reconciliation statement

$ $
Balance per payables ledger 11,200
Add: items recorded by supplier but not in our ledger
Goods delivered on 31 December (invoice not yet received) 1,500
Error - invoice not recorded 1,000 2,500
Add: items recorded in our ledger but not yet by the supplier
Payment in transit 500
Debit note for goods returned (not yet received by the supplier) 150 650
Balance per supplier statement 14,350

Correcting the ledger and the reported balance

Two of the four differences are genuine omissions from Kaufmano’s own records, not just timing lags on the supplier’s side: the goods delivered on 31 December and the invoice the supplier issued that Kaufmano never recorded. Both represent real purchases that happened before year-end, so they need to be posted to the ledger rather than left as reconciling items:

  • Goods delivered 31 December, invoice not yet received: debit purchases, credit trade payables, $1,500.
  • Invoice for goods delivered but not recorded: debit purchases, credit trade payables, $1,000.

Posting both entries brings the ledger balance to $11,200 + $1,500 + $1,000 = $13,700.

The $500 payment and the $150 debit note are different - Kaufmano already recorded both correctly, and it’s the supplier’s records that haven’t caught up yet. These stay as timing differences in the reconciliation rather than ledger corrections: $13,700 + $500 + $150 = $14,350, which matches the supplier’s statement.

Because the $1,500 and $1,000 items reflect real purchases that occurred before year-end, the corrected balance of $13,700 - not the supplier’s $14,350 - is the trade payables liability Kaufmano reports in its financial statements.

Key points

Payables ledger basics

  • Credit purchases: debit purchases, credit trade payables; payments: debit trade payables, credit cash; purchase returns: debit trade payables, credit purchase returns
  • Payables account normally carries credit balance = amount owed to suppliers
  • Closing credit balance reported as current liability in statement of financial position
  • Supplier statements show opening balance, invoices, payments, credit notes, closing balance

Causes of payables vs. supplier statement differences

  • Timing differences: goods in transit (supplier records before buyer receives/records) and payments in transit (buyer records before supplier processes)
  • Credit notes not yet processed: buyer issues debit note for returns/pricing errors, but supplier hasn’t yet agreed/recorded matching credit note
  • Recording errors, duplicate entries, or disputes over quantity/price/quality

Purpose of reconciliation

  • Ensures accuracy and completeness of recorded liabilities
  • Identifies omitted/understated/overstated invoices, duplicates, pricing errors, timing differences
  • Helps prevent overpayment, detect fraud, maintain supplier relationships, ensure accurate financial statements

Preparing the reconciliation

  • Steps: match ledger items to supplier statement; post unmarked supplier statement items to the ledger; correct ledger errors
  • Items recorded by supplier but missing from ledger (e.g., goods delivered but invoice not yet received, unrecorded invoice) → add to ledger balance
  • Items recorded in ledger but not yet by supplier (e.g., payment in transit, debit note not yet received by supplier) → add to ledger balance when reconciling ledger to supplier statement (direction determines sign; reversing direction flips all additions/subtractions)
  • Reconciliation statement bridges ledger balance to supplier statement balance through these adjustments

Correcting the ledger and reporting the liability

  • Distinguish genuine omissions (real purchases not yet recorded by buyer) from pure timing differences (items correctly recorded by buyer, lagging on supplier’s side)
  • Genuine omissions must be posted: debit purchases, credit trade payables, for each missing invoice/goods received
  • Timing differences (payments/debit notes already recorded by buyer) remain as reconciling items only, not ledger corrections
  • The corrected ledger balance (after posting omissions), not the supplier’s statement figure, is the amount reported as trade payables in the financial statements

More from Reconciliations

  • Bank reconciliation statement