
Bids & offers
Investors can buy and sell securities in the secondary market largely because of market makers. A market maker is a firm that makes a business out of trading securities with the public. Like a car dealership that buys cars and resells them, a market maker buys securities from investors and sells those securities to other investors.
This chapter explains how market makers use bid and ask spreads and how they operate in two major markets.
Bid & ask spreads
Bid & ask (offer) spreads are maintained by market makers in the secondary market*.
- The bid and ask are the prices the market maker is willing to trade at.
- The difference between them (the spread) is a key source of the market maker’s profit.
*Securities are originally sold in the primary market by issuers, then are traded in the secondary market by investors.
The bid is the price the firm is willing to buy a security at.
- The term bid is from the market maker’s perspective: the firm is “bidding” for someone to sell to them.
- Along with the bid price, the market maker also states how many shares they’re willing to buy at that price.
The ask, sometimes called the offer, is the price the firm is willing to sell a security at.
- The term ask is also from the market maker’s perspective: the firm is “asking” a price in hopes that someone will buy.
- Along with the ask price, the market maker states how many shares they’re willing to sell at that price.
Here’s an example of a bid/ask:
GM stock
$40 bid / $41 ask
4x7
In this example, a market maker is quoting GM stock.
- The bid tells us the market maker is willing to buy up to 400 shares at $40.
- The ask tells us the market maker is willing to sell up to 700 shares at $41.
When a market maker publishes a quote, the size is shown in round lots. The “4” on the bid side means 4 round lots, or 400 shares.
The market maker’s profit comes from buying at the bid and selling at the ask. The difference between $40 and $41 is the spread. Even small spreads can add up because market makers may execute thousands of trades per day.
A $1 spread is not common for actively traded stocks. Popular stocks often have spreads measured in pennies. In an efficient market, firms can still earn substantial profits because trading volume is high and spreads are small.
An efficient market is defined as one with active trading and small spreads. As long as the market maker trades frequently with the public, small spreads can add up over the day.
There are always two sides to a trade. So far, we’ve described bid and ask from the market maker’s perspective. A customer takes the opposite side.
Here’s a summary:
Bid
- Market maker buys
- Customer sells
Ask
- Market maker sells
- Customer buys
NYSE
Functioning in some form since 1792, the New York Stock Exchange (NYSE) is the world’s largest stock exchange. The NYSE operates as an auction market, where a designated market maker (DMM) (sometimes called a specialist) facilitates trading in a stock.
Like other auctions, the DMM (acting like an auctioneer) helps bring buyers and sellers together. The DMM also trades with the public out of the DMM’s own inventory. The DMM always acts in a principal capacity*, trading for its own account. It doesn’t act in an agency capacity: the exchange’s system matches public buy and sell orders with each other automatically.
*These trade capacities are discussed in detail later in this unit. For now, assume an agency capacity involves matching buyers and sellers, while a principal transaction involves a professional trading directly with their clients.
Before 2008, this role belonged to the NYSE specialist, who could act in either capacity: as an agent matching public orders, or as a principal trading from inventory. When the NYSE replaced specialists with DMMs in 2008, the agency role was eliminated.
In practice, the DMM function is both a person on the NYSE floor and a technology-driven trading system. Modern markets move too quickly for a human to manually execute every trade, so market making relies heavily on computerized systems and algorithms that respond almost instantly to changing prices and order flow. People still oversee these systems and may step in to trade manually when needed.
Private companies are hired by the NYSE to operate as DMMs, and they assign an employee to work at the DMM post. If you want a closer look, here’s an NYSE-created YouTube video describing the role of DMMs.
There are several DMMs on the NYSE, but each listed stock is assigned to one DMM. For example, all trades of Coca-Cola stock (listed on the NYSE) are facilitated by one specific DMM.
The DMM’s primary goal is to maintain fair and orderly markets and reduce liquidity problems. In plain terms, the DMM helps ensure investors can trade at accurate market prices during normal trading hours.
One way the NYSE supports this is through its order-routing system, traditionally called the Super Display Book. When firms submit customer orders to the NYSE, most orders go through this system, which matches and executes them automatically. In 2012, the Super Display Book was updated to the modern Universal Trading Platform, but FINRA still refers to the Super Display Book as the NYSE’s system.
Limit orders that are currently “away from the market” are placed on the NYSE’s order book, known as the DMM’s book.
*Limit orders involve placing a “limit” on a transaction price. For example, a limit order to buy stock at $40 would not allow a transaction to go through unless the stock was $40 or lower. If the market price was above $40, the order would be “away from the market” and remain unfilled until the market price fell below $40. You’ll learn more about these order types later in this unit.
To see how this works, here’s a simplified example of what the DMM’s book might look like:
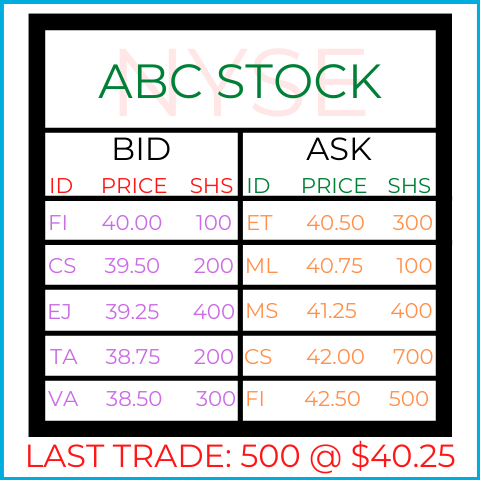
This screen shows a bid-and-ask style view of limit orders.
- The left side shows buy limit orders entered by firms on behalf of customers.
- The right side shows sell limit orders.
- These orders are “away from the market,” meaning they can’t be filled at the current market price.
The last completed trade was 500 shares at $40.25, which sits between the highest bid and the lowest ask.
- The best buy order is 100 shares at $40.00.
- The best sell order is 300 shares at $40.50.
This is the inside market: the best available prices currently on the DMM’s book. So the inside market is:
40.00 x 40.50
1 x 3
Market orders are often matched against limit orders on the book. (A market order requests execution at the next available price.)
For example, if a market order to buy 300 shares enters the system, it could be matched against the $40.50 limit order to sell 300 shares. In that case, the exchange’s system matches:
- the buyer (the market order to buy)
- with the seller (the $40.50 limit order to sell)
The DMM isn’t part of that trade; it doesn’t act as an agent for public orders.
If the DMM believes the $0.50 spread (between the highest bid and lowest ask) is too wide, the DMM can narrow it by offering shares from its own inventory at a better price than $40.50.
Assume the DMM offers 300 shares from inventory at $40.40. The market order would then buy from the DMM at $40.40, a $0.10 per share price improvement compared with buying at $40.50. This is how DMMs act in a principal capacity: they trade directly from their own inventory.
When doing this, the DMM follows the same price priority as everyone else: the best price trades first. In this example, to trade ahead of the public orders on the book, the DMM must:
- sell at a price below $40.50, or
- buy at a price above $40.00
At the same price as a public order, the DMM’s order trades alongside the public orders (called parity) rather than ahead of them. At a worse price, it waits behind them. Before 2008, the specialist had to let public orders at the same price trade first.
These examples show how the DMM supports a fair, orderly, and liquid market:
- When trading is active, public orders mostly trade with each other through the exchange’s system.
- When trading is thin or spreads are wide, the DMM trades directly with the public (principal) to improve liquidity and pricing.
Here’s a video that goes deeper into the DMM’s role with bid and ask spreads and how to approach test questions on the topic:
DMMs are also authorized to stop stock, meaning they can freeze the price of a security for a short period of time. This is most often done for floor brokers, who work on the NYSE floor.
Floor brokers represent financial firms that send trades to the NYSE.
For example, Charles Schwab could send a representative to the NYSE floor to help facilitate large customer trades (while small trades are routinely handled electronically). If Schwab receives a large order in an NYSE-listed stock, the order could be routed to a floor broker. The floor broker may then work with the DMM and other floor brokers to find the best available price.
If the DMM chooses, the DMM can quote a price to the floor broker and “lock it in” (stop the stock) for a short time. During that time, the floor broker tries to find a better price from other brokers. If no better price is found before the time expires, the broker can return to the DMM and accept the quoted price.
DMMs can only stop stock for public orders. They cannot stop stock for themselves or for a firm’s trading account.
The NYSE trades only stocks that are listed on the exchange. To be listed, issuers must meet certain standards (such as market capitalization and minimum numbers of shareholders). You don’t need to memorize the listing requirements, but it’s important to know that the NYSE generally lists large companies with actively traded stocks.
The NYSE isn’t the only exchange organized this way. A few other exchanges are modeled after the NYSE structure, including the American Stock Exchange, referred to as NYSE-MKT. There are also regional exchanges similar to the NYSE, such as the Philadelphia Stock Exchange.
A stock may trade on the NYSE and another exchange (often a regional exchange). These are called dual-listed stocks.
Any trade executed on the NYSE is a first market trade: a trade of an exchange-listed security on the exchange where it’s listed. The first market is part of the secondary market, not the primary market - recall that the primary market is where issuers sell new shares to raise capital, while the secondary market is where investors trade already-issued shares among themselves. Since a first market trade on the NYSE involves shares that are already outstanding changing hands between investors, it falls under the secondary market.