


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
CMA Part 1
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. External financial reporting decisions
2. Planning, budgeting, and forecasting
3. Performance management
4. Cost management
5. Internal control
5.1 Governance, risk and compliance
5.1.1 Internal control objectives and the COSO Framework
5.1.2 Responsibility for internal control and segregation of duties
5.1.3 Internal control limitations, risks, and deficiencies
5.1.4 Corporate governance structure and responsibilities
5.1.5 Corporate governance roles and responsibilities
5.1.6 External audit
5.1.7 The Sarbanes-oxley Act
5.1.8 Other regulatory bodies
5.2 System controls and security measures
6. Technology and analytics
Wrapping up
Achievable logoAchievable logo
5.1.4 Corporate governance structure and responsibilities
Achievable CMA Part 1
5. Internal control
5.1. Governance, risk and compliance
Our CMA Part 1 course is currently in development and is a work-in-progress.

Corporate governance structure and responsibilities

8 min read
Font
Discuss
Share
Feedback

Learning outcome statements

The learning outcome statements relevant for this section are:

  1. explain how a company’s organizational structure, policies, objectives, and goals, as well as its management philosophy and style, influence the scope and effectiveness of the control environment
  2. identify the Board of Directors’ responsibilities with respect to ensuring that the company is operated in the best interest of shareholders
  3. identify the hierarchy of corporate governance (i.e., articles of incorporation, bylaws, policies, and procedures)
  4. demonstrate an understanding of corporate governance, including rights and responsibilities of the CEO, the CFO, the Board of Directors, the audit committee, managers, and other stakeholders; and the procedures for making corporate decisions

What is corporate governance

Definitions
Corporate governance
The system of rules, practices, processes, and organizational structures that guide and control the way a company is directed and managed.

Corporate governance establishes the framework for achieving a company’s objectives, ensuring accountability, fairness, and transparency in the relationship among a company’s management, board of directors, shareholders, and other stakeholders.

Influence of organizational attributes on the control environment

The effectiveness of a company’s control environment is significantly shaped by various elements of its governance structure. These include the company’s organizational structure, management philosophy, operating style, and strategic objectives. A company with clearly defined goals, consistent values, and an ethical culture is more likely to establish a robust control environment. For example, a decentralized structure may promote innovation but could also increase risks if not properly monitored. Similarly, a management philosophy that values aggressive growth over regulatory compliance may undermine the control environment.

Personnel policies, accountability mechanisms, and communication protocols also reinforce governance by embedding expectations of integrity and performance throughout the organization.

The board of directors and the agency perspective

Central to corporate governance is the role of the Board of Directors, which acts as a fiduciary for shareholders. The Board is responsible for overseeing management’s actions, guiding corporate strategy, and ensuring the company operates in the best interests of its owners. This aligns with agency theory, which highlights the inherent tension between the interests of shareholders (principals) and management (agents). Without proper oversight, managers may pursue personal goals at the expense of shareholders’ wealth.

To mitigate agency risks, the Board can implement a variety of governance mechanisms. These include establishing independent audit and compensation committees, separating the roles of CEO and Chairperson, and tying executive compensation to long-term performance metrics such as return on equity or total shareholder return.

Policies that promote transparency (e.g., mandatory disclosure of related party transactions and whistleblower protection) also strengthen accountability. Regular board evaluations, director training, and a strong code of ethics further ensure that management actions align with shareholder interests. The Board must establish clear governance policies, monitor executive performance, set ethical standards, and ensure transparent reporting. Independence, competence, and active engagement are critical qualities that empower the Board to fulfill its governance responsibilities effectively.

The specific rights and responsibilities of the CEO, CFO, audit committee, and other stakeholders are covered in detail in the next chapter, Corporate governance roles and responsibilities.

The hierarchy of corporate governance

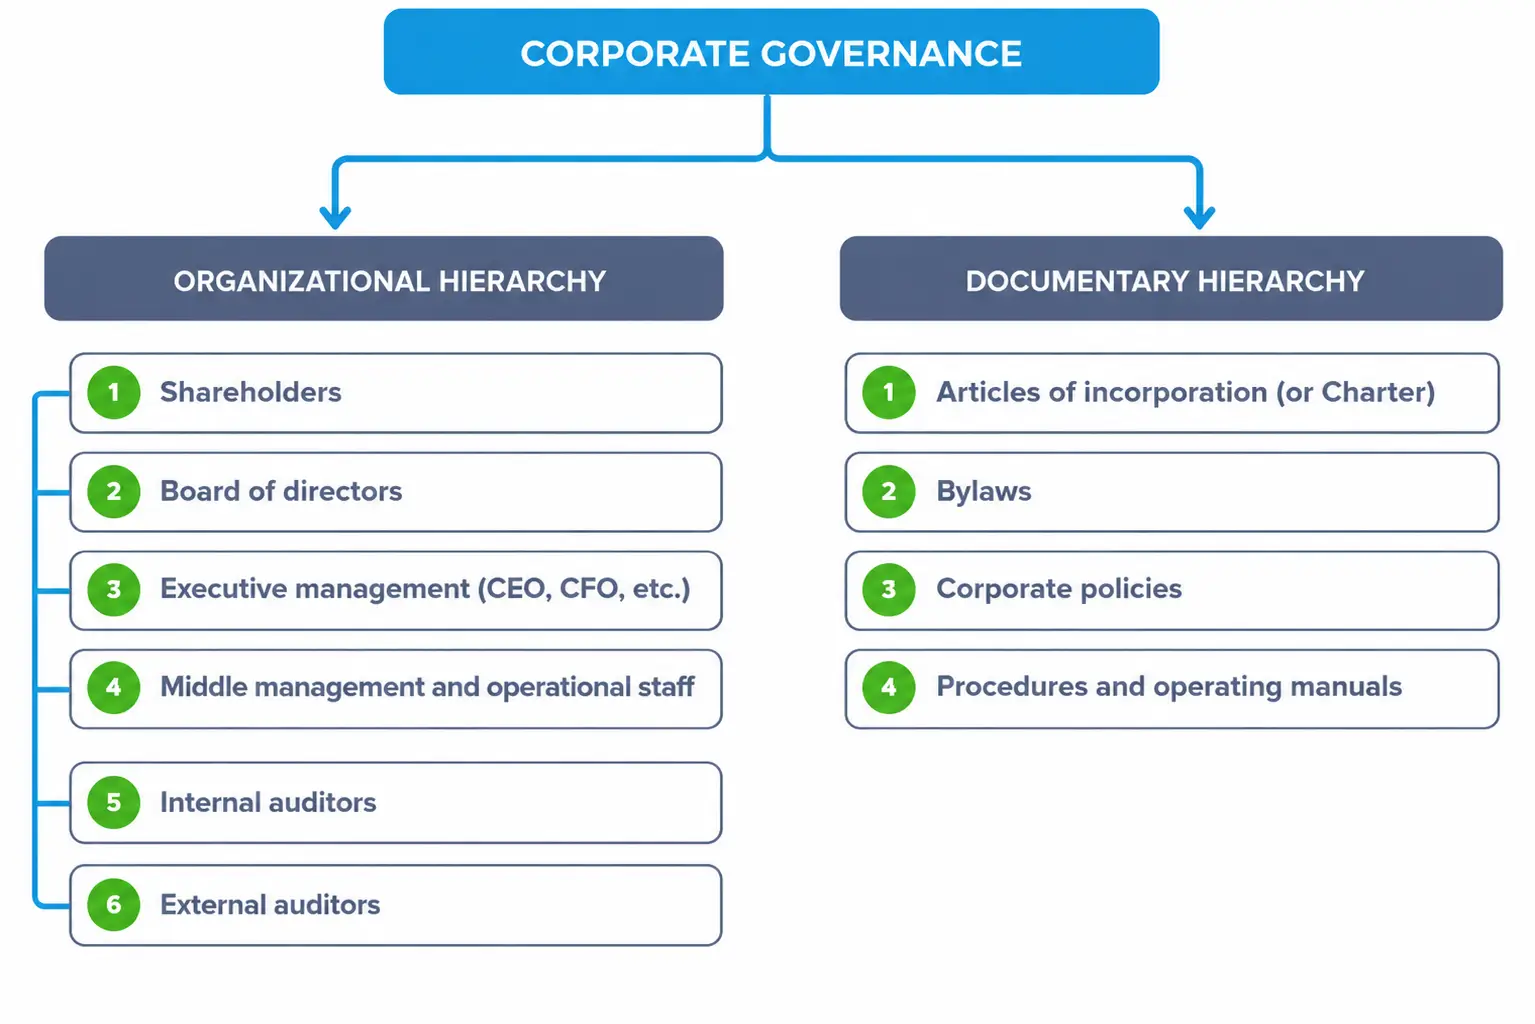
Corporate governance can be understood through two interrelated hierarchies:

  1. the organizational (stakeholder) hierarchy and
  2. the documentary (legal and procedural) hierarchy.

Each plays a distinct but complementary role in shaping how governance is established, maintained, and enforced within an entity.

Showing organizational and documentary hierarchies branching from corporate governance.
Corporate Governance Hierarchy
Achievable

Organizational hierarchy of governance

This hierarchy defines the distribution of authority and oversight roles among different stakeholders within a company:

  1. Shareholders: As the owners of the company, shareholders hold ultimate authority and typically exercise their power through voting rights at general meetings. They appoint members of the Board of Directors and can influence key strategic decisions through resolutions and shareholder activism.
  2. Board of directors: Elected by shareholders, the Board is responsible for setting the company’s strategic direction, ensuring effective risk management, and overseeing executive performance. The Board operates through various committees, such as audit, risk, and compensation committees, which help in specialized oversight.
  3. Executive management (e.g., CEO, CFO): Executives are accountable for the day-to-day management of the company. They translate the Board’s strategic vision into operational plans, implement policies, and manage performance. Executives also play a central role in promoting corporate culture and values.
  4. Middle management and operational staff: These individuals execute corporate policies and procedures within their functional areas. They are the front line of governance, ensuring that activities align with organizational standards and that risks are reported and addressed appropriately.

This hierarchy ensures that checks and balances are embedded within the organizational structure: authority is delegated downward from shareholders to the Board to management, while accountability flows upward, with management answerable to the Board and the Board answerable to shareholders.

Other functions independent from the ones identified above are the internal and external audit functions:

  • Internal auditors: Operating independently from management, internal auditors assess the effectiveness of internal controls, risk management, and governance processes. They report directly to the audit committee or Board, providing assurance and recommendations for improvement.
  • External auditors: Appointed, compensated, and overseen by the audit committee (in public companies, often with shareholder ratification), external auditors offer an independent assessment of the company’s financial statements and, in some cases, internal controls. They serve as a critical external check on financial transparency and governance integrity.

Pitfall: internal audit reports functionally to the audit committee or Board, which is what preserves its independence, but administratively to management, which handles day-to-day matters like budget and staffing. Mixing up these two reporting lines is a common point of confusion.

Documentary hierarchy of governance

The second hierarchy consists of the formal documentation that governs how decisions are made and operations are conducted. These sources of authority typically follow this order:

  1. Articles of incorporation (or Charter): This foundational legal document formally creates the corporation, outlines its purpose, and defines its basic legal framework, including the rights of shareholders and powers of directors.
  2. Bylaws: These internal rules provide more detailed guidance on the governance structure, such as the frequency and procedures of board meetings, voting processes, and the roles of corporate officers.
  3. Corporate policies: These articulate the organization’s standards and expectations in areas such as ethics, compliance, risk management, financial reporting, and information security. Policies guide consistent decision-making across the organization.
  4. Procedures and operating manuals: These provide step-by-step instructions for implementing corporate policies in daily operations. They ensure that employees understand their responsibilities and execute tasks in line with governance standards.

Each level must be consistent with, and is subordinate to, the levels above it: bylaws cannot contradict the articles of incorporation, and policies and procedures cannot contradict the bylaws. Where a conflict arises, the higher-level document prevails.

For example, if the bylaws require board approval for any related-party transaction, a policy that lets a single officer approve such transactions without board sign-off is invalid, since it conflicts with the higher-level document.

Procedures for making corporate decisions

Corporate decision-making follows a hierarchical and procedural structure guided by governance documents, regulatory requirements, and industry best practices.

Strategic decisions are typically proposed by management and reviewed and approved by the Board of Directors. Operational decisions fall under the domain of executives and managers, within the boundaries set by board-approved policies.

Decision-making processes often include:

  1. Proposal development by relevant departments
  2. Internal review by management and functional committees
  3. Presentation to the board or appropriate committee for approval
  4. Documentation of decisions in meeting minutes and policy updates

In the United States, these procedures are influenced by legal and regulatory frameworks, including the Sarbanes-Oxley Act of 2002 (SOX) and Securities and Exchange Commission (SEC) rules, which promote transparency, accountability, and sound internal controls in public companies. These regulations emphasize the need for formalized decision-making structures and adequate documentation to support corporate governance and protect stakeholder interests.

Corporate governance basics

  • Definition: system of rules, practices, processes, structures guiding/controlling company direction and management
  • Goals: accountability, fairness, transparency among management, board, shareholders, stakeholders
  • Control environment effectiveness shaped by: organizational structure, management philosophy/style, objectives, personnel policies, communication protocols
    • Decentralization can boost innovation but raise unmonitored risk
    • Growth-focused philosophy over compliance can weaken controls

Board of Directors & agency theory

  • Board = fiduciary for shareholders; oversees management, guides strategy, ensures alignment with shareholder interests
  • Agency theory: tension between shareholders (principals) and management (agents) who may pursue self-interest
  • Mitigation tools: independent audit/compensation committees, separate CEO/Chair roles, performance-tied executive pay, transparency policies (disclosure, whistleblower protection), board evaluations, code of ethics
  • Key Board qualities: independence, competence, active engagement

Organizational (stakeholder) hierarchy

  • Flow of authority downward, accountability upward:
    • Shareholders (ultimate owners, vote/elect board)
    • Board of Directors (strategy, oversight, committees)
    • Executive management/CEO, CFO (translate strategy into operations)
    • Middle management/staff (execute policies, front-line governance)
  • Internal auditors: assess controls/risk/governance; report functionally to audit committee/Board (independence), administratively to management (budget/staffing) — common exam pitfall
  • External auditors: independent check on financials, appointed/overseen by audit committee

Documentary (legal/procedural) hierarchy

  • Order of authority (each level subordinate to the one above; higher document prevails in conflicts):
    1. Articles of Incorporation/Charter – creates corporation, defines purpose/rights
    2. Bylaws – governance structure details (meetings, voting, officer roles)
    3. Corporate policies – standards for ethics, compliance, risk, reporting
    4. Procedures/operating manuals – step-by-step implementation guidance
  • Example: policy conflicting with bylaws (e.g., bypassing required board approval) is invalid

Corporate decision-making procedures

  • Strategic decisions: proposed by management, approved by Board
  • Operational decisions: handled by executives/managers within board-approved policy limits
  • Typical process: proposal development → internal review → board/committee approval → documentation (minutes, policy updates)
  • U.S. regulatory influence: Sarbanes-Oxley Act (SOX) and SEC rules require formalized decision structures, strong internal controls, and documentation to protect stakeholders

Sign up for free to take 13 quiz questions on this topic

Previous
Next  | 5.1.5 Corporate governance roles and responsibilities
All rights reserved ©2016 - 2026 Achievable, Inc.

Corporate governance structure and responsibilities

Learning outcome statements

The learning outcome statements relevant for this section are:

  1. explain how a company’s organizational structure, policies, objectives, and goals, as well as its management philosophy and style, influence the scope and effectiveness of the control environment
  2. identify the Board of Directors’ responsibilities with respect to ensuring that the company is operated in the best interest of shareholders
  3. identify the hierarchy of corporate governance (i.e., articles of incorporation, bylaws, policies, and procedures)
  4. demonstrate an understanding of corporate governance, including rights and responsibilities of the CEO, the CFO, the Board of Directors, the audit committee, managers, and other stakeholders; and the procedures for making corporate decisions

What is corporate governance

Definitions
Corporate governance
The system of rules, practices, processes, and organizational structures that guide and control the way a company is directed and managed.

Corporate governance establishes the framework for achieving a company’s objectives, ensuring accountability, fairness, and transparency in the relationship among a company’s management, board of directors, shareholders, and other stakeholders.

Influence of organizational attributes on the control environment

The effectiveness of a company’s control environment is significantly shaped by various elements of its governance structure. These include the company’s organizational structure, management philosophy, operating style, and strategic objectives. A company with clearly defined goals, consistent values, and an ethical culture is more likely to establish a robust control environment. For example, a decentralized structure may promote innovation but could also increase risks if not properly monitored. Similarly, a management philosophy that values aggressive growth over regulatory compliance may undermine the control environment.

Personnel policies, accountability mechanisms, and communication protocols also reinforce governance by embedding expectations of integrity and performance throughout the organization.

The board of directors and the agency perspective

Central to corporate governance is the role of the Board of Directors, which acts as a fiduciary for shareholders. The Board is responsible for overseeing management’s actions, guiding corporate strategy, and ensuring the company operates in the best interests of its owners. This aligns with agency theory, which highlights the inherent tension between the interests of shareholders (principals) and management (agents). Without proper oversight, managers may pursue personal goals at the expense of shareholders’ wealth.

To mitigate agency risks, the Board can implement a variety of governance mechanisms. These include establishing independent audit and compensation committees, separating the roles of CEO and Chairperson, and tying executive compensation to long-term performance metrics such as return on equity or total shareholder return.

Policies that promote transparency (e.g., mandatory disclosure of related party transactions and whistleblower protection) also strengthen accountability. Regular board evaluations, director training, and a strong code of ethics further ensure that management actions align with shareholder interests. The Board must establish clear governance policies, monitor executive performance, set ethical standards, and ensure transparent reporting. Independence, competence, and active engagement are critical qualities that empower the Board to fulfill its governance responsibilities effectively.

The specific rights and responsibilities of the CEO, CFO, audit committee, and other stakeholders are covered in detail in the next chapter, Corporate governance roles and responsibilities.

The hierarchy of corporate governance

Corporate governance can be understood through two interrelated hierarchies:

  1. the organizational (stakeholder) hierarchy and
  2. the documentary (legal and procedural) hierarchy.

Each plays a distinct but complementary role in shaping how governance is established, maintained, and enforced within an entity.

Organizational hierarchy of governance

This hierarchy defines the distribution of authority and oversight roles among different stakeholders within a company:

  1. Shareholders: As the owners of the company, shareholders hold ultimate authority and typically exercise their power through voting rights at general meetings. They appoint members of the Board of Directors and can influence key strategic decisions through resolutions and shareholder activism.
  2. Board of directors: Elected by shareholders, the Board is responsible for setting the company’s strategic direction, ensuring effective risk management, and overseeing executive performance. The Board operates through various committees, such as audit, risk, and compensation committees, which help in specialized oversight.
  3. Executive management (e.g., CEO, CFO): Executives are accountable for the day-to-day management of the company. They translate the Board’s strategic vision into operational plans, implement policies, and manage performance. Executives also play a central role in promoting corporate culture and values.
  4. Middle management and operational staff: These individuals execute corporate policies and procedures within their functional areas. They are the front line of governance, ensuring that activities align with organizational standards and that risks are reported and addressed appropriately.

This hierarchy ensures that checks and balances are embedded within the organizational structure: authority is delegated downward from shareholders to the Board to management, while accountability flows upward, with management answerable to the Board and the Board answerable to shareholders.

Other functions independent from the ones identified above are the internal and external audit functions:

  • Internal auditors: Operating independently from management, internal auditors assess the effectiveness of internal controls, risk management, and governance processes. They report directly to the audit committee or Board, providing assurance and recommendations for improvement.
  • External auditors: Appointed, compensated, and overseen by the audit committee (in public companies, often with shareholder ratification), external auditors offer an independent assessment of the company’s financial statements and, in some cases, internal controls. They serve as a critical external check on financial transparency and governance integrity.

Pitfall: internal audit reports functionally to the audit committee or Board, which is what preserves its independence, but administratively to management, which handles day-to-day matters like budget and staffing. Mixing up these two reporting lines is a common point of confusion.

Documentary hierarchy of governance

The second hierarchy consists of the formal documentation that governs how decisions are made and operations are conducted. These sources of authority typically follow this order:

  1. Articles of incorporation (or Charter): This foundational legal document formally creates the corporation, outlines its purpose, and defines its basic legal framework, including the rights of shareholders and powers of directors.
  2. Bylaws: These internal rules provide more detailed guidance on the governance structure, such as the frequency and procedures of board meetings, voting processes, and the roles of corporate officers.
  3. Corporate policies: These articulate the organization’s standards and expectations in areas such as ethics, compliance, risk management, financial reporting, and information security. Policies guide consistent decision-making across the organization.
  4. Procedures and operating manuals: These provide step-by-step instructions for implementing corporate policies in daily operations. They ensure that employees understand their responsibilities and execute tasks in line with governance standards.

Each level must be consistent with, and is subordinate to, the levels above it: bylaws cannot contradict the articles of incorporation, and policies and procedures cannot contradict the bylaws. Where a conflict arises, the higher-level document prevails.

For example, if the bylaws require board approval for any related-party transaction, a policy that lets a single officer approve such transactions without board sign-off is invalid, since it conflicts with the higher-level document.

Procedures for making corporate decisions

Corporate decision-making follows a hierarchical and procedural structure guided by governance documents, regulatory requirements, and industry best practices.

Strategic decisions are typically proposed by management and reviewed and approved by the Board of Directors. Operational decisions fall under the domain of executives and managers, within the boundaries set by board-approved policies.

Decision-making processes often include:

  1. Proposal development by relevant departments
  2. Internal review by management and functional committees
  3. Presentation to the board or appropriate committee for approval
  4. Documentation of decisions in meeting minutes and policy updates

In the United States, these procedures are influenced by legal and regulatory frameworks, including the Sarbanes-Oxley Act of 2002 (SOX) and Securities and Exchange Commission (SEC) rules, which promote transparency, accountability, and sound internal controls in public companies. These regulations emphasize the need for formalized decision-making structures and adequate documentation to support corporate governance and protect stakeholder interests.

Key points

Corporate governance basics

  • Definition: system of rules, practices, processes, structures guiding/controlling company direction and management
  • Goals: accountability, fairness, transparency among management, board, shareholders, stakeholders
  • Control environment effectiveness shaped by: organizational structure, management philosophy/style, objectives, personnel policies, communication protocols
    • Decentralization can boost innovation but raise unmonitored risk
    • Growth-focused philosophy over compliance can weaken controls

Board of Directors & agency theory

  • Board = fiduciary for shareholders; oversees management, guides strategy, ensures alignment with shareholder interests
  • Agency theory: tension between shareholders (principals) and management (agents) who may pursue self-interest
  • Mitigation tools: independent audit/compensation committees, separate CEO/Chair roles, performance-tied executive pay, transparency policies (disclosure, whistleblower protection), board evaluations, code of ethics
  • Key Board qualities: independence, competence, active engagement

Organizational (stakeholder) hierarchy

  • Flow of authority downward, accountability upward:
    • Shareholders (ultimate owners, vote/elect board)
    • Board of Directors (strategy, oversight, committees)
    • Executive management/CEO, CFO (translate strategy into operations)
    • Middle management/staff (execute policies, front-line governance)
  • Internal auditors: assess controls/risk/governance; report functionally to audit committee/Board (independence), administratively to management (budget/staffing) — common exam pitfall
  • External auditors: independent check on financials, appointed/overseen by audit committee

Documentary (legal/procedural) hierarchy

  • Order of authority (each level subordinate to the one above; higher document prevails in conflicts):
    1. Articles of Incorporation/Charter – creates corporation, defines purpose/rights
    2. Bylaws – governance structure details (meetings, voting, officer roles)
    3. Corporate policies – standards for ethics, compliance, risk, reporting
    4. Procedures/operating manuals – step-by-step implementation guidance
  • Example: policy conflicting with bylaws (e.g., bypassing required board approval) is invalid

Corporate decision-making procedures

  • Strategic decisions: proposed by management, approved by Board
  • Operational decisions: handled by executives/managers within board-approved policy limits
  • Typical process: proposal development → internal review → board/committee approval → documentation (minutes, policy updates)
  • U.S. regulatory influence: Sarbanes-Oxley Act (SOX) and SEC rules require formalized decision structures, strong internal controls, and documentation to protect stakeholders

More from Governance, risk and compliance

  • Internal control objectives and the COSO Framework
  • Responsibility for internal control and segregation of duties
  • Internal control limitations, risks, and deficiencies
  • Corporate governance roles and responsibilities
  • External audit