


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
CMA Part 1
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. External financial reporting decisions
2. Planning, budgeting, and forecasting
3. Performance management
4. Cost management
5. Internal control
6. Technology and analytics
Wrapping up
Achievable logoAchievable logo
1.2.5.2 Initial recognition and subsequent measurement
Achievable CMA Part 1
1. External financial reporting decisions
1.2. Financial transactions
1.2.5. Intangible assets
Our CMA Part 1 course is currently in development and is a work-in-progress.

Initial recognition and subsequent measurement

5 min read
Font
Discuss
Share
Feedback

This chapter covers how intangible assets are initially recorded and later measured (amortization and the definite- vs. indefinite-life distinction). That groundwork is needed for impairment, which is covered in a later chapter.

Just like property, plant and equipment, the general accounting for intangible assets can be broken down into:

  • Initial recognition
  • Subsequent measurement, which includes:
    • Periodic amortization, if applicable
    • Impairment

Goodwill is discussed separately from other types of intangibles because, despite being an intangible asset itself, the requirements for goodwill are covered by a separate subtopic of the Codification (ASC 350-20), while other intangibles fall under ASC 350-30.

Initial recognition of intangible assets

The initial recognition of intangible assets mirrors that of property, plant and equipment discussed in the previous section. They are initially recorded at acquisition cost plus incidental costs necessary to make the asset ready for use. This may vary depending on the type of asset being accounted for so initial recognition accounting is best discussed per type of intangible asset. This discussion is combined in the table presented in the next section.

Watch out: Purchased intangibles and the legal fees to obtain them are capitalized. Under U.S. GAAP, costs to internally develop an intangible - including R&D - are expensed as incurred, not capitalized. IFRS differs: qualifying development costs can be capitalized, and a revaluation model is allowed. These differences are covered in a later chapter.

Subsequent measurement of intangible assets

The subsequent measurement of intangible assets depends on whether the asset has a definite life or an indefinite life.

  • Definite-life intangible assets are carried at cost less accumulated amortization and impairment.

  • Indefinite-life intangible assets are carried at cost less impairment only, since they are not amortized until their useful life becomes finite.

An intangible asset is considered to have an indefinite life when there are no legal, regulatory, contractual, competitive, or economic factors that limit its continued use. However, indefinite does not mean infinite. If circumstances change such that the useful life can be determined, the company must begin amortizing the asset accordingly.

In practice, amortization methods may vary depending on the type of intangible asset, but the accounting treatment is conceptually the same as depreciation: the expense is systematically allocated and recorded through a journal entry that mirrors depreciation charges.

Watch out: A useful-life reassessment is a prospective change in estimate - prior periods aren’t restated.

Example: reassessing useful life

A trademark’s $50,000 carrying value is reassessed from an indefinite life to a definite 5-year life.

Answer: First, test the trademark for impairment (ASC 350-30-35-17). Then amortize the post-test carrying value prospectively: $50,000÷5=$10,000 per year; prior periods aren’t restated.

Cost, useful life and amortization

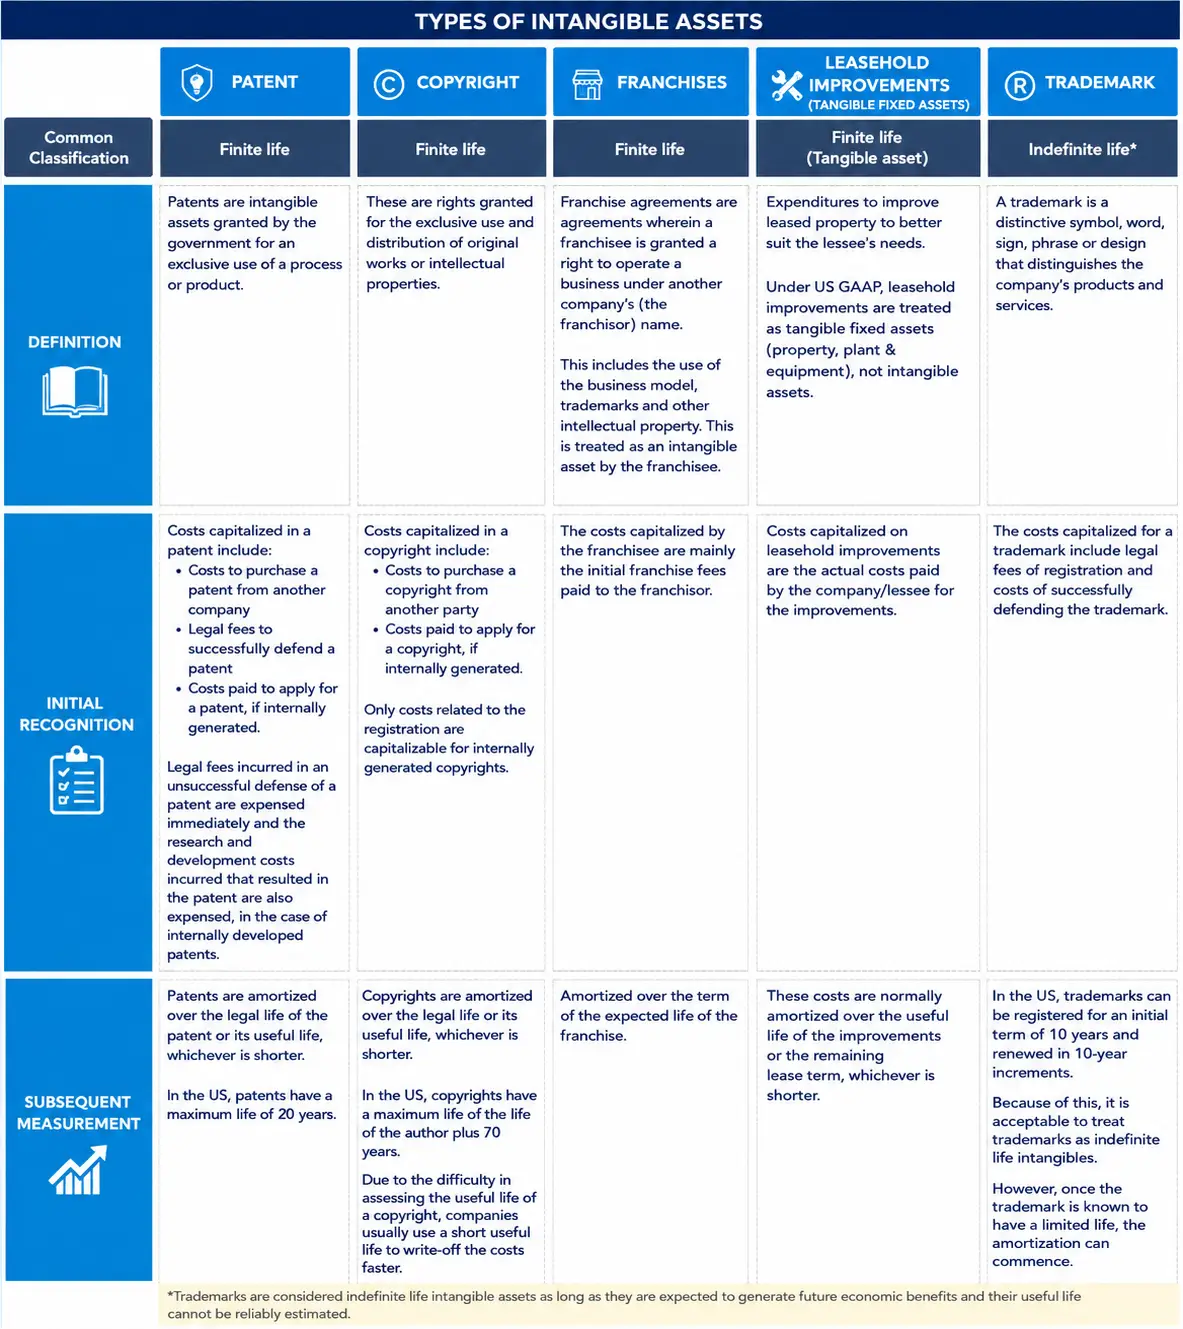
The table below summarizes common intangible asset types, their capitalized costs, useful life, and amortization treatment.

Intangible asset Costs capitalized Useful life Amortization
Patent Purchase price and legal fees to obtain it; R&D to develop it is expensed Definite - lesser of legal life (20 yrs) or useful life Straight-line over useful life
Trademark / trade name Purchase price or registration fees Often indefinite - renewable indefinitely Not amortized; impairment-tested
Copyright Purchase price plus registration and legal fees; R&D to develop it is expensed Definite - lesser of legal life (author’s life + 70 years) or useful life Straight-line over useful life
Franchise / license Initial franchise fee and directly related costs Definite if term-limited; indefinite if perpetual Amortized over the term if definite; not amortized (impairment-tested) if indefinite
Common types of intangible assets.
Types of intangible assets comparison
Achievable

Journal entry

This entry reduces the asset’s carrying value over time while recognizing the expense in the income statement.

Account Debit Credit Financial statement element
Amortization expense XXX Expense
Accumulated amortization - intangible asset XXX Contra-asset
To record amortization of intangible asset

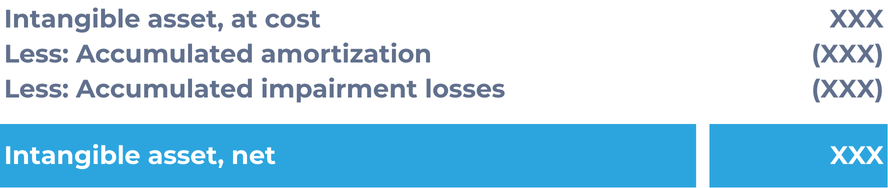
The journal entry typically is credited to the contra-asset account because we need to track the cost of the intangible asset. Effectively, the presentation in the balance sheet is as follows:

Balance sheet showing intangible asset at cost less accumulated amortization equals net carrying value
Intangible asset presentation in the balance sheet
Achievable

Overview of intangible asset accounting

  • Same two-stage framework as PP&E: initial recognition, then subsequent measurement (amortization + impairment)
  • Goodwill treated separately (ASC 350-20) from other intangibles (ASC 350-30)
  • Impairment details covered in a later chapter

Initial recognition

  • Recorded at acquisition cost plus incidental costs to make asset ready for use
  • Purchased intangibles and related legal fees: capitalized
  • U.S. GAAP: internally developed costs (including R&D) expensed as incurred, not capitalized
  • IFRS differs: qualifying development costs can be capitalized; revaluation model allowed

Subsequent measurement: definite vs. indefinite life

  • Definite-life intangibles: carried at cost less accumulated amortization and impairment
  • Indefinite-life intangibles: carried at cost less impairment only (no amortization)
  • Indefinite life = no legal/regulatory/contractual/competitive/economic limits on use (indefinite ≠ infinite)
  • If life becomes determinable, asset must begin amortizing
  • Useful-life reassessment = prospective change in estimate (no restatement of prior periods)
    • First test for impairment, then amortize remaining carrying value over new useful life going forward

Common intangible asset types (cost, life, amortization patterns)

  • Capitalized costs generally = purchase price/fees to acquire; self-developed R&D always expensed
  • Life classification varies: patents/copyrights are definite (tied to legal life or useful life, whichever shorter); trademarks often indefinite (renewable); franchises/licenses depend on contract term (definite if term-limited, indefinite if perpetual)
  • Amortization: straight-line over useful life for definite-life assets (e.g., patents over lesser of 20-year legal life or useful life; copyrights over lesser of author’s life+70 years or useful life); indefinite-life assets not amortized, only impairment-tested

Journal entry and presentation

  • Entry: debit Amortization Expense, credit Accumulated Amortization (contra-asset)
  • Mirrors depreciation mechanics for PP&E
  • Balance sheet shows intangible asset at cost less accumulated amortization = net carrying value

Sign up for free to take 12 quiz questions on this topic

Previous
Next  | 1.2.5.3 Impairment of intangible assets
All rights reserved ©2016 - 2026 Achievable, Inc.

Initial recognition and subsequent measurement

This chapter covers how intangible assets are initially recorded and later measured (amortization and the definite- vs. indefinite-life distinction). That groundwork is needed for impairment, which is covered in a later chapter.

Just like property, plant and equipment, the general accounting for intangible assets can be broken down into:

  • Initial recognition
  • Subsequent measurement, which includes:
    • Periodic amortization, if applicable
    • Impairment

Goodwill is discussed separately from other types of intangibles because, despite being an intangible asset itself, the requirements for goodwill are covered by a separate subtopic of the Codification (ASC 350-20), while other intangibles fall under ASC 350-30.

Initial recognition of intangible assets

The initial recognition of intangible assets mirrors that of property, plant and equipment discussed in the previous section. They are initially recorded at acquisition cost plus incidental costs necessary to make the asset ready for use. This may vary depending on the type of asset being accounted for so initial recognition accounting is best discussed per type of intangible asset. This discussion is combined in the table presented in the next section.

Watch out: Purchased intangibles and the legal fees to obtain them are capitalized. Under U.S. GAAP, costs to internally develop an intangible - including R&D - are expensed as incurred, not capitalized. IFRS differs: qualifying development costs can be capitalized, and a revaluation model is allowed. These differences are covered in a later chapter.

Subsequent measurement of intangible assets

The subsequent measurement of intangible assets depends on whether the asset has a definite life or an indefinite life.

  • Definite-life intangible assets are carried at cost less accumulated amortization and impairment.

  • Indefinite-life intangible assets are carried at cost less impairment only, since they are not amortized until their useful life becomes finite.

An intangible asset is considered to have an indefinite life when there are no legal, regulatory, contractual, competitive, or economic factors that limit its continued use. However, indefinite does not mean infinite. If circumstances change such that the useful life can be determined, the company must begin amortizing the asset accordingly.

In practice, amortization methods may vary depending on the type of intangible asset, but the accounting treatment is conceptually the same as depreciation: the expense is systematically allocated and recorded through a journal entry that mirrors depreciation charges.

Watch out: A useful-life reassessment is a prospective change in estimate - prior periods aren’t restated.

Example: reassessing useful life

A trademark’s $50,000 carrying value is reassessed from an indefinite life to a definite 5-year life.

Answer: First, test the trademark for impairment (ASC 350-30-35-17). Then amortize the post-test carrying value prospectively: $50,000÷5=$10,000 per year; prior periods aren’t restated.

Cost, useful life and amortization

The table below summarizes common intangible asset types, their capitalized costs, useful life, and amortization treatment.

Intangible asset Costs capitalized Useful life Amortization
Patent Purchase price and legal fees to obtain it; R&D to develop it is expensed Definite - lesser of legal life (20 yrs) or useful life Straight-line over useful life
Trademark / trade name Purchase price or registration fees Often indefinite - renewable indefinitely Not amortized; impairment-tested
Copyright Purchase price plus registration and legal fees; R&D to develop it is expensed Definite - lesser of legal life (author’s life + 70 years) or useful life Straight-line over useful life
Franchise / license Initial franchise fee and directly related costs Definite if term-limited; indefinite if perpetual Amortized over the term if definite; not amortized (impairment-tested) if indefinite

Journal entry

This entry reduces the asset’s carrying value over time while recognizing the expense in the income statement.

Account Debit Credit Financial statement element
Amortization expense XXX Expense
Accumulated amortization - intangible asset XXX Contra-asset
To record amortization of intangible asset

The journal entry typically is credited to the contra-asset account because we need to track the cost of the intangible asset. Effectively, the presentation in the balance sheet is as follows:

Key points

Overview of intangible asset accounting

  • Same two-stage framework as PP&E: initial recognition, then subsequent measurement (amortization + impairment)
  • Goodwill treated separately (ASC 350-20) from other intangibles (ASC 350-30)
  • Impairment details covered in a later chapter

Initial recognition

  • Recorded at acquisition cost plus incidental costs to make asset ready for use
  • Purchased intangibles and related legal fees: capitalized
  • U.S. GAAP: internally developed costs (including R&D) expensed as incurred, not capitalized
  • IFRS differs: qualifying development costs can be capitalized; revaluation model allowed

Subsequent measurement: definite vs. indefinite life

  • Definite-life intangibles: carried at cost less accumulated amortization and impairment
  • Indefinite-life intangibles: carried at cost less impairment only (no amortization)
  • Indefinite life = no legal/regulatory/contractual/competitive/economic limits on use (indefinite ≠ infinite)
  • If life becomes determinable, asset must begin amortizing
  • Useful-life reassessment = prospective change in estimate (no restatement of prior periods)
    • First test for impairment, then amortize remaining carrying value over new useful life going forward

Common intangible asset types (cost, life, amortization patterns)

  • Capitalized costs generally = purchase price/fees to acquire; self-developed R&D always expensed
  • Life classification varies: patents/copyrights are definite (tied to legal life or useful life, whichever shorter); trademarks often indefinite (renewable); franchises/licenses depend on contract term (definite if term-limited, indefinite if perpetual)
  • Amortization: straight-line over useful life for definite-life assets (e.g., patents over lesser of 20-year legal life or useful life; copyrights over lesser of author’s life+70 years or useful life); indefinite-life assets not amortized, only impairment-tested

Journal entry and presentation

  • Entry: debit Amortization Expense, credit Accumulated Amortization (contra-asset)
  • Mirrors depreciation mechanics for PP&E
  • Balance sheet shows intangible asset at cost less accumulated amortization = net carrying value

More from Intangible assets

  • Learning outcomes
  • Impairment of intangible assets
  • Goodwill