



Inventory ownership and capitalization
Inventories are assets in the balance sheet because:
- they are resources owned by an entity; and
- they are expected to provide future economic benefits through sale or, for a manufacturer, use in production, in the ordinary course of business.
Inventories are a unique type of asset because they appear as an asset in the balance sheet, but also as an input to determine the cost of goods sold in the income statement. This is why the major objective in the accounting for inventories is the proper determination of income by matching the revenues to the costs related to those items sold. If the inventory amounts are misstated, it has a corresponding impact to the cost of goods sold and eventually to the net income. For example, an overstated ending inventory understates cost of goods sold and overstates net income - an error that reverses in the following period.
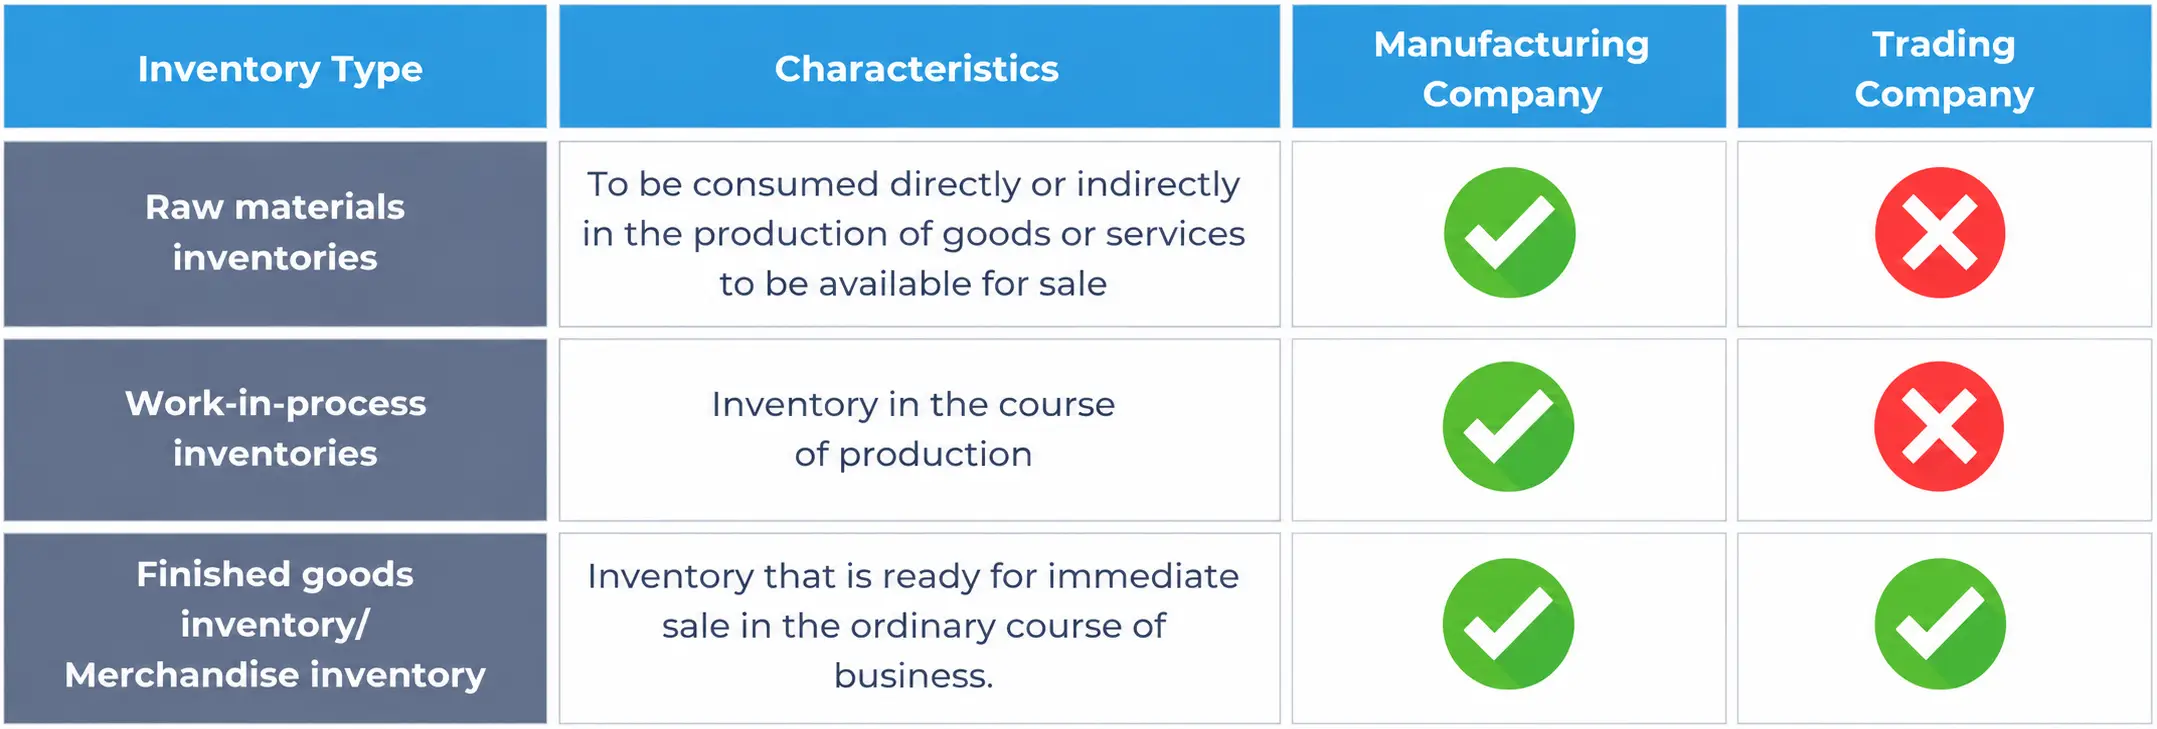
Below is a summary of the characteristics of inventories as per ASC 330, summarized by the nature of the operations. This chapter follows US GAAP; differences between US GAAP and IFRS inventory accounting are covered in a later chapter, US GAAP versus IFRS.
The ownership rules below are illustrated for a trading company’s finished goods, but the cost rules also apply to manufacturers. Other inventory types and manufacturing inventory flows are covered in a later chapter of CMA Part 1.
What goods to include in inventory
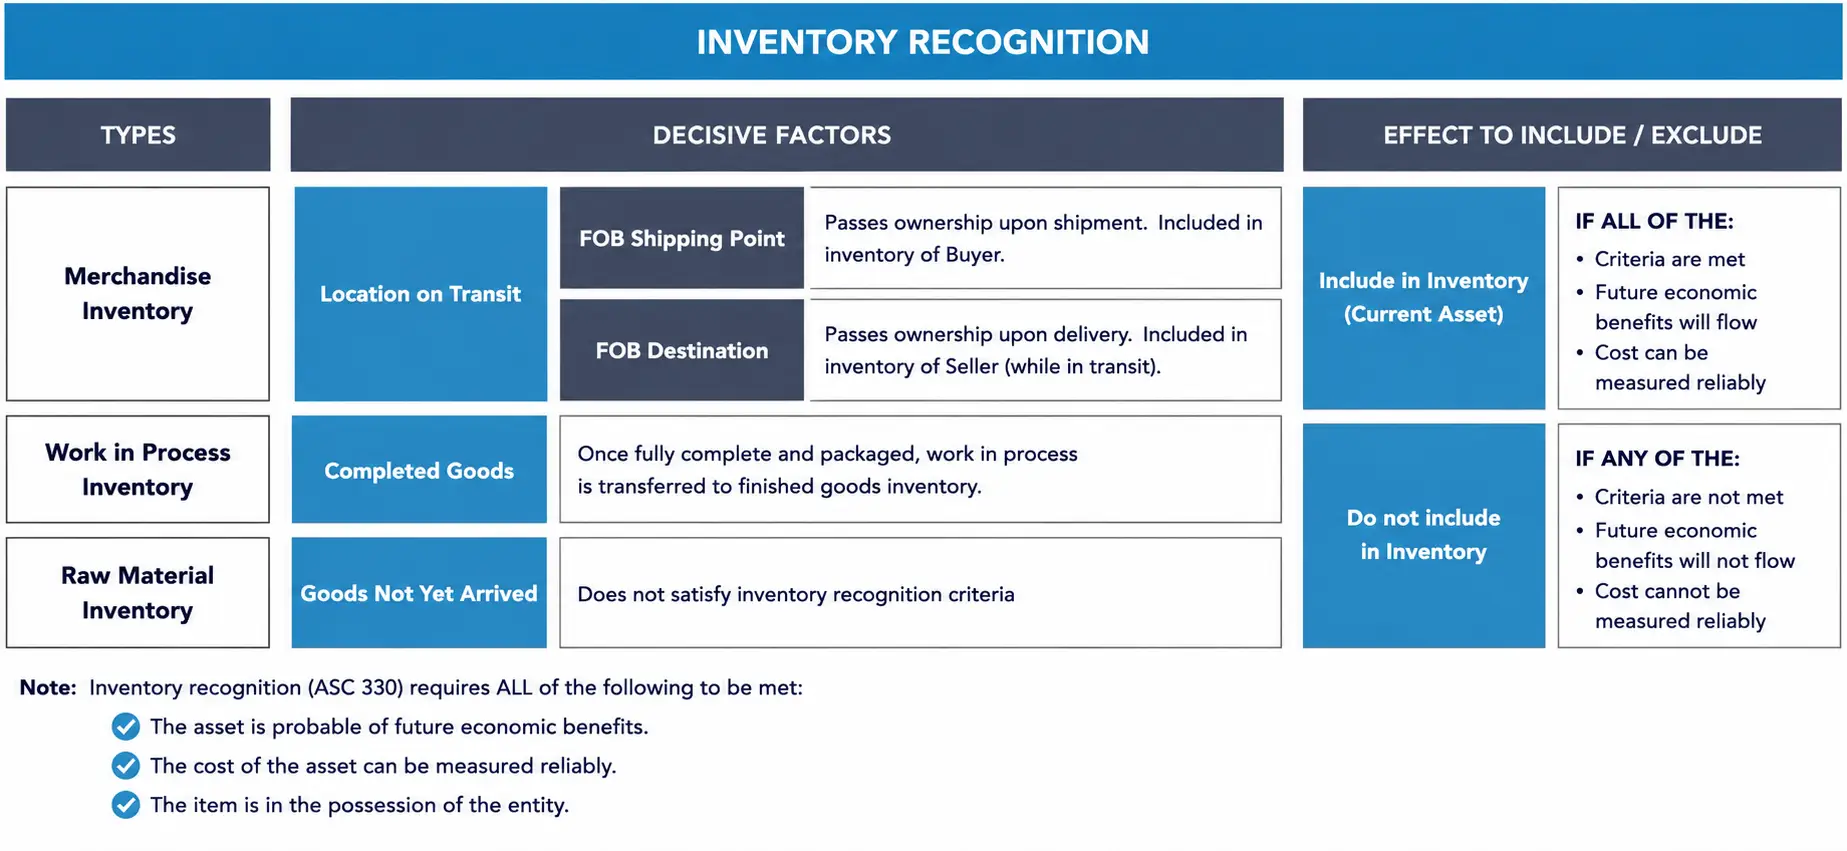
Because inventories are assets the company owns, the test for what to include is ownership (title), not physical location.
In particular, a company needs to include inside the “inventories” line item in the balance sheet all inventory items that the company owns or has title to, as of the balance sheet date. This may sound pretty straight-forward for unsold inventories at the company’s physical warehouse, but there are certain cases that need to be considered as per below:
Inventories in transit
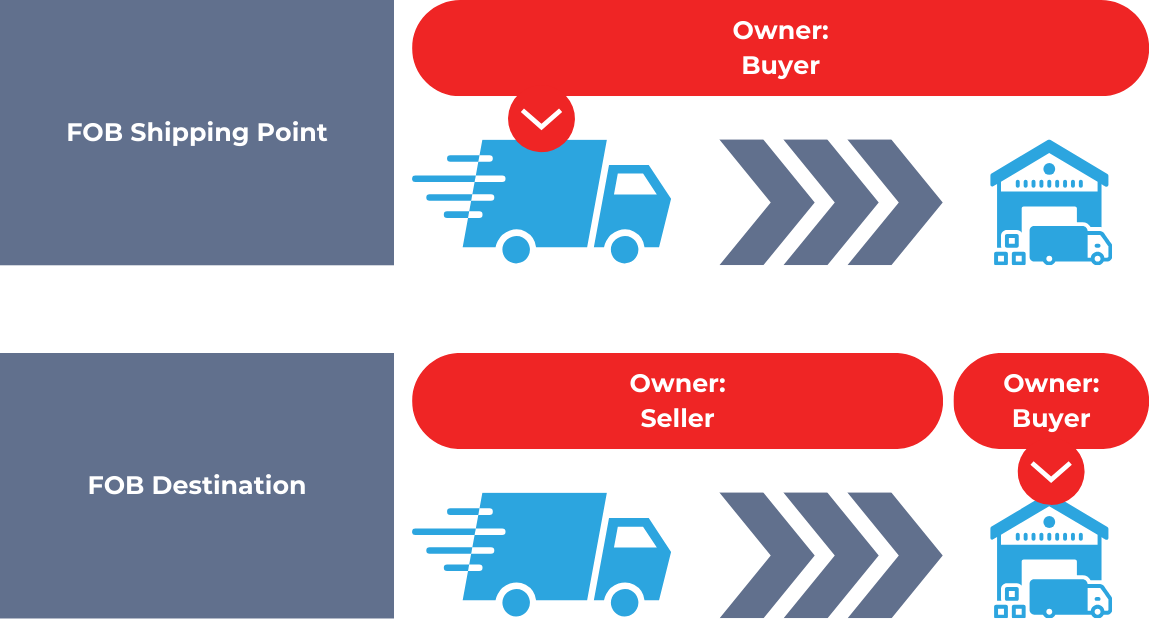
There are inventories that are either sold to a customer or purchased from a supplier but still did not arrive at their intended destination as at the end of the year. This needs to be considered in the assessment because the ownership of the inventories may pass on at different times depending on the terms of shipping:
- FOB shipping point; or
- FOB destination
Since a trading company can either be a buyer or a seller, you need to consider both points of view in assessing inventory ownership. Below is a summary of the impacts to the inventory balance on an in transit inventory during year-end depending if the company is a buyer or the seller of the merchandise:
| Terms of shipping | Company is: | |
| Buyer | Seller | |
| FOB shipping point | Included in inventory | Excluded from inventory |
| FOB destination | Excluded from inventory | Included in inventory |
Consigned goods
Consignment is an arrangement whereby a company (the consignor) delivers goods to another company (the consignee) but the title is retained by the consignor until the goods are finally sold to the end customer. The consignee becomes responsible to sell the goods as an agent and has the ability to return unsold goods, thereby bearing no risk in the arrangement.
In a consignment arrangement, the goods are included in the inventory of the consignor because the title has not passed during the delivery. It is accounted for only as a reclassification of the inventory cost plus any shipping cost paid to deliver the goods to the consignee. For example, a consignor ships goods costing to a consignee and pays in freight:
| Account | Debit | Credit | Financial statement element |
| Inventories on consignment | $10,500 | Asset | |
| Inventories | $10,000 | Asset | |
| Cash | $500 | Asset | |
| To record delivery of inventories out on consignment | |||
The freight is capitalized, not expensed.
If the company is a consignee, even if physically in the consignee’s warehouse, the consigned goods (also called goods held on consignment) are not included in its balance sheet as inventories.
Obsolete inventories
When for whatever reason an inventory item cannot be sold anymore, it is deemed as obsolete. These items are not expected to bring future benefits to the company and should not be a part of a company’s assets anymore. The cost of the obsolete inventories should be written off in the period when they are determined to be obsolete. A sample journal entry is as follows:
| Account | Debit | Credit | Financial statement element |
| Loss on inventory obsolescence | $500 | Loss | |
| Inventories | $500 | Asset | |
| To record write-off of obsolete inventories | |||
When inventories have salvage values, it means a portion of their costs can be recovered through sale. This topic is covered by “inventory valuation” in a subsequent section.
What costs to include in inventory
Another issue related to inventory accounting is the determination of what constitutes the capitalizable costs of an inventory. A company routinely pays for costs of different nature and we need to determine if such payments should go to the income statement (as expenses) or to the balance sheet (as inventories).
Inventoriable costs include:
- Costs to purchase the inventory which include the purchase price, transport costs, handling costs, and other costs directly attributable to the purchase of raw materials or finished goods. These amounts are recorded net of any trade discounts and rebates.
- Costs of conversion include costs required to directly or indirectly convert raw materials or work-in-progress inventories into finished goods. Examples are direct labor costs, variable and fixed overheads. This is common only for manufacturing companies.
- Other costs incurred in bringing the inventories to their present location and condition.
The following items are expensed in the income statement and are therefore not included as inventoriable costs:
- Abnormal costs related to freight, handling, and wasted materials (spoilage). Only the abnormal, unexpected portion of these costs is expensed - normal (routine) freight-in and expected spoilage are still inventoriable costs.
- Storage costs except when the storage costs are required for the production process (i.e., inventory handling costs related to the raw materials of a manufacturing company)
- Administrative overhead costs. These costs are not directly or indirectly related to the production of goods so they are excluded from inventory costs
- Selling costs
- Costs to transport goods to the customer or freight-out (note that costs to transport inventories to a consignee are inventoriable costs)
Example: Computing inventoriable cost
A retailer buys inventory for , pays in freight-in to get the goods to its warehouse, and receives a trade discount from the supplier. It also pays in administrative costs and in sales commissions related to the purchase.
Only the purchase price, freight-in, and trade discount affect inventoriable cost - administrative costs and selling costs are expensed as incurred.
Inventoriable cost:
Answer: