



Introduction to flexible budgets
A flexible budget restates the budget at the actual activity level so results can be judged fairly. This chapter defines it, contrasts it with a static budget, and shows how to build one.
Definition and purpose of flexible budgets
The primary purposes of a flexible budget are:
- To account for the variability of costs and revenues as activity levels change.
- To provide a relevant basis for comparison with actual results, enabling meaningful variance analysis.
- To improve decision-making by offering a realistic view of performance under actual operating conditions.
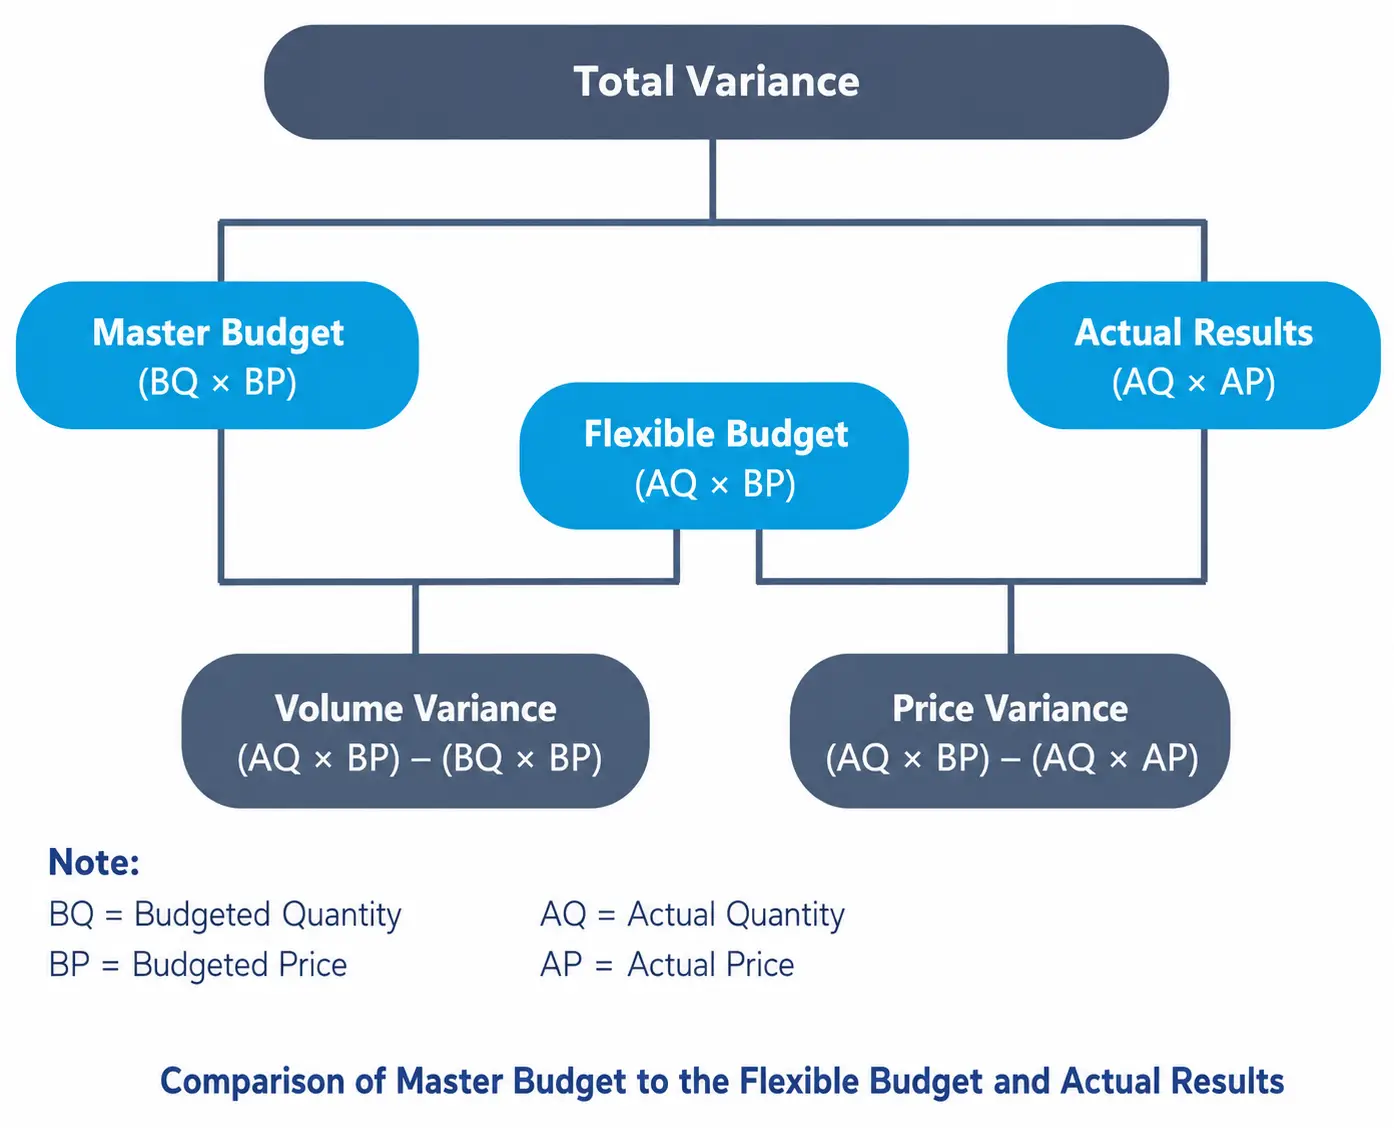
Comparing the master (static) budget, the flexible budget, and actual results splits the total static-budget variance into two pieces: a sales-volume variance (flexible budget vs. static budget, caused by activity differing from plan) and a flexible-budget variance (actual results vs. flexible budget, caused by differences in prices and in input efficiency). The diagram below previews the detailed cost-variance formulas used in later chapters.
Benefits of flexible budgets in performance analysis
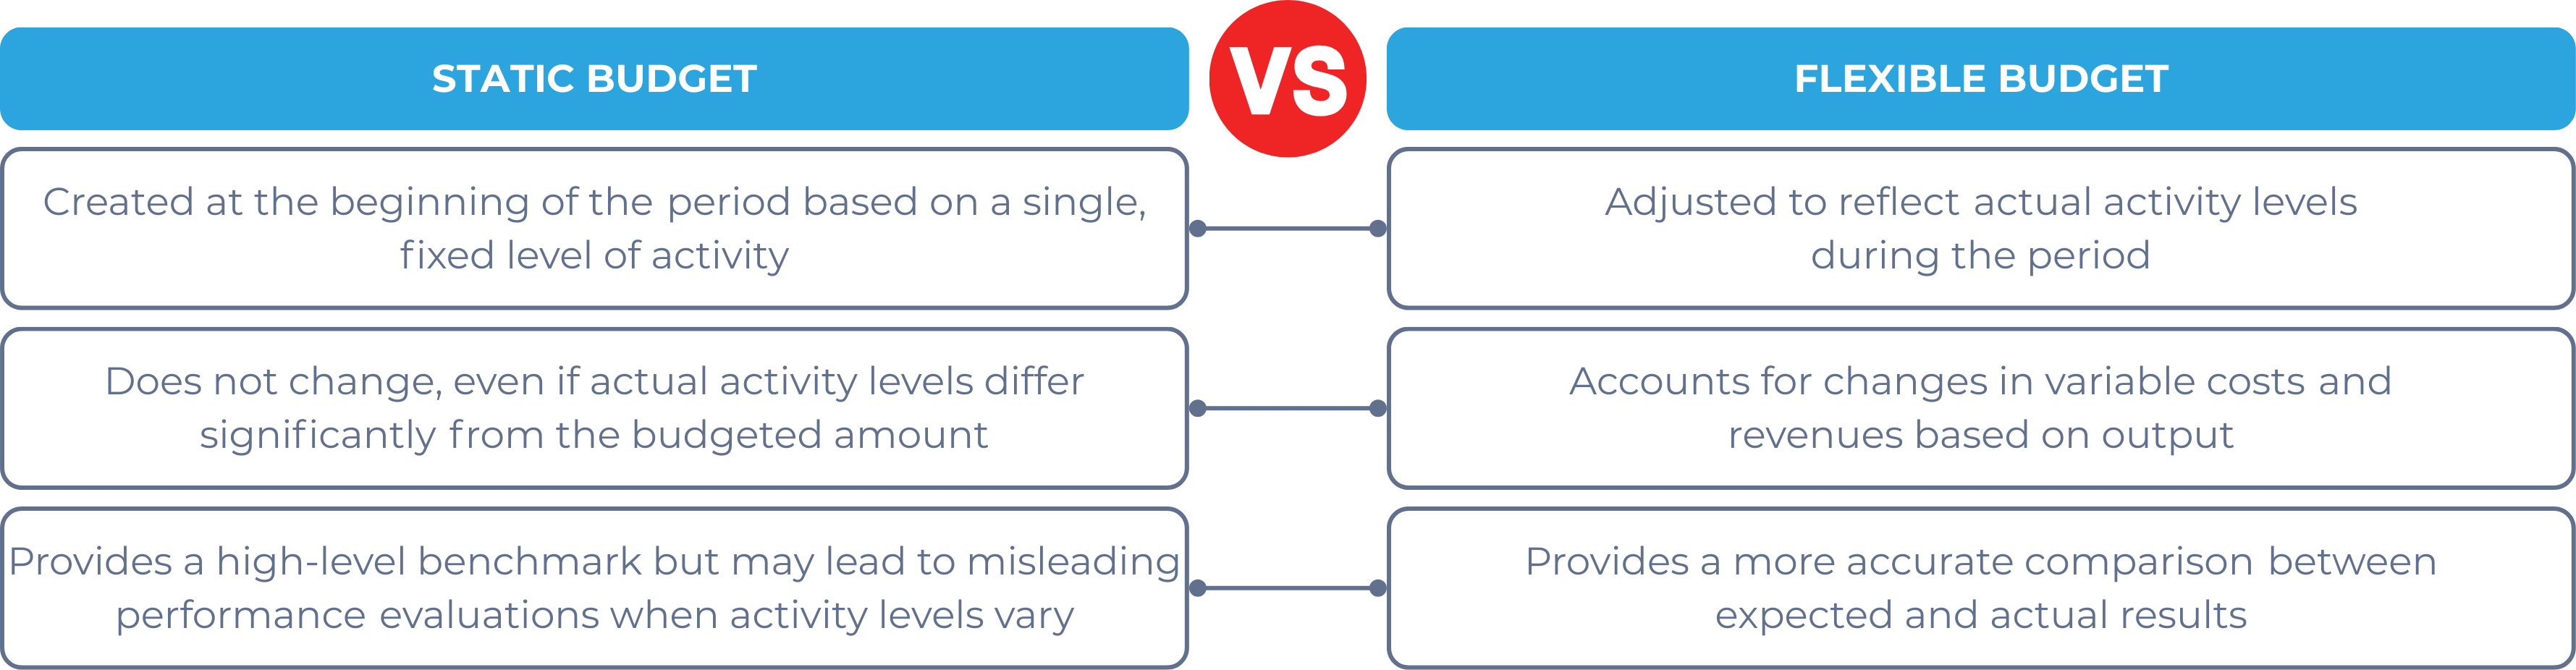
Flexible budgets resolve the issue from the previous section by separating the total static-budget variance into a sales-volume variance and a flexible-budget variance. Flexible budgets also offer several other advantages in analyzing performance:
- More accurate variance analysis
By accounting for changes in activity levels, flexible budgets provide a realistic basis for variance calculations. Because the benchmark is restated at actual volume, any remaining variance reflects price and efficiency performance, not the mere fact that output was higher or lower than planned. - Improved decision-making
Flexible budgets highlight variances that truly reflect operational performance, helping managers identify areas requiring attention. For instance, identifying an unfavorable variance in material costs despite expected production levels allows managers to investigate potential inefficiencies or supplier issues. - Enhanced accountability
Flexible budgets adjust expectations to match actual conditions, ensuring that performance evaluations are fair and meaningful. This motivates managers to focus on controllable factors rather than external circumstances that could skew static budget comparisons. - Adaptability to dynamic environments
Flexible budgets are especially useful in industries with fluctuating demand or variable production levels. By adapting to real-time conditions, they provide a relevant framework for monitoring and managing performance.
Creating a flexible budget
Understanding how to adjust a budget based on actual sales or production levels is essential for accurate performance analysis. This section discusses how to modify a static budget into a flexible budget, emphasizing the importance of activity level adjustments and introducing the concept of more complex scenarios where both activity levels and prices per unit vary.
A static budget is prepared at the start of the period based on an expected level of activity. However, actual performance often deviates from these expectations, necessitating the creation of a flexible budget that adjusts for the actual output level.
Example: Converting a static budget to a flexible budget
A company budgets to produce and sell 10,000 units of its product in a month. Relevant data from the company’s budget are as follows:
- Revenue of $10 per unit.
- Variable costs of $4 per unit.
- Fixed costs of $20,000.
At the end of the period, actual sales volume was 12,000 units while the unit costs and sales price were the same as in the budget.
The static budget comes directly from the budgetary data explained above. No further adjustments are necessary.
Category Computation Static budget
(10,000 units)Revenue 10,000 × $10 $100,000 Variable costs 10,000 × $4 ($40,000) Fixed costs - ($20,000) Operating profit $40,000 For the flexible budget, we adapt the computations of the static budget but use the actual volume of 12,000 instead of the planned 10,000.
Category Computation Flexible budget
(12,000 units)Revenue 12,000 × $10 $120,000 Variable costs 12,000 × $4 ($48,000) Fixed costs - ($20,000) Operating profit $52,000 The static budget reflects the company’s original plan for 10,000 units while the flexible budget adjusts the revenue and variable costs to account for the actual output of 12,000 units. Fixed costs remain unchanged as they are not dependent on activity levels. For a mixed cost, flex only the variable part: allowance = fixed component + variable rate × actual activity.
The $12,000 favorable difference ($52,000 − $40,000) is due only to selling 2,000 more units than planned. This is the sales-volume variance, and it says nothing about cost control. Performance is judged by comparing actual results with the $52,000 flexible budget, covered in the next chapters.
Answer: Flexible budget operating profit = $52,000 (vs. static budget profit of $40,000).
In this simple example, only activity levels changed, while the price per unit for revenue and variable costs remained as the budgeted prices. In real-world scenarios and in the CMA examination, actual prices may also differ from budgeted assumptions. For instance, revenue per unit might increase due to a price hike, or variable costs per unit might rise due to input cost inflation. These price changes will make the analysis more complex which we will show in the next sections.