



Overhead allocation methods
In manufacturing and service organizations, indirect costs, commonly referred to as overhead, must be allocated to cost objects such as products, jobs, or departments. Since overhead cannot be traced directly, a systematic and rational method is required for allocation. This section discusses various approaches to calculating and applying overhead rates, including corporate-wide, departmental, and activity-specific rates, as well as the selection and use of appropriate allocation bases.
Common overhead rate structures
Overhead can be applied using different rate structures, depending on the complexity of operations and the level of detail required. The three most common are:
Corporate-wide overhead rate
This method uses a single overhead rate for the entire organization, calculated by dividing the total estimated overhead by the total estimated activity base (e.g., machine hours or labor hours):
Departmental overhead rates
Each department calculates its own overhead rate based on its specific overhead costs and activity drivers, using the same formula above but computed per department. For example, the machining department uses machine hours, while the assembly department uses labor hours.
Activity-based overhead rates
Used in activity-based costing (ABC) systems, this method applies overhead by linking cost pools to specific activities and using appropriate cost drivers (e.g., number of setups, inspections, or orders processed). A detailed discussion of activity-based costing and comparisons to traditional systems is presented in the section about ABC in this chapter.
Understanding the strengths and weaknesses of each overhead allocation method helps organizations choose the most appropriate system for their operations. Below is a comparison of the three commonly used methods:
| Method | Benefits | Limitations |
| Corporate-wide overhead rate | Simple to implement and maintain Low administrative cost Suitable for uniform operations |
May distort costs in complex or multi-department environments Ignores departmental or activity differences Poor cost traceability for decision-making |
| Departmental overhead rates | More accurate than a single rate Reflects differences in departmental cost structures Enhances cost control at the departmental level |
Still assumes uniformity within departments Requires tracking of departmental costs and activities More complex than corporate-wide method |
| Activity-based overhead rate | Highly accurate cost allocation Aligns overhead with resource consumption Supports strategic decisions (e.g., pricing, profitability) |
Data-intensive and complex to implement High system and training costs May not be cost-effective for simple operations |
Allocation bases for overhead
Choosing the right allocation base is critical for meaningful cost assignment. The base should reflect a cause-and-effect relationship between the incurrence of overhead and the cost object’s use of resources.
Variable overhead bases typically include:
- Direct labor hours or costs
- Machine hours
- Units produced
Fixed overhead bases are often chosen to allocate factory costs that do not vary with production, such as rent or depreciation. Common bases include:
- Normal or practical capacity in labor or machine hours
- Budgeted production volume
The fixed overhead application rate follows the same general formula as above - budgeted fixed overhead divided by the chosen allocation base (e.g., practical capacity). For example, a company expects $100,000 in fixed overhead and 10,000 labor hours of practical capacity:
This rate is then multiplied by the actual labor hours used to determine the amount of overhead applied to jobs or units.
Predetermined overhead rate and application in production
In most practical settings, overhead costs are applied to production using a predetermined overhead rate, rather than waiting until actual costs are known. This rate is computed in advance of the accounting period based on estimated figures, providing timely cost information that supports budgeting, pricing, and performance evaluation.
The estimated total overhead costs include both fixed and variable components expected for the upcoming period. The allocation base can be labor hours, machine hours, or any other activity driver depending on the nature of operations.
This predetermined rate is then applied to actual production activity during the period to assign overhead costs to products or jobs.
Why use a predetermined rate?
- Timeliness: Managers need cost data during the period, not just after actuals are finalized.
- Cost control: Allows for variance analysis by comparing applied vs. actual overhead.
- Standardization: Ensures consistent costing, particularly important for inventory valuation under absorption costing.
Comparison of this approach with other overhead application approaches:
| Method | Overhead used | Timing | Characteristics |
| Actual overhead rate | Actual costs / actual base | After period-end | Highly accurate but not timely. Not suitable for interim use. |
| Normal costing | Predetermined OH rate × actual base | During the period | Balances accuracy and timeliness. Most widely used in practice. |
| Standard costing | Standard OH rate × standard base | During the period | Supports budgeting and variance analysis. May require frequent updates. |
Note that in normal costing, direct materials and direct labor are recorded at actual amounts, but overhead is applied using a predetermined rate, allowing for prompt recording of production costs. This is the approach most commonly tested on the CMA exam.
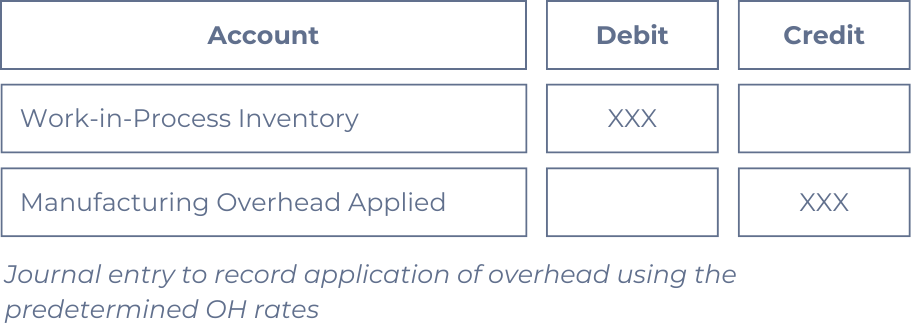
Once the predetermined rate is established, it is used to apply overhead to work-in-process (WIP) during production:
Example: Applying a predetermined overhead rate
A company budgets $40,000 of variable overhead and $100,000 of fixed overhead for the year, based on 10,000 labor hours of practical capacity.
- Variable overhead rate: $40,000 ÷ 10,000 hours = $4 per labor hour
- Fixed overhead rate: $100,000 ÷ 10,000 hours = $10 per labor hour
- Combined (predetermined) overhead rate: $4 + $10 = $14 per labor hour
A job that uses 50 actual labor hours is applied 50 × $14 = $700 of overhead, recorded as a debit to work-in-process (WIP) and a credit to manufacturing overhead applied.
Answer: $700 applied ($200 variable + $500 fixed)
At the end of the period, the difference between applied and actual overhead is assessed. Overapplied or underapplied overhead must be reconciled and adjusted, typically through cost of goods sold (COGS), or proportionally across WIP, finished goods, and COGS accounts. Because the fixed rate is set using practical capacity, any period in which the activity used to apply fixed overhead falls short of that capacity leaves some fixed overhead unabsorbed (underapplied). Under standard costing, that shortfall - budgeted fixed overhead minus fixed overhead applied to the standard hours allowed for actual output - is the unfavorable production volume variance, covered later in the fixed overhead (FOH) cost variance material. The full mechanics of reconciling applied and actual overhead are covered in the next chapter, Overapplied and underapplied overhead.