



Insurance Contracts
Essential Elements of an Insurance Contract
An insurance contract is built on utmost good faith from everyone involved. The applicant relies on the insurer’s promise to pay covered benefits. The insurer relies on the applicant to provide truthful, complete information on the application.
Insurance is also governed by contract law. For a contract to be valid and enforceable, the following conditions must be met:
- There must be consideration by both parties.
- An offer must be made by one party and acceptance of that offer made by the other party.
- All parties to the contract must be legally capable of entering into a contract.
- The purpose of the contract must be legal.
Consideration
For a contract to be valid, each party must give something of value (this exchange is called consideration).
- The insurer’s consideration is its promise to pay policy benefits if the insured suffers a covered loss (acceptance of the risk).
- The applicant’s consideration is the premium.
Premiums are often calculated on an annualized basis, but different payment modes (monthly, quarterly, semiannual) may be used. Statutory reserves are maintained to meet future claim obligations.
The more often premium is paid, the more the insured pays over a year, because the insurer collects less money up front to invest and incurs more billing and processing expense. Paying less often, such as annually instead of monthly, lowers the total annual outlay.
Offer and acceptance
An offer made by one party must be accepted by the other unconditionally.
- The applicant makes the offer by completing an application.
- The insurer may accept the application as written, or it may make a counteroffer (for example, by proposing a rated policy).
A contract forms only when both parties agree to the final terms. If they don’t agree, there is no contract.
Competent parties (legal capacity)
Both parties must be legally capable of entering into a contract.
- If the insurer is admitted or authorized in the state, it has legal capacity.
- The applicant has legal capacity unless he/she is a minor, mentally incompetent, intoxicated, or under the influence of narcotics.
Certain individuals, such as enemy aliens or others restricted by law, may also lack capacity in specific jurisdictions.
Legal purpose
A valid contract must be for a legal purpose and not against public policy. A life insurance policy purchased with the intent to have the insured killed is an obvious example of an invalid contract.
For an insurance contract to be valid, there must be an insurable interest between the applicant/owner and the insured.
- For life insurance, insurable interest must exist at policy inception.
- For property and casualty insurance, it must exist at the time of loss.
Policy structure
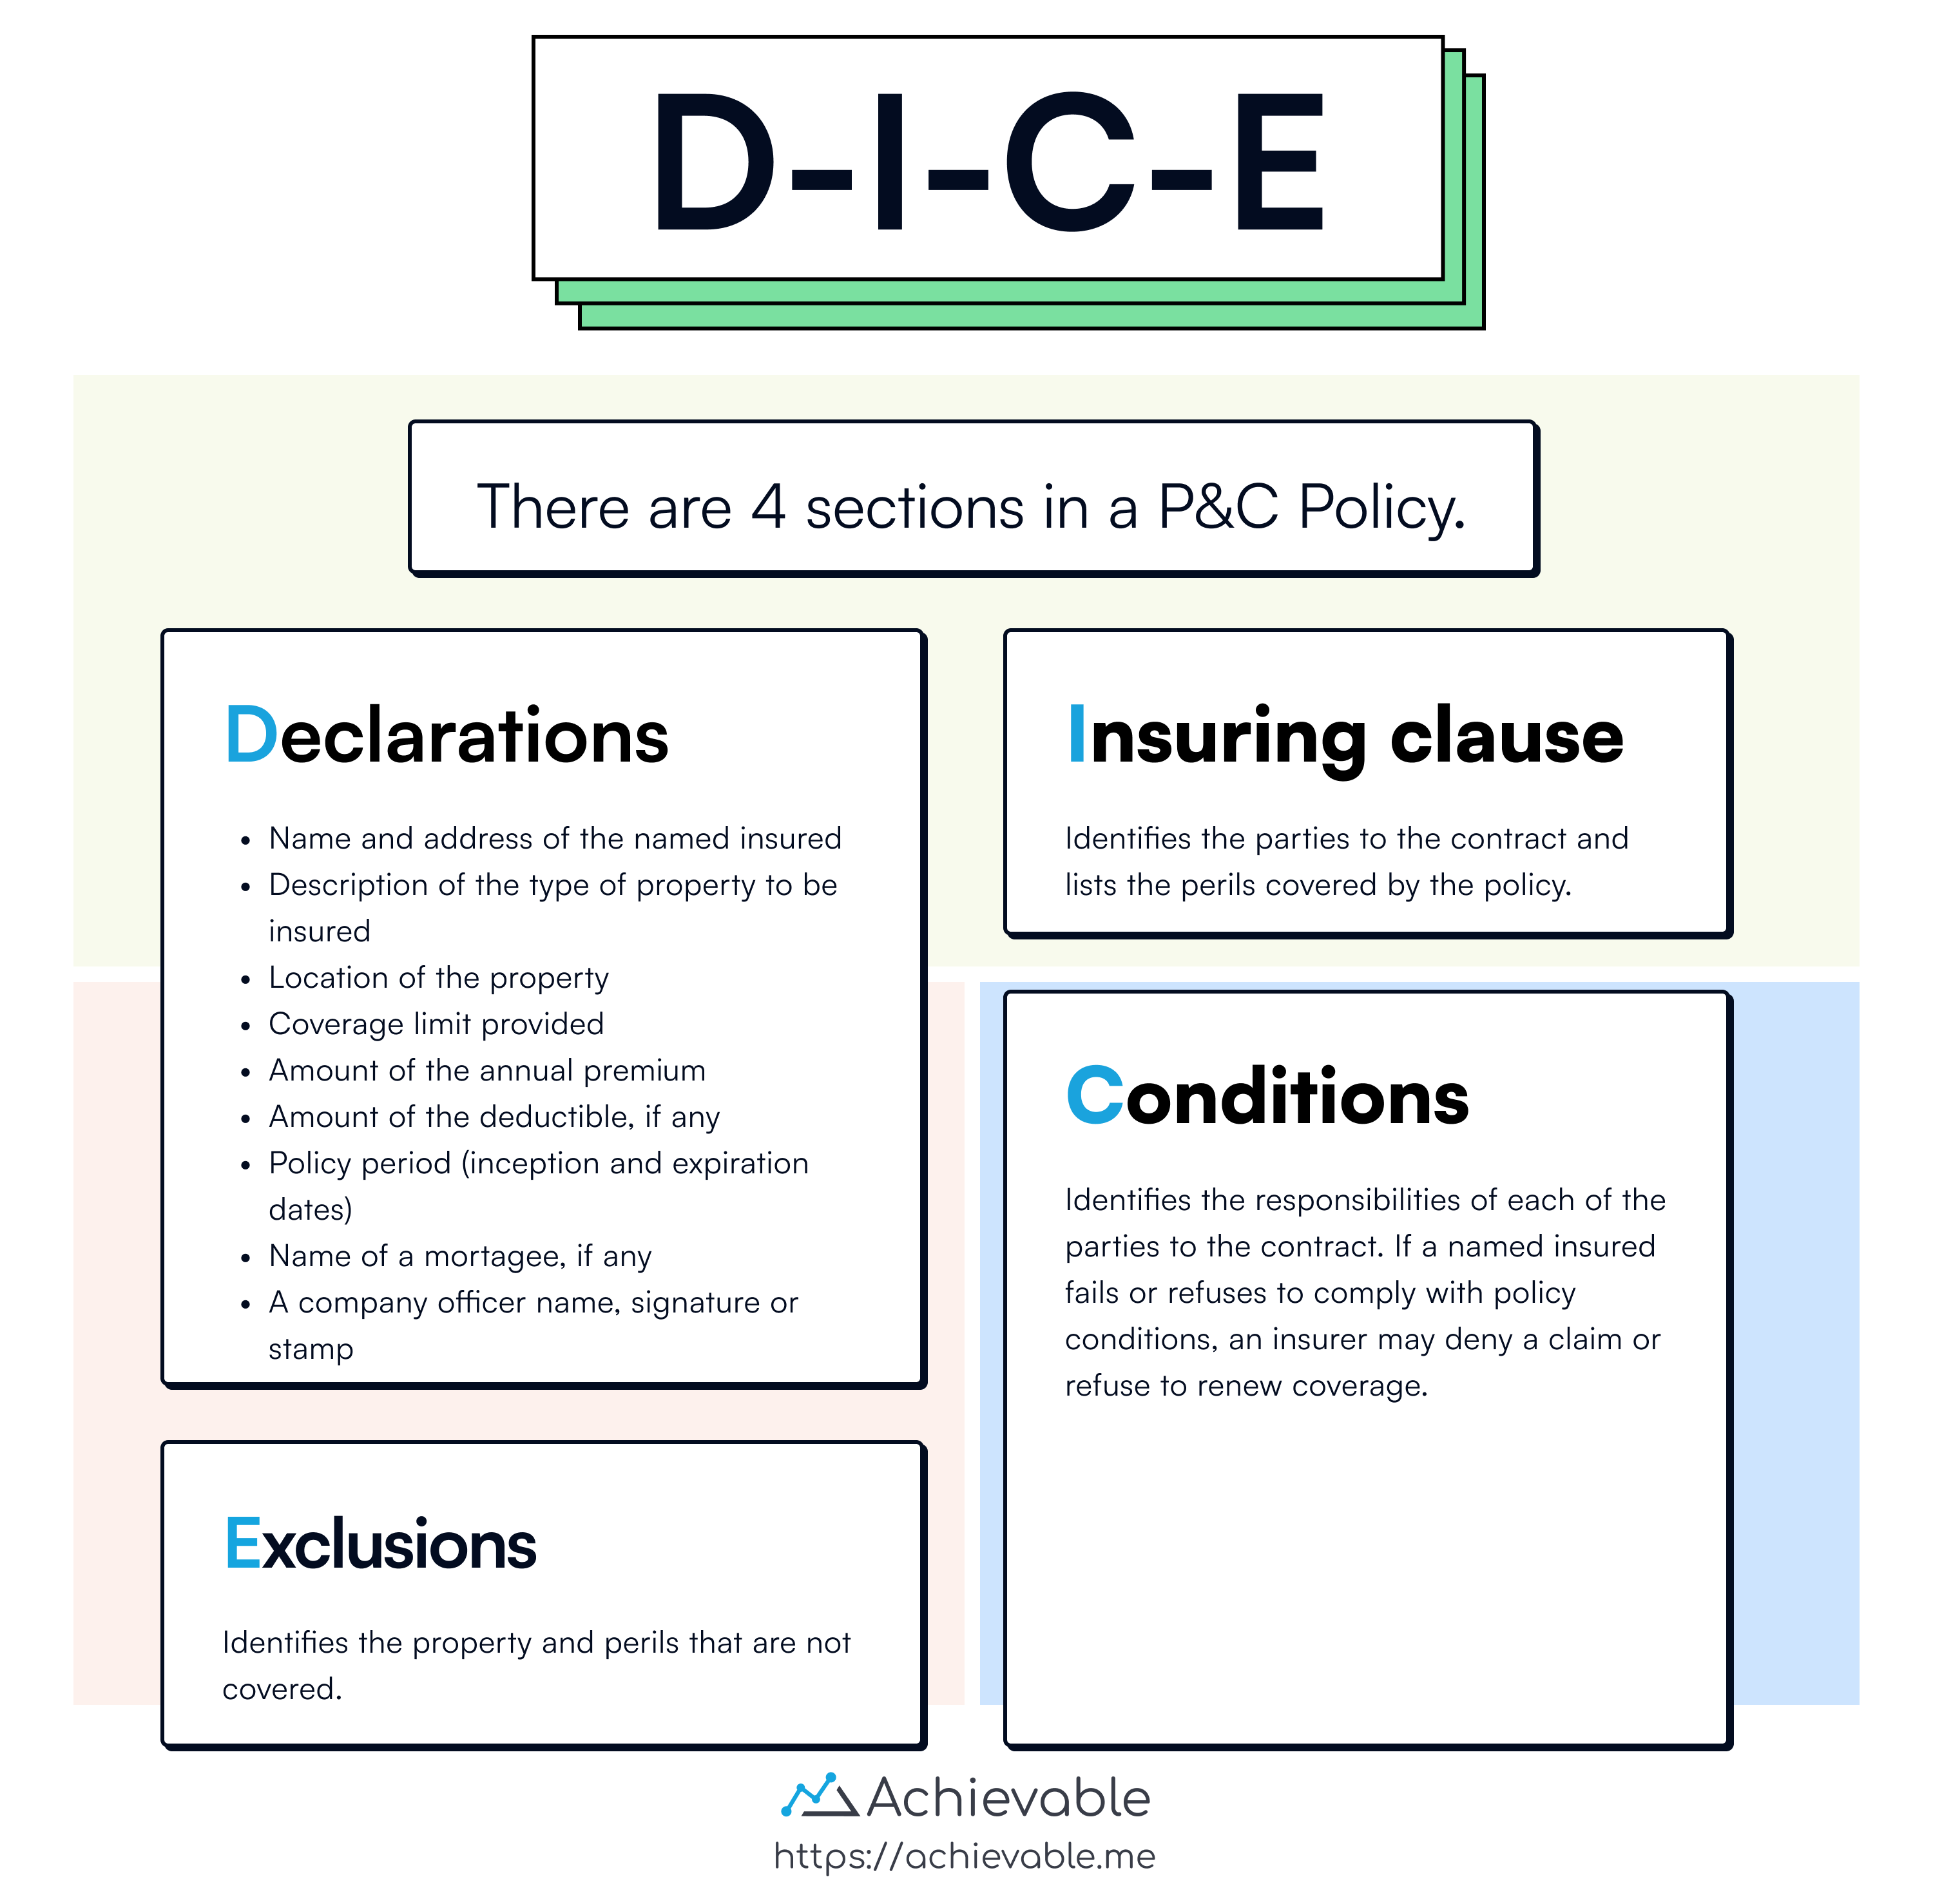
A property and casualty insurance policy is comprised of four basic sections of coverage including:
-
Declarations
-
Insuring agreement
-
Conditions
-
Exclusions
Declarations
The declarations page summarizes key information about the property or exposures being insured. Much of this information comes directly from the application and includes, but is not limited to:
-
Name and address of the named insured
-
A description of the type of property to be insured
-
The location of the property
-
The coverage limit provided
-
The amount of the annual premium
-
Amount of the deductible, if any
-
The policy period (inception and expiration dates)
-
The name of a mortgagee, if any
-
A company officer name, signature or stamp
Insuring agreement (insuring clause)
This section summarizes the coverage agreement between the named insured and the insurer. More specifically, it identifies the parties to the contract and lists the perils covered by the policy.
Conditions
This section explains the responsibilities of each party to the contract. If a named insured fails or refuses to comply with policy conditions, an insurer may deny a claim or refuse to renew coverage.
Most policy conditions are placed on the named insured. For example, after a loss the named insured must give the insurer prompt notice, protect the property from further damage and cooperate with the insurer’s investigation of the claim.
Exclusions
This section identifies the property and perils that are not covered. Exclusions allow an insurer to protect itself from financial disaster by not providing coverage for catastrophic losses.
Besides these four sections, a policy has definitions, may provide additional or supplementary coverages, and can be changed by endorsements.
Definitions
The definitions section gives the meaning of words and phrases that have a special meaning in the policy. Words and phrases that appear in quotation marks have the special meaning the definitions section gives them.
Additional/supplementary coverage
Additional coverages are coverages a property policy adds to its main coverages, such as the cost of removing debris after a covered loss. Some are paid as additional insurance and some reduce the limit that applies to the loss. In a liability policy, supplementary payments, such as the insurer’s expenses in defending a suit, are paid in addition to the limit of liability.
Endorsements
An endorsement is a form added to a policy that changes or adds to its provisions. An endorsement may broaden coverage, restrict it, or add insureds or locations. A policy’s terms can be changed only by an endorsement issued by the insurer.
Legal interpretations affecting contracts
Insurance contracts are unique in that the applicant must purchase the policy as written, without an opportunity to modify or clarify the contract language. Over time, courts have applied the Doctrine of Adhesion to interpret ambiguous contract terms or conditions in favor of the insured, since the insured had no chance to alter the contract at the time of application.
Reasonable expectations
Courts in some states go a step further than resolving ambiguous wording. Under the doctrine of reasonable expectations, a court interprets a policy to provide the protection the insured might reasonably have expected, even if the policy wording does not provide that coverage. Not every state recognizes the doctrine.
Indemnity
Property and liability insurance policies are contracts of indemnity: a person who recovers under one should be restored to approximately the financial position that person was in before the loss, and should not profit from it. That is why a property policy pays no more than the insured’s financial interest in the property, and why other insurance and subrogation provisions keep an insured from being paid twice for one loss.
Good faith
Each party to an insurance contract is entitled to rely on what the other says. This duty of utmost good faith runs both ways: the applicant must give the insurer truthful and complete information, and the insurer must deal honestly with the applicant and keep the promises it makes in the policy. The rules on representations, concealment and fraud below are how that duty is enforced against an applicant or insured.
Warranties, representations, misrepresentations, and concealment
Insurers work to make contract language clear and to avoid misunderstandings about policy terms. Even so, questions and conflicts can arise, and they often involve warranties and representations.
A warranty is a statement or promise incorporated into the policy that must be true as stated or performed as promised. Under modern insurance law, a breach must generally be material to affect coverage.
Representations are statements made on the application that are substantially true to the best of the applicant’s knowledge.
A misrepresentation is a false or misleading statement. A misrepresentation is material when it is significant enough to affect the insurer’s decision to issue the policy, set the premium or accept the risk. A misrepresentation that is both intentional and material can allow the insurer to void the policy.
Concealment is the willful holding back of information that is pertinent to the insurance, even though the insurer did not ask about that subject. Like a misrepresentation, concealment of a material fact can void the policy.
Fraud
Fraud is deception used to cheat or to intentionally mislead. In its usual form, a person makes a false statement of fact, knowing it is false or recklessly disregarding whether it is true, and intending that another person rely on it; that person reasonably relies on it and is harmed. Fraud is closely related to misrepresentation and concealment. What sets it apart from an innocent misstatement is the intent to deceive. The standard commercial property conditions state that coverage is void in any case of fraud by the named insured relating to the coverage, and also if the named insured or any other insured intentionally conceals or misrepresents a material fact about the coverage, the covered property, the named insured’s interest in it or a claim.
If an applicant makes a statement on an application that the applicant knows is false, it is a misrepresentation and may constitute fraud. If the insurer can prove that a material misrepresentation was made intentionally, it may void the contract, and the applicant may be prosecuted for insurance fraud, which state law makes a crime.
Lesson Summary
An insurance contract is based on utmost good faith: the applicant relies on the insurer’s promise to pay, and the insurer relies on the truthfulness of the applicant’s statements.
To be valid and enforceable under contract law, an insurance contract must include consideration, offer and acceptance, legal capacity, and a legal purpose. Consideration is the exchange of value: the insurer promises to pay benefits for covered losses, and the applicant pays the premium.
Offer and acceptance require an unconditional agreement. The applicant makes an offer by submitting an application. The insurer may accept it as written or make a counteroffer (such as a rated policy). Legal capacity means both parties must be able to enter into a contract. The contract must also have a legal purpose and not violate public policy. A valid insurance contract also requires an insurable interest between the applicant/owner and the insured.
-
Insurance contracts have unique features:
-
Applicants must accept policies as written without modification.
-
The Doctrine of Adhesion favors insured parties in case of ambiguous terms.
Insurers strive for clear contract language to prevent misunderstandings.
A valid insurance contract must establish an insurable interest. Additionally, a property and casualty insurance policy consists of four parts:
- Declarations: Information about the insured property
- Insuring Clause: Summary of coverage and perils covered
- Conditions: Responsibilities of each party
- Exclusions: Identifies what is not covered
A policy also has a definitions section, may provide additional or supplementary coverages, and can be changed by endorsements.
Warranties are statements or promises that must be true as stated or performed as promised, although under modern insurance law a breach must be material to affect coverage; representations are statements believed to be true to the best of the applicant’s knowledge.
Misrepresentations, if intentional and material, can void the contract and may constitute fraud. Concealment is the willful holding back of pertinent information, and fraud is intentional deception. Under the doctrine of reasonable expectations, courts in some states read a policy to give the protection an insured might reasonably have expected.