


This browser is too old to run Achievable.

Update it, or open this page in a current version of Chrome, Safari, Firefox or Edge. On an iPhone or iPad, update iOS: every browser there runs on the version of Safari that comes with it.

Achievable logoAchievable logo
CMA Part 1
Sign in
Sign up
Purchase
Textbook
Practice exams
Support
How it works
Resources
Exam catalog
Mountain with a flag at the peak
Textbook
Introduction
1. External financial reporting decisions
2. Planning, budgeting, and forecasting
3. Performance management
4. Cost management
5. Internal control
6. Technology and analytics
Wrapping up
Achievable logoAchievable logo
3.2.4.1 Transfer pricing objectives and methods
Achievable CMA Part 1
3. Performance management
3.2. Responsibility centers and reporting segments
3.2.4. Transfer pricing
Our CMA Part 1 course is currently in development and is a work-in-progress.

Transfer pricing objectives and methods

8 min read
Font
Discuss
Share
Feedback

Learning outcome statements

The learning outcome statements relevant for this section are:

  1. define transfer pricing and identify the objectives of transfer pricing
  2. identify the methods for determining transfer prices, and list and explain the advantages and disadvantages of each method
  3. calculate transfer prices using variable cost, full cost, market price, negotiated price, and dual-rate pricing
  4. explain how transfer pricing is affected by business issues, such as the presence of outside suppliers and the opportunity costs associated with capacity usage
  5. describe how special issues such as tariffs, exchange rates, taxes, currency restrictions, expropriation risk, and the availability of materials and skills affect performance evaluation in multinational companies

Objectives of transfer pricing

Definitions
Transfer pricing (TP)
The practice of determining the value of goods, services, or intangible assets transferred between different units or divisions within the same organization.

Transfer pricing establishes an internal price for transactions occurring between related entities, such as a parent company and its subsidiaries or between divisions of the same company. Effective transfer pricing ensures accurate representation of the economic value of intercompany transactions.

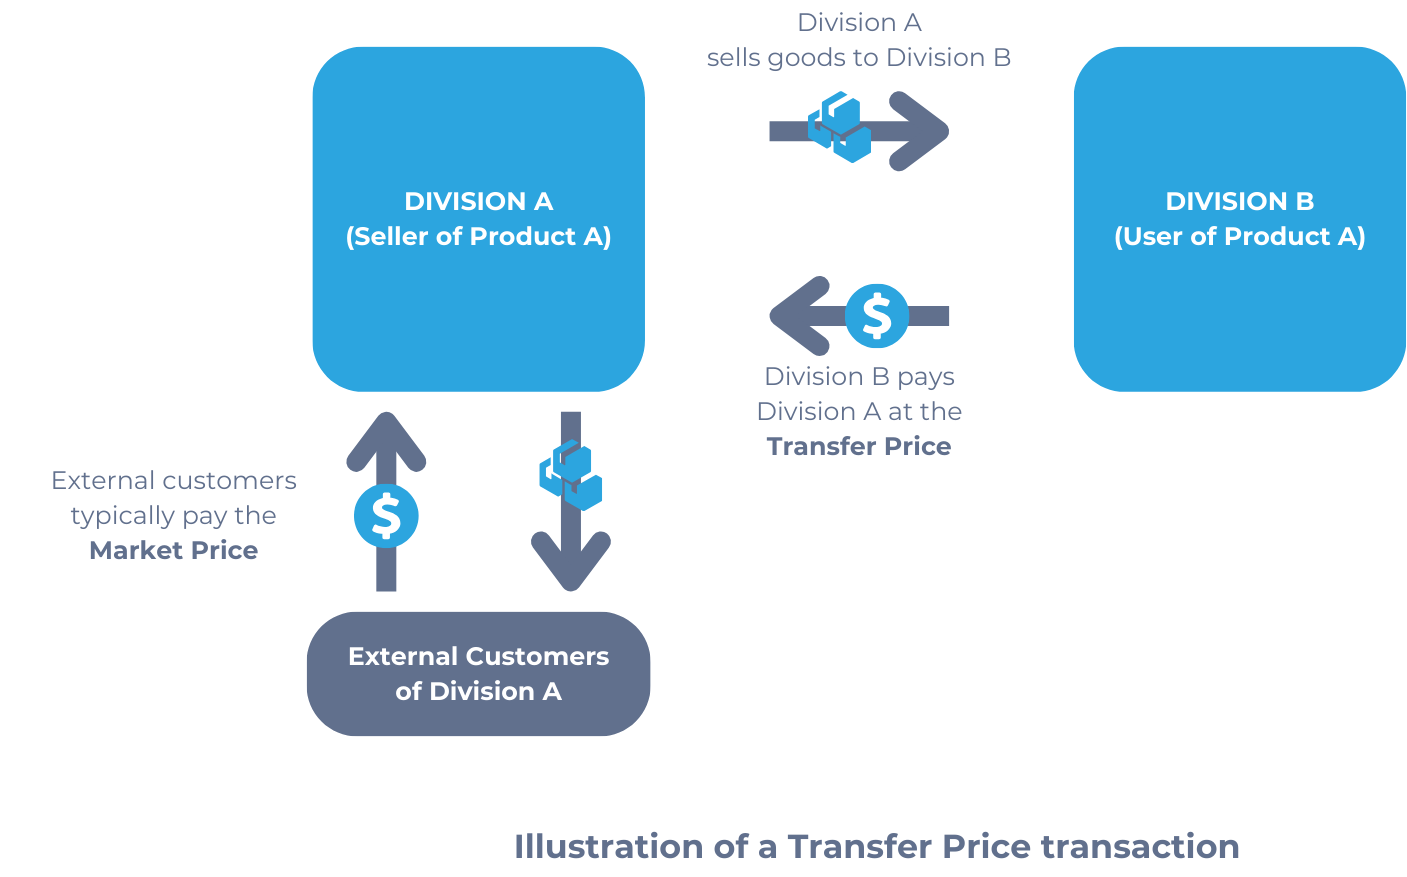
Consider a manufacturing company with two divisions: Division A produces a component (Product A) that is used by Division B in assembling the final product. Division A has two choices: it can sell the component to external customers at the market price, or it can transfer the component internally to Division B at an agreed transfer price.

Illustration of a transfer price transaction
Achievable

The transfer price directly affects how each division’s performance is measured. If the transfer price is set too low, Division A may appear less profitable even though it is efficient, while Division B will benefit from lower input costs. If the transfer price is set too high, Division B may appear unprofitable despite creating value for the company as a whole.

This illustrates why transfer pricing is important: it ensures that intercompany transactions reflect economic reality, so divisional results are measured fairly and company-wide decisions are made on reliable information.

The objectives of transfer pricing are as follows:

  • Accurate performance evaluation: To ensure that the performance of individual units or divisions is evaluated fairly by assigning an appropriate value to the goods or services they exchange.
  • Fair cost allocation: To allocate costs appropriately among different units, enabling better transparency and accountability within the organization.
  • Tax compliance: To meet regulatory requirements and ensure compliance with tax laws and transfer pricing guidelines in various jurisdictions.
  • Financial reporting accuracy: To produce financial reports that accurately reflect the financial performance of each division and the organization as a whole.
  • Support strategic decision-making: To enable the organization to make informed decisions regarding resource allocation, pricing strategies, and investment opportunities.

Methods of determining transfer prices

1. Cost-based pricing methods

1.1. Variable cost price

The variable cost method sets the transfer price equal to the variable costs incurred to produce a good or service. This approach ensures that the receiving division is not burdened with fixed costs and reflects the true incremental cost of production.

Transfer price=variable cost per unit

It is simple to calculate, encourages marginal cost decision-making, and ensures transparency in cost control. When using this method, it is generally advisable to base the transfer price on standard variable costs. This approach ensures that any inefficiencies in the production process remain with the supplying division and are not unfairly transferred to the buying division. By isolating inefficiencies, the buying division can better focus on its own operations without being impacted by cost overruns from the supplying division.

Disadvantages:

  • Does not cover fixed costs, potentially leading to under-recovery for the supplying division.
  • Discourages long-term profitability analysis.
  • May lead to disputes if fixed costs are significant for overall operations.

1.2. Full cost price

The full cost method incorporates both variable and fixed costs into the transfer price. This approach ensures that all production costs are covered, making it particularly useful for long-term planning and profitability analysis.

Transfer price=variable cost per unit+fixed cost allocation per unit

Full cost pricing provides a comprehensive view of production expenses and promotes fairness in cost recovery for the supplying division. As with variable cost, use standard (not actual) full cost so the supplying division’s inefficiencies are not passed to the buyer.

Disadvantages:

  • Subjective allocation of fixed costs can cause disputes.
  • Higher transfer prices may reduce competitiveness for the receiving division.
  • Discourages marginal decision-making.

1.3. Cost-plus price

The cost-plus method adds a predetermined markup to the production cost, which can be based on variable or full costs.

Transfer price = cost per unit (variable or full) + markup

This approach encourages profitability for the supplying division while reflecting fair value for internal transactions. Cost-plus pricing is flexible and widely used across different industries to ensure cost recovery and incentivize internal suppliers.

Disadvantages:

  • Subjectivity in determining the markup can lead to inconsistencies.
  • May inflate transfer prices, reducing the receiving division’s profitability.

2. Market price method

The market price method sets the transfer price based on the price at which the goods or services could be sold externally. If no external demand exists, the price of a similar product in the market can be used.

Transfer price = market price (or adjusted market price)

Adjustments can be made for cost savings, such as reduced selling expenses, when transactions occur internally. This method encourages market-based decision-making, reduces internal disputes, and provides a clear benchmark for divisional performance.

Disadvantages:

  • Not feasible if no external market or comparable product exists.
  • Adjustments to market price may introduce subjectivity.
  • High transfer prices can reduce the competitiveness of the receiving division.

3. Negotiated price method

The negotiated price method allows divisions to negotiate a mutually agreed transfer price.

Transfer price = agreed price between divisions

This method fosters collaboration and ensures both divisions’ goals are considered, providing flexibility to adapt to unique circumstances. It reflects economic realities and avoids rigid pricing structures, making it suitable for organizations with diverse operational priorities.

Disadvantages:

  • Time-consuming and prone to conflicts during negotiations.
  • May lead to imbalances if one division has more negotiating power.
  • Requires strong managerial oversight to prevent disputes.

4. Dual pricing method

The dual pricing method involves recording different transfer prices for the selling and receiving divisions. For instance, the selling division may record the transfer at the market price, ensuring it recovers its full costs, while the receiving division records it at variable cost, reflecting cost savings from internal transactions.

Selling division price = market price

Receiving division price = variable cost price

This method reduces internal disputes and promotes divisional harmony. However, because the seller records more revenue than the buyer records as cost, the sum of divisional profits exceeds companywide profit, so the difference must be eliminated at headquarters. It’s important to note that the policies governing this approach are determined by the organization. The dual-pricing method simply involves using two different prices for the same transaction: one for the selling division and another for the buying division.

Disadvantages:

  • It can be more complex to implement and reconcile.
  • Raises potential tax compliance issues, especially in multinational operations.
  • The selling division has less incentive to control costs, since it recovers its price regardless of efficiency.

Example: Calculating transfer prices

Division A produces a component with a variable cost of $40 per unit and a fixed cost allocation of $15 per unit. Division A can sell the component externally at a market price of $80 per unit, but selling to Division B internally saves $5 per unit in selling costs. Division A’s cost-plus policy applies a 20% markup to full cost.

  • Variable cost price: $40
  • Full cost price: $40 + $15 = $55
  • Cost-plus price: $55 × 1.20 = $66
  • Adjusted market price: $80 − $5 = $75
  • Dual pricing: the selling division records $75 (market price) and the receiving division records $40 (variable cost)
  • Negotiated price: any price the two divisions agree on, typically between $40 (the selling division’s floor: its variable cost, when it has idle capacity) and $80 (the buying division’s ceiling: the market price it would pay an outside supplier)

Answer: Variable cost = $40; full cost = $55; cost-plus = $66; adjusted market = $75; dual pricing = $75 (seller) / $40 (buyer); negotiated price falls between $40 and $80.

Business considerations such as the presence of outside suppliers, idle versus full capacity, and special multinational issues like tariffs, exchange rates, taxes, currency restrictions, and expropriation risk also shape transfer pricing decisions - we cover these in the next chapter, Transfer pricing and business issues.

Transfer pricing basics

  • Transfer pricing (TP): internal price for goods/services/assets moved between divisions or related entities
  • Poorly set prices distort divisional performance (too low hurts seller’s reported profit, too high hurts buyer’s)
  • Key objectives: accurate performance evaluation, fair cost allocation, tax compliance, accurate financial reporting, support strategic decisions

Cost-based pricing methods

  • Variable cost: Transfer price=variable cost per unit
    • Use standard variable cost so seller’s inefficiencies aren’t passed to buyer
    • Pro: simple, supports marginal decision-making; Con: ignores fixed costs, discourages long-term profitability view
  • Full cost: Transfer price=variable cost per unit+fixed cost allocation per unit
    • Pro: recovers all costs, good for long-term planning; Con: fixed cost allocation is subjective, can reduce buyer competitiveness
  • Cost-plus: Transfer price = cost per unit (variable or full)+markup
    • Pro: incentivizes seller profitability; Con: markup subjectivity can inflate price, hurt buyer margins

Market price method

  • Transfer price = market price (or adjusted market price), adjusted for internal savings (e.g., avoided selling costs)
  • Pro: objective benchmark, reduces disputes, encourages market-based decisions
  • Con: requires an external market/comparable product; adjustments add subjectivity; high price can hurt buyer competitiveness

Negotiated price method

  • Transfer price = agreed price between divisions, typically bounded between seller’s variable cost (floor) and market price (ceiling)
  • Pro: flexible, reflects real economics, encourages cooperation
  • Con: time-consuming, risk of power imbalance, needs managerial oversight

Dual pricing method

  • Seller records transfer at market price: Selling division price = market price
  • Buyer records transfer at variable cost: Receiving division price = variable cost price
  • Pro: reduces internal conflict, lets seller fully recover costs while buyer gets cost benefit
  • Con: sum of divisional profits exceeds total company profit (must reconcile at HQ), complex to implement, raises tax compliance concerns, weakens seller’s cost-control incentive

Applying the methods (example takeaway)

  • Same transaction yields different prices depending on method (e.g., variable cost $40, full cost $55, cost-plus $66, adjusted market $75, negotiated range $40–$80)
  • Choice of method affects divisional profit reporting and must align with company objectives

Broader business/multinational considerations (preview)

  • Real-world TP decisions also affected by: presence of outside suppliers, idle vs. full capacity/opportunity cost, and multinational factors (tariffs, exchange rates, taxes, currency restrictions, expropriation risk, resource/skill availability) — detailed in next chapter

Sign up for free to take 10 quiz questions on this topic

Previous
Next  | 3.2.4.2 Transfer pricing and business issues
All rights reserved ©2016 - 2026 Achievable, Inc.

Transfer pricing objectives and methods

Learning outcome statements

The learning outcome statements relevant for this section are:

  1. define transfer pricing and identify the objectives of transfer pricing
  2. identify the methods for determining transfer prices, and list and explain the advantages and disadvantages of each method
  3. calculate transfer prices using variable cost, full cost, market price, negotiated price, and dual-rate pricing
  4. explain how transfer pricing is affected by business issues, such as the presence of outside suppliers and the opportunity costs associated with capacity usage
  5. describe how special issues such as tariffs, exchange rates, taxes, currency restrictions, expropriation risk, and the availability of materials and skills affect performance evaluation in multinational companies

Objectives of transfer pricing

Definitions
Transfer pricing (TP)
The practice of determining the value of goods, services, or intangible assets transferred between different units or divisions within the same organization.

Transfer pricing establishes an internal price for transactions occurring between related entities, such as a parent company and its subsidiaries or between divisions of the same company. Effective transfer pricing ensures accurate representation of the economic value of intercompany transactions.

Consider a manufacturing company with two divisions: Division A produces a component (Product A) that is used by Division B in assembling the final product. Division A has two choices: it can sell the component to external customers at the market price, or it can transfer the component internally to Division B at an agreed transfer price.

The transfer price directly affects how each division’s performance is measured. If the transfer price is set too low, Division A may appear less profitable even though it is efficient, while Division B will benefit from lower input costs. If the transfer price is set too high, Division B may appear unprofitable despite creating value for the company as a whole.

This illustrates why transfer pricing is important: it ensures that intercompany transactions reflect economic reality, so divisional results are measured fairly and company-wide decisions are made on reliable information.

The objectives of transfer pricing are as follows:

  • Accurate performance evaluation: To ensure that the performance of individual units or divisions is evaluated fairly by assigning an appropriate value to the goods or services they exchange.
  • Fair cost allocation: To allocate costs appropriately among different units, enabling better transparency and accountability within the organization.
  • Tax compliance: To meet regulatory requirements and ensure compliance with tax laws and transfer pricing guidelines in various jurisdictions.
  • Financial reporting accuracy: To produce financial reports that accurately reflect the financial performance of each division and the organization as a whole.
  • Support strategic decision-making: To enable the organization to make informed decisions regarding resource allocation, pricing strategies, and investment opportunities.

Methods of determining transfer prices

1. Cost-based pricing methods

1.1. Variable cost price

The variable cost method sets the transfer price equal to the variable costs incurred to produce a good or service. This approach ensures that the receiving division is not burdened with fixed costs and reflects the true incremental cost of production.

Transfer price=variable cost per unit

It is simple to calculate, encourages marginal cost decision-making, and ensures transparency in cost control. When using this method, it is generally advisable to base the transfer price on standard variable costs. This approach ensures that any inefficiencies in the production process remain with the supplying division and are not unfairly transferred to the buying division. By isolating inefficiencies, the buying division can better focus on its own operations without being impacted by cost overruns from the supplying division.

Disadvantages:

  • Does not cover fixed costs, potentially leading to under-recovery for the supplying division.
  • Discourages long-term profitability analysis.
  • May lead to disputes if fixed costs are significant for overall operations.

1.2. Full cost price

The full cost method incorporates both variable and fixed costs into the transfer price. This approach ensures that all production costs are covered, making it particularly useful for long-term planning and profitability analysis.

Transfer price=variable cost per unit+fixed cost allocation per unit

Full cost pricing provides a comprehensive view of production expenses and promotes fairness in cost recovery for the supplying division. As with variable cost, use standard (not actual) full cost so the supplying division’s inefficiencies are not passed to the buyer.

Disadvantages:

  • Subjective allocation of fixed costs can cause disputes.
  • Higher transfer prices may reduce competitiveness for the receiving division.
  • Discourages marginal decision-making.

1.3. Cost-plus price

The cost-plus method adds a predetermined markup to the production cost, which can be based on variable or full costs.

Transfer price = cost per unit (variable or full) + markup

This approach encourages profitability for the supplying division while reflecting fair value for internal transactions. Cost-plus pricing is flexible and widely used across different industries to ensure cost recovery and incentivize internal suppliers.

Disadvantages:

  • Subjectivity in determining the markup can lead to inconsistencies.
  • May inflate transfer prices, reducing the receiving division’s profitability.

2. Market price method

The market price method sets the transfer price based on the price at which the goods or services could be sold externally. If no external demand exists, the price of a similar product in the market can be used.

Transfer price = market price (or adjusted market price)

Adjustments can be made for cost savings, such as reduced selling expenses, when transactions occur internally. This method encourages market-based decision-making, reduces internal disputes, and provides a clear benchmark for divisional performance.

Disadvantages:

  • Not feasible if no external market or comparable product exists.
  • Adjustments to market price may introduce subjectivity.
  • High transfer prices can reduce the competitiveness of the receiving division.

3. Negotiated price method

The negotiated price method allows divisions to negotiate a mutually agreed transfer price.

Transfer price = agreed price between divisions

This method fosters collaboration and ensures both divisions’ goals are considered, providing flexibility to adapt to unique circumstances. It reflects economic realities and avoids rigid pricing structures, making it suitable for organizations with diverse operational priorities.

Disadvantages:

  • Time-consuming and prone to conflicts during negotiations.
  • May lead to imbalances if one division has more negotiating power.
  • Requires strong managerial oversight to prevent disputes.

4. Dual pricing method

The dual pricing method involves recording different transfer prices for the selling and receiving divisions. For instance, the selling division may record the transfer at the market price, ensuring it recovers its full costs, while the receiving division records it at variable cost, reflecting cost savings from internal transactions.

Selling division price = market price

Receiving division price = variable cost price

This method reduces internal disputes and promotes divisional harmony. However, because the seller records more revenue than the buyer records as cost, the sum of divisional profits exceeds companywide profit, so the difference must be eliminated at headquarters. It’s important to note that the policies governing this approach are determined by the organization. The dual-pricing method simply involves using two different prices for the same transaction: one for the selling division and another for the buying division.

Disadvantages:

  • It can be more complex to implement and reconcile.
  • Raises potential tax compliance issues, especially in multinational operations.
  • The selling division has less incentive to control costs, since it recovers its price regardless of efficiency.

Example: Calculating transfer prices

Division A produces a component with a variable cost of $40 per unit and a fixed cost allocation of $15 per unit. Division A can sell the component externally at a market price of $80 per unit, but selling to Division B internally saves $5 per unit in selling costs. Division A’s cost-plus policy applies a 20% markup to full cost.

  • Variable cost price: $40
  • Full cost price: $40 + $15 = $55
  • Cost-plus price: $55 × 1.20 = $66
  • Adjusted market price: $80 − $5 = $75
  • Dual pricing: the selling division records $75 (market price) and the receiving division records $40 (variable cost)
  • Negotiated price: any price the two divisions agree on, typically between $40 (the selling division’s floor: its variable cost, when it has idle capacity) and $80 (the buying division’s ceiling: the market price it would pay an outside supplier)

Answer: Variable cost = $40; full cost = $55; cost-plus = $66; adjusted market = $75; dual pricing = $75 (seller) / $40 (buyer); negotiated price falls between $40 and $80.

Business considerations such as the presence of outside suppliers, idle versus full capacity, and special multinational issues like tariffs, exchange rates, taxes, currency restrictions, and expropriation risk also shape transfer pricing decisions - we cover these in the next chapter, Transfer pricing and business issues.

Key points

Transfer pricing basics

  • Transfer pricing (TP): internal price for goods/services/assets moved between divisions or related entities
  • Poorly set prices distort divisional performance (too low hurts seller’s reported profit, too high hurts buyer’s)
  • Key objectives: accurate performance evaluation, fair cost allocation, tax compliance, accurate financial reporting, support strategic decisions

Cost-based pricing methods

  • Variable cost: Transfer price=variable cost per unit
    • Use standard variable cost so seller’s inefficiencies aren’t passed to buyer
    • Pro: simple, supports marginal decision-making; Con: ignores fixed costs, discourages long-term profitability view
  • Full cost: Transfer price=variable cost per unit+fixed cost allocation per unit
    • Pro: recovers all costs, good for long-term planning; Con: fixed cost allocation is subjective, can reduce buyer competitiveness
  • Cost-plus: Transfer price = cost per unit (variable or full)+markup
    • Pro: incentivizes seller profitability; Con: markup subjectivity can inflate price, hurt buyer margins

Market price method

  • Transfer price = market price (or adjusted market price), adjusted for internal savings (e.g., avoided selling costs)
  • Pro: objective benchmark, reduces disputes, encourages market-based decisions
  • Con: requires an external market/comparable product; adjustments add subjectivity; high price can hurt buyer competitiveness

Negotiated price method

  • Transfer price = agreed price between divisions, typically bounded between seller’s variable cost (floor) and market price (ceiling)
  • Pro: flexible, reflects real economics, encourages cooperation
  • Con: time-consuming, risk of power imbalance, needs managerial oversight

Dual pricing method

  • Seller records transfer at market price: Selling division price = market price
  • Buyer records transfer at variable cost: Receiving division price = variable cost price
  • Pro: reduces internal conflict, lets seller fully recover costs while buyer gets cost benefit
  • Con: sum of divisional profits exceeds total company profit (must reconcile at HQ), complex to implement, raises tax compliance concerns, weakens seller’s cost-control incentive

Applying the methods (example takeaway)

  • Same transaction yields different prices depending on method (e.g., variable cost $40, full cost $55, cost-plus $66, adjusted market $75, negotiated range $40–$80)
  • Choice of method affects divisional profit reporting and must align with company objectives

Broader business/multinational considerations (preview)

  • Real-world TP decisions also affected by: presence of outside suppliers, idle vs. full capacity/opportunity cost, and multinational factors (tariffs, exchange rates, taxes, currency restrictions, expropriation risk, resource/skill availability) — detailed in next chapter

More from Transfer pricing

  • Transfer pricing and business issues